


EN
3 U.S. Defense Stocks Investors May Revisit Before The 2026 Election
Markets are already on edge heading into the 2026 U.S. elections, and the fresh legal fight over Alaska’s Senate race adds another layer of political risk that investors cannot ignore. When uncertainty around who controls Congress rises, money often shifts across sectors as traders rethink spending, regulation, and safe havens. This article examines three U.S. defense and security stocks exposed to that story and explains how this backdrop could reshape their risk and appeal.
The three stocks profiled next are only a starter set, and the full screen surfaced 57 more U.S. defense and security companies with equally compelling narratives that this article does not cover. If you want to move past headlines and actually compare the sector on your own terms, head straight into the U.S. Defense and Security Stocks screener to identify, analyze, and focus on your highest conviction ideas.
Tutor Perini (TPC)
Overview: Tutor Perini is a long-established construction and design-build contractor that delivers large public infrastructure, government facilities, and complex private projects, giving investors indirect exposure to U.S. defense and security-related spending through major civil and building works.
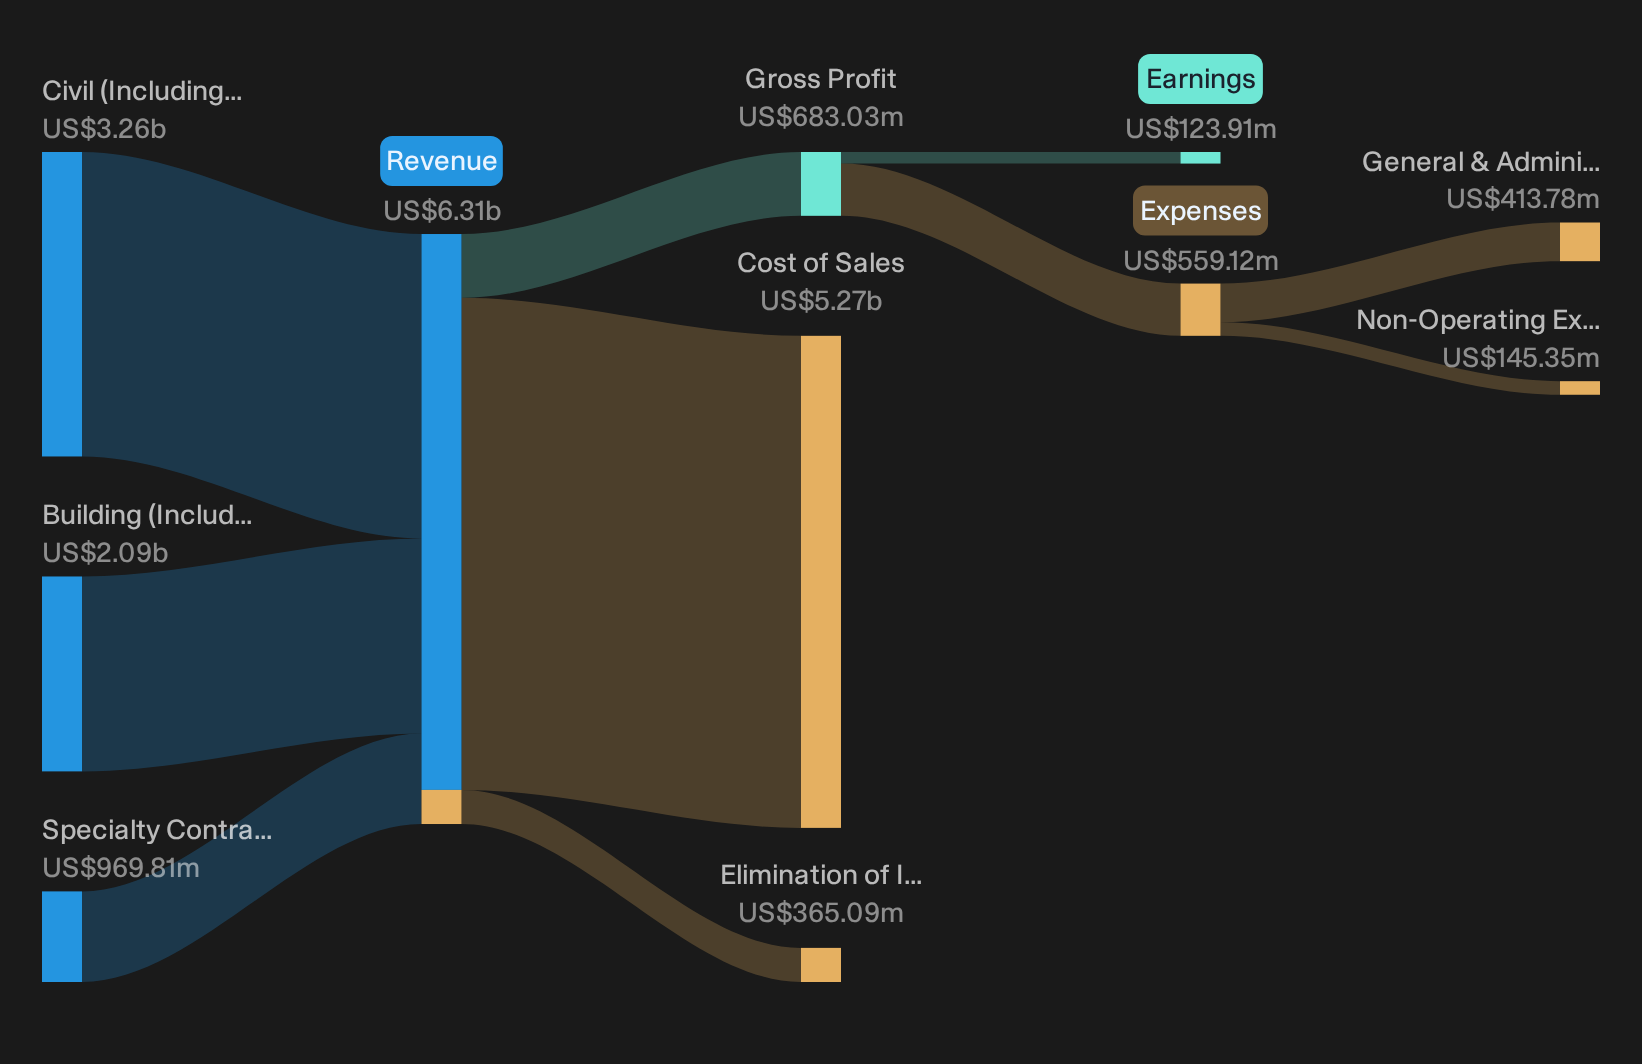
Operations: Tutor Perini generates about US$3.3b from Civil, US$2.1b from Building, and US$969.8m from Specialty Contractors, with roughly US$5.5b earned in the United States.
Market Cap: US$4.0b
Tutor Perini matters in a U.S. defense and security screen because its big-ticket public works, military-related facilities, and secure infrastructure projects lean heavily on long term government funding cycles that can look especially relevant when Washington risk premiums rise.
"Although Tutor Perini highlights nine large projects totaling about US$16b with better contractual terms and higher expected margins, the July 2026 US$42.4m judgment tied to the W and Element hotels shows that legacy disputes can still absorb cash from this mega project shift and could weigh on net margins and earnings quality as these projects ramp."
What ultimately happens to Tutor Perini’s margins and investor confidence may hinge on how one unresolved pressure shapes the cash coming off that backlog.
That cash squeeze question is exactly what the full narrative for Tutor Perini unpacks, including how those mega projects could reshape Tutor Perini’s risk profile and upside potential.
HawkEye 360 (HAWK)
Overview: HawkEye 360 runs a satellite based radio frequency intelligence network that supplies defense and security agencies with shareable, mission ready surveillance data.
Operations: HawkEye 360 generates about US$167.6 million from Aerospace & Defense, with roughly US$96.8 million from the United States and US$70.8 million from international clients.
Market Cap: US$1.2b
HawkEye 360 fits this defense and security screen because it operates in the path of rising demand for space based surveillance data that governments can plug into real world operations when political and geopolitical risks climb.
"Growing global focus on electromagnetic spectrum awareness for missions such as maritime domain awareness and long range fires is aligning directly with HawkEye 360's RF intelligence offering."
What happens to HawkEye 360’s future margins and contract depth may depend on how one unseen pressure shapes that long term demand curve.
That hidden pressure is exactly where the full narrative for HawkEye 360 shows how HawkEye 360’s RF network could convert spectrum demand into accelerating contracts, while gaps in execution still matter.

Cadre Holdings (CDRE)
Overview: Cadre Holdings supplies protective gear and equipment for law enforcement, first responders, and government agencies, linking directly to homeland security spending.
Operations: Cadre Holdings generates about US$621.5 million from Product and US$98.9 million from Distribution, with most revenue coming from the United States.
Market Cap: US$1.3b
Cadre Holdings matters in this defense and security screen because it sits where public safety budgets meet the everyday gear frontline professionals rely on.
"While record orders in armor, duty gear and EOD suggest continued demand for mission critical public safety equipment, the sharp fall in Q1 2026 net income to about US$2.0 million from US$9.2 million a year earlier and a 2.6% annual EPS contraction over two years indicate that higher volumes may still translate into weaker per share profitability if cost, mix and interest burdens persist, limiting the benefit to net margins and earnings."
This raises the question of how a single capital allocation choice can shift how much of that resilient demand actually reaches Cadre Holdings’ bottom line.
That capital decision point is exactly what the full narrative for Cadre Holdings unpacks, revealing how Cadre Holdings could convert steady demand into accelerating earnings power while managing the cost and interest drag.

Seeking Fresh Alternatives Before They Fly
New ideas can move from quiet to breakout faster than most investors react. Catch fresh momentum while it matters, before the crowd, and get in early.
- Track cash rich businesses built for staying power and quickly scan a curated list of solid balance sheet and fundamentals (24 results) that keeps weakness from slipping into your watchlist.
- Ride structural demand in electricity and infrastructure and pull forward opportunities inside the curated 42 power grid technology and infrastructure stocks before attention floods into the same tickers.
- Target companies participating in the AI infrastructure trend and move through the hand picked 55 AI infrastructure stocks while pricing still reflects today, not yesterday’s headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com