


EN
Federated Hermes (FHI), Why Is Fresh Attention Building Around It?
Federated Hermes (FHI) just moved deeper into digital assets through a new partnership with Prometheum, aiming to distribute tokenized fund products over SEC-registered broker-dealer infrastructure.
Recent trading has been choppy for Federated Hermes, with the share price down 1.5% over the past day and roughly 4% lower over the last 90 days, even as the year to date share price return of 8.5% and a 1 year total shareholder return of 21.1% point to momentum that has built over a longer stretch. Against that backdrop, this push into tokenized funds with Prometheum feeds into a wider story where the stock has already delivered a very large 3 year total shareholder return of about 2x and a 5 year total shareholder return a little above that. This suggests investors have been willing to reprice the business as it leans into new product formats and perceived growth areas in asset management.
Scan how Federated Hermes fits into the broader opportunity in asset managers that are leaning into new structures by running your filters across 21 high quality undiscovered gems with similar fundamentals and under-the-radar storylines.
Federated Hermes now trades at a modest discount to both analyst targets and an internal fair value estimate after announcing this tokenized funds push. Is that gap a cautious market correctly pricing risk, or an overreaction that misreads the opportunity in digital infrastructure?
Most Popular Narrative: 7% Undervalued
Federated Hermes last closed at $56.81, against a widely followed fair value narrative of $61.00. This frames the current 7% discount as relatively modest and leaves little room for big misreads on valuation.
The key factor is that growth in equity, ETF, and alternative private markets assets continues to offset periods of softer money market flows and higher operating expenses from acquisitions and expansion. The current valuation and recent share price strength indicate that investors already view Federated Hermes as a high quality asset manager with strong profitability, consistent shareholder returns, and limited room for disappointment.
See why 8 investors see Federated Hermes as 7% undervalued.
Result: Fair Value of $61 (UNDERVALUED)
Still, fee pressure on active strategies and any renewed slippage in money market fund share could quickly weaken the Federated Hermes valuation story that investors are leaning on.
Find out about the key risks to this Federated Hermes narrative.
Another View: What The P/E Ratio Says About Federated Hermes
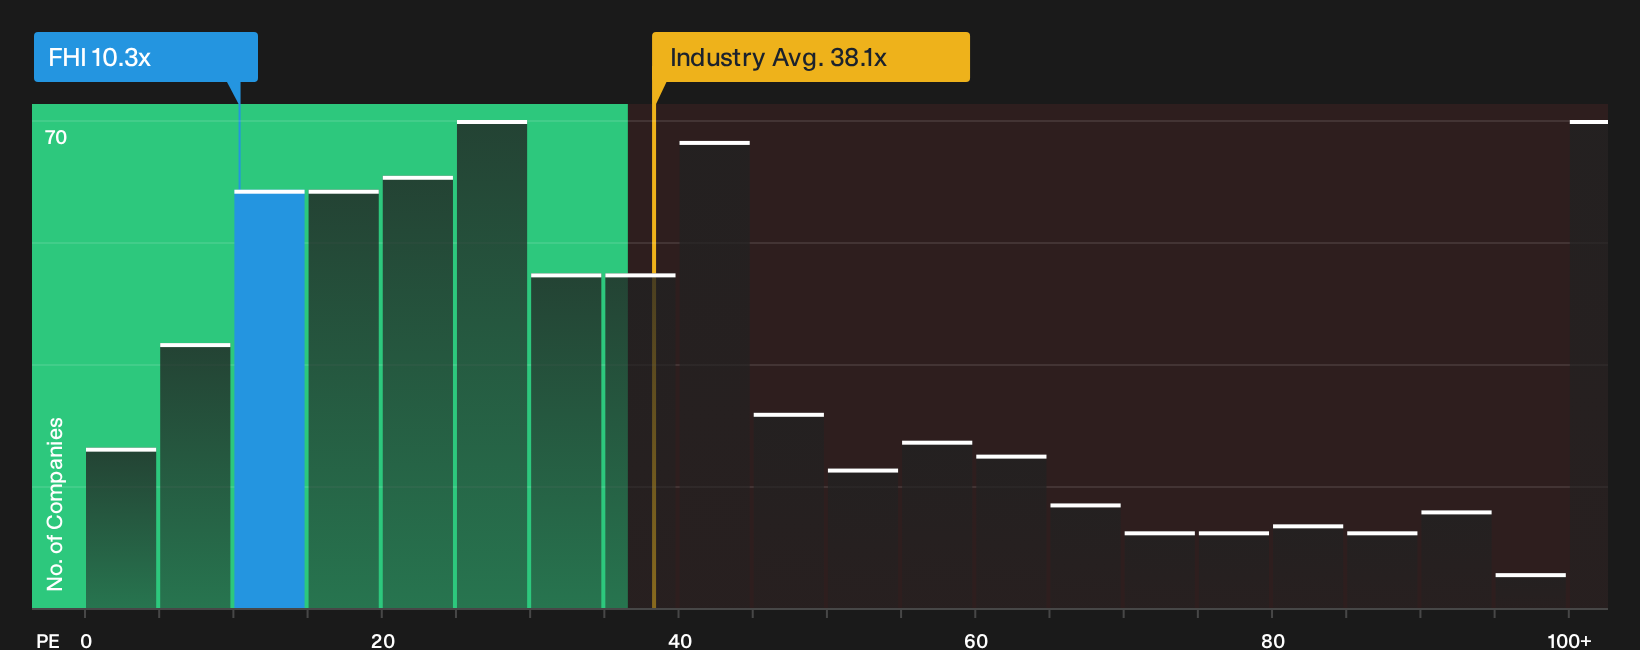
The first narrative leans on fair value estimates and cash flow, yet the plain P/E story for Federated Hermes is more mixed. The stock trades on 10.3x earnings, very close to a fair ratio of 9.8x, which suggests there may be limited margin for error if expectations slip.
Set against that, the same 10.3x P/E is below a 12.8x peer average and well below the wider US Capital Markets group on 38.1x. The gap points to a market that pays less for each dollar of FHI earnings, so the key question is whether that discount reflects risk or a potential opening for patient investors.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Federated Hermes so far. Act while the debate is fresh and weigh the trade off yourself using the 3 key rewards and 1 important warning sign.
Looking for more Federated Hermes style investment ideas?
If you want to turn this Federated Hermes research into a broader watchlist, use focused stock lists that filter for quality so you are not sifting blindly.
- Target resilient outcomes first and scan a curated set of companies with lower risk profiles through the 30 resilient stocks with low risk scores.
- Prioritize financial strength and run through a list of solid balance sheet and fundamentals (24 results) so you can focus on businesses with sturdier foundations.
- Hunt for future standouts by reviewing a 7 elite penny stocks with strong financials that surfaces smaller players with the potential to reshape your opportunity set.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com