


EN
Should Earnings Beat Require Action From U.S. Bancorp (USB) Investors?
- U.S. Bancorp reported third quarter 2026 net interest income of US$4,468 million and net income of US$2,202 million, alongside higher earnings per share compared with the same period in 2025.
- Management raised full year 2026 total net revenue growth guidance to a range of 8% to 9% and signaled fee driven momentum, with BTIG contributing meaningfully to projected fourth quarter fee expansion.
- We will explore how U.S. Bancorp's stronger earnings and upgraded revenue outlook reshape the existing investment narrative around fee growth and efficiency.
U.S. Bancorp Investment Narrative Recap
To own U.S. Bancorp, you need to believe that its mix of net interest income and fees can support steady earnings while credit costs and competition stay manageable. The raised 2026 revenue guidance and solid third quarter earnings keep that core story intact. The key near term swing factor remains execution on fee growth and cost control rather than these bond deals.
The fresh fixed income and preferred offerings add funding and capital flexibility but look modest next to a US$92.8b market cap and multi billion dollar balance sheet. They do not materially change the biggest current risk, which is pressure on loan quality or regional economies that could force higher provisions and dent profitability.
The US$1b perpetual preferred depositary share issue is the most relevant piece of recent news. It adds an extra layer of capital that can support loan books, fee investments and the BTIG platform. For you as a shareholder, this matters because it influences how confidently U.S. Bancorp can lean into growth opportunities while still meeting regulatory requirements.
Set against the bond issuances, that preferred deal is the one that ties closest to the existing catalysts in capital markets and payments. It supports the narrative of a bank that wants fee income closer to half of revenue and is willing to use multiple funding tools to keep lending, payments initiatives and technology projects moving without straining its capital ratios.
U.S. Bancorp's narrative projects US$37.8b revenue and US$9.1b earnings by 2029. This assumes 10.7% yearly revenue growth and about a US$1.1b earnings increase from US$8.0b today.
Uncover why U.S. Bancorp's fair value indicates a 15% potential upside to its current price that may not last much longer.
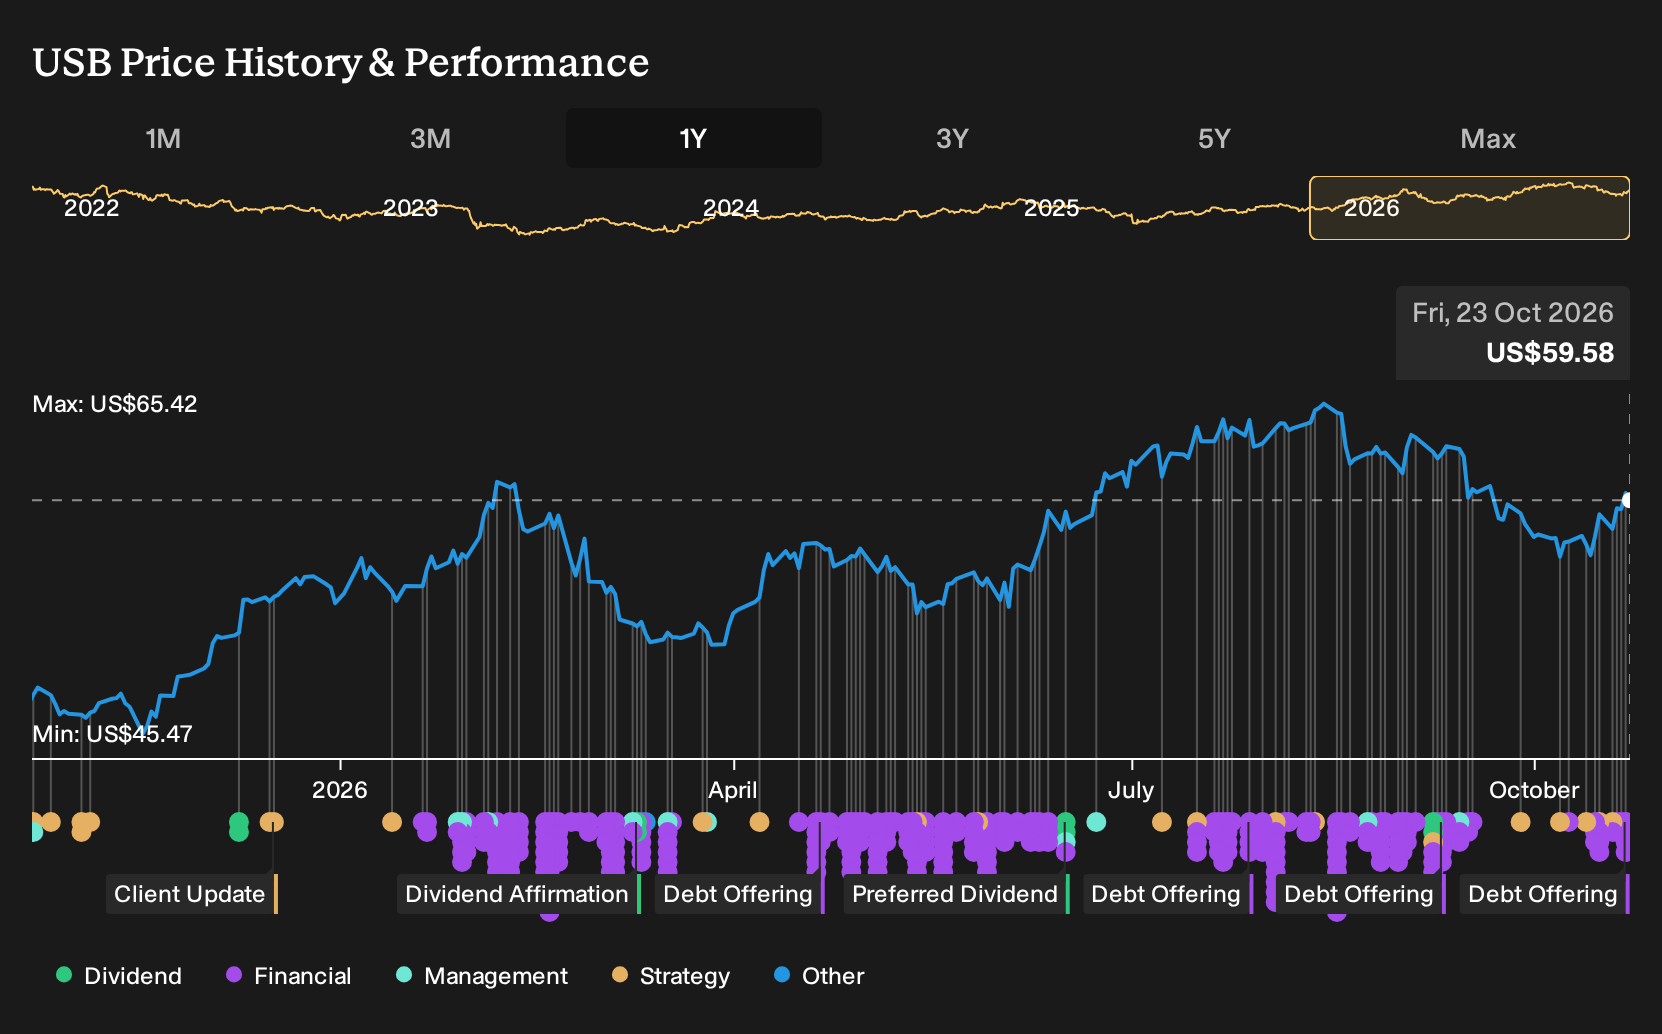
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span roughly US$58 to US$111 per share. This range places U.S. Bancorp in very different territory depending on whose model you trust. You see that spread before the recent preferred and bond issuance or new payment features, so use it to cross check several contrasting views.
Explore 4 other U.S. Bancorp fair value estimates, including one that suggests it could be worth just $58.09.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your U.S. Bancorp research is our analysis highlighting 4 key rewards that could inform your investment assessment.
- See our latest analysis for U.S. Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review U.S. Bancorp's overall financial profile at a glance.
Looking For More Investment Ideas Beyond U.S. Bancorp?
If U.S. Bancorp has sharpened your thinking around banks and balance sheets, you can use that momentum to compare it with other listed businesses that share the qualities you care about most.
- If you prefer companies with strong fundamentals and sturdy finances, start by scanning a curated list of solid balance sheet and fundamentals (24 results) to see which businesses fit that profile.
- If lower volatility and resilience matter more to you than rapid growth, you can filter for stocks through a focused 30 resilient stocks with low risk scores that screens for calmer return profiles.
- If you are hunting for under appreciated opportunities with solid quality markers, put your criteria to work using a targeted 21 high quality undiscovered gems that surfaces lesser known ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com