


EN
Dropbox (DBX), Why Is The Stock Back In The Spotlight?
Dropbox (DBX) drew fresh attention on October 23, 2026, after its Class A shares gained 0.93%, extending a 5-day winning streak that followed a technical buy signal earlier in the month.
That technical upswing comes on top of a stronger run for Dropbox, with a 30-day share price return of 17.05% and a year-to-date share price gain of 40.48%, while total shareholder return over three years is 45.84%, indicating momentum that investors are still willing to support.
Scan the market for other software stocks showing similar momentum traits to Dropbox with our hand-picked 21 high quality undiscovered gems.
Bulls point to Dropbox’s recent surge and sizeable implied discount to some value estimates. Bears focus on modest revenue growth and a price already above analyst targets. Which side does the valuation actually support?
Most Popular Narrative: 19% Overvalued
Dropbox closed at $37.83 while the most followed narrative pegs fair value at $31.80, so the recent rally sits above that model with the discount rate set at 10.04% for those projected cash flows.
The main thing that has to go right is that Dropbox turns its AI products and Protect security offerings into durable user growth and adoption while keeping infrastructure costs and security risks under control.
The numbers imply a share price that already reflects a fairly valued, bullish view on Dropbox, with strong cash generation and buybacks offset by questions about how much AI success is realistically embedded in the stock.
See why 10 investors see Dropbox as 19% overvalued.
Result: Fair Value of $31.80 (OVERVALUED)
Still, that story can crack if AI features keep pressuring gross margins without a clear revenue payoff, or if further security issues erode trust in Dropbox.
Find out about the key risks to this Dropbox narrative.
Another View: Multiples Paint a Different Picture for Dropbox
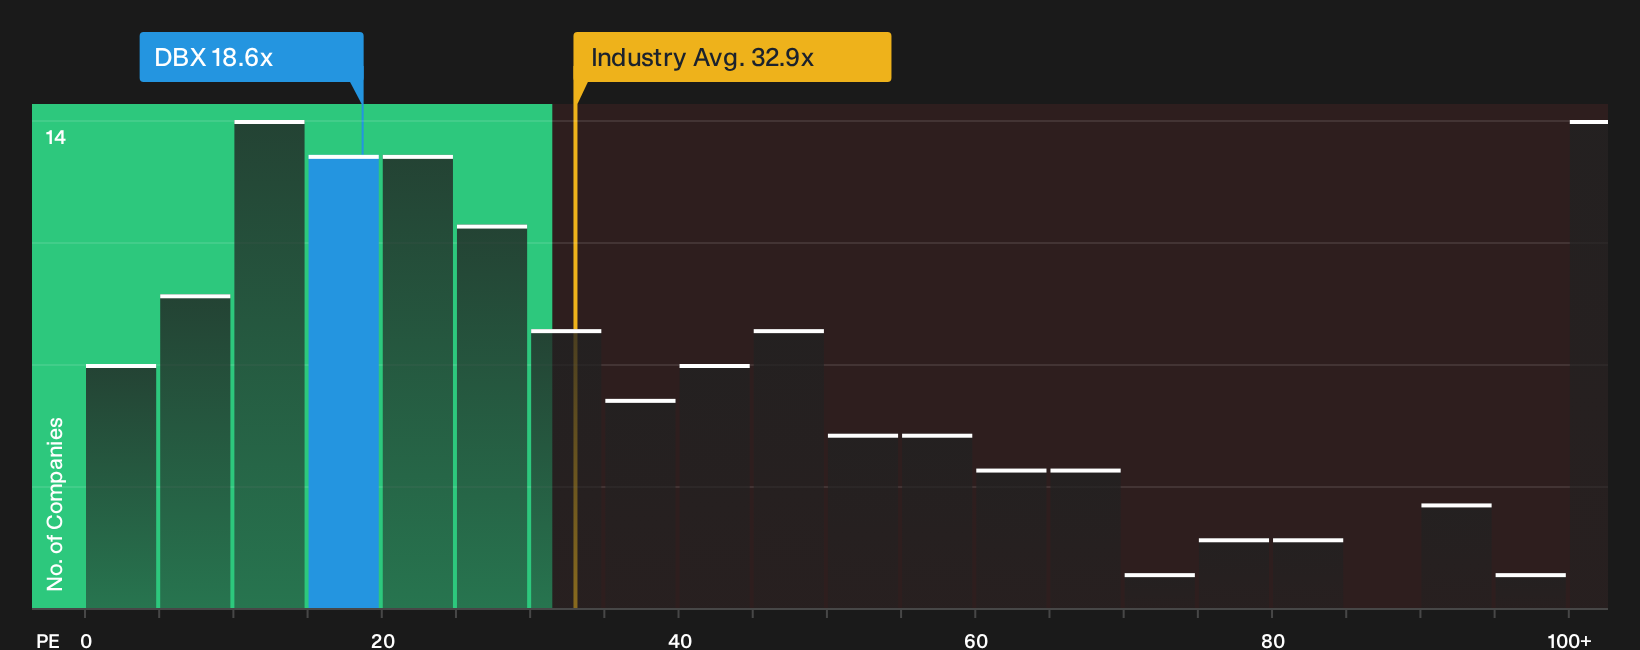
The overvalued narrative hinges on a fair value of $31.80, yet Dropbox trades on a P/E of 18.6x compared with a fair ratio of 21.6x and a US Software industry average of 33.7x. That points to a stock priced more conservatively than both its peers and the ratio the market could move towards, which raises the question of whether the perceived premium is really in the multiples at all.
To see how this ratio based view holds up under a closer lens, check the valuation breakdown in our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With Dropbox sentiment clearly split between overvaluation worries and value upside, move quickly and test the narrative against your own checklist using our breakdown of 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Dropbox?
Do not stop at one story. Use the Simply Wall St Screener to line up fresh ideas that fit the way you like to invest.
- Target potential value opportunities by scanning a focused list of 29 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Prioritise resilience by hunting through 30 resilient stocks with low risk scores that score well on stability so you are not relying on luck when volatility picks up.
- Zero in on balance sheet strength through a tailored list of solid balance sheet and fundamentals (24 results) that helps you avoid fragile businesses before problems show up in the headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com