


EN
Is Record Earnings Altering The Investment Case For Eastern Bankshares Stock?
- Eastern Bankshares reported third quarter 2026 net interest income of US$257.9 million and net income of US$111 million, alongside a quarterly dividend of US$0.15 per share and US$5.2 million of net loan charge offs.
- For the first nine months of 2026, Eastern Bankshares moved from a prior year loss to net income of US$281.5 million, highlighting how its operating model and merger integrations are influencing reported profitability.
- The impact of Eastern Bankshares' record operating earnings in the latest quarter on its broader investment narrative remains to be seen.
Compare Eastern Bankshares' record quarter with other banks that are demonstrating strong earnings power and disciplined balance sheets using our curated list of list of solid balance sheet and fundamentals (24 results).
Eastern Bankshares Investment Narrative Recap
To own Eastern Bankshares, you need to be comfortable with a regional bank that is leaning into commercial and industrial lending, wealth services, and merger integrations to drive earnings. The big near term swing factor is whether that record operating quarter can continue to offset higher funding costs as deposit competition in New England stays intense.
The key risk is that deposit pricing and softer loan demand push net interest income toward the low end of the reduced 2026 guidance range. The Q3 record, combined with lower net loan charge offs of US$5.2 million, supports the existing earnings narrative rather than changing the short term story.
The dividend affirmation at US$0.15 per share is the most relevant recent announcement for this earnings update. It indicates that management is keeping capital returns steady while still working through merger integration and a loan book that is shifting further toward relationship based commercial lending and away from slower residential mortgage balances.
For catalysts, that payout sits alongside ongoing share repurchases and the multi year repricing of loans and securities that management has highlighted. The risk side is that higher deposit costs or weaker spread income could force tougher trade offs between dividend consistency, buybacks, and organic growth ambitions for Eastern Bankshares.
Eastern Bankshares Earnings Assumptions And Valuation Link
Analyst models around Eastern Bankshares help frame what that record quarter needs to support over time. The forecasts roll current profitability into longer term assumptions on revenue, earnings and valuation that you can compare with your own expectations.
Eastern Bankshares' narrative projects US$1.4b revenue and US$507.2 million earnings by 2029. This implies 9.1% yearly revenue growth and an earnings increase of about US$131 million from US$376.1 million today.
Consensus estimates build in profit margins stepping up from 34.2% today to 35.5% in three years. That margin expansion assumption sits on top of the multi year shift toward commercial and industrial lending and growing wealth fees that management has been emphasizing on recent calls.
On earnings, the US$507.2 million forecast by 2029 equals earnings per share of US$2.28, based on analyst expectations for share count to grow roughly 7% a year over the next three years. That share issuance assumption matters because it spreads profit over a larger base, so headline earnings growth needs to be strong enough to offset any dilution.
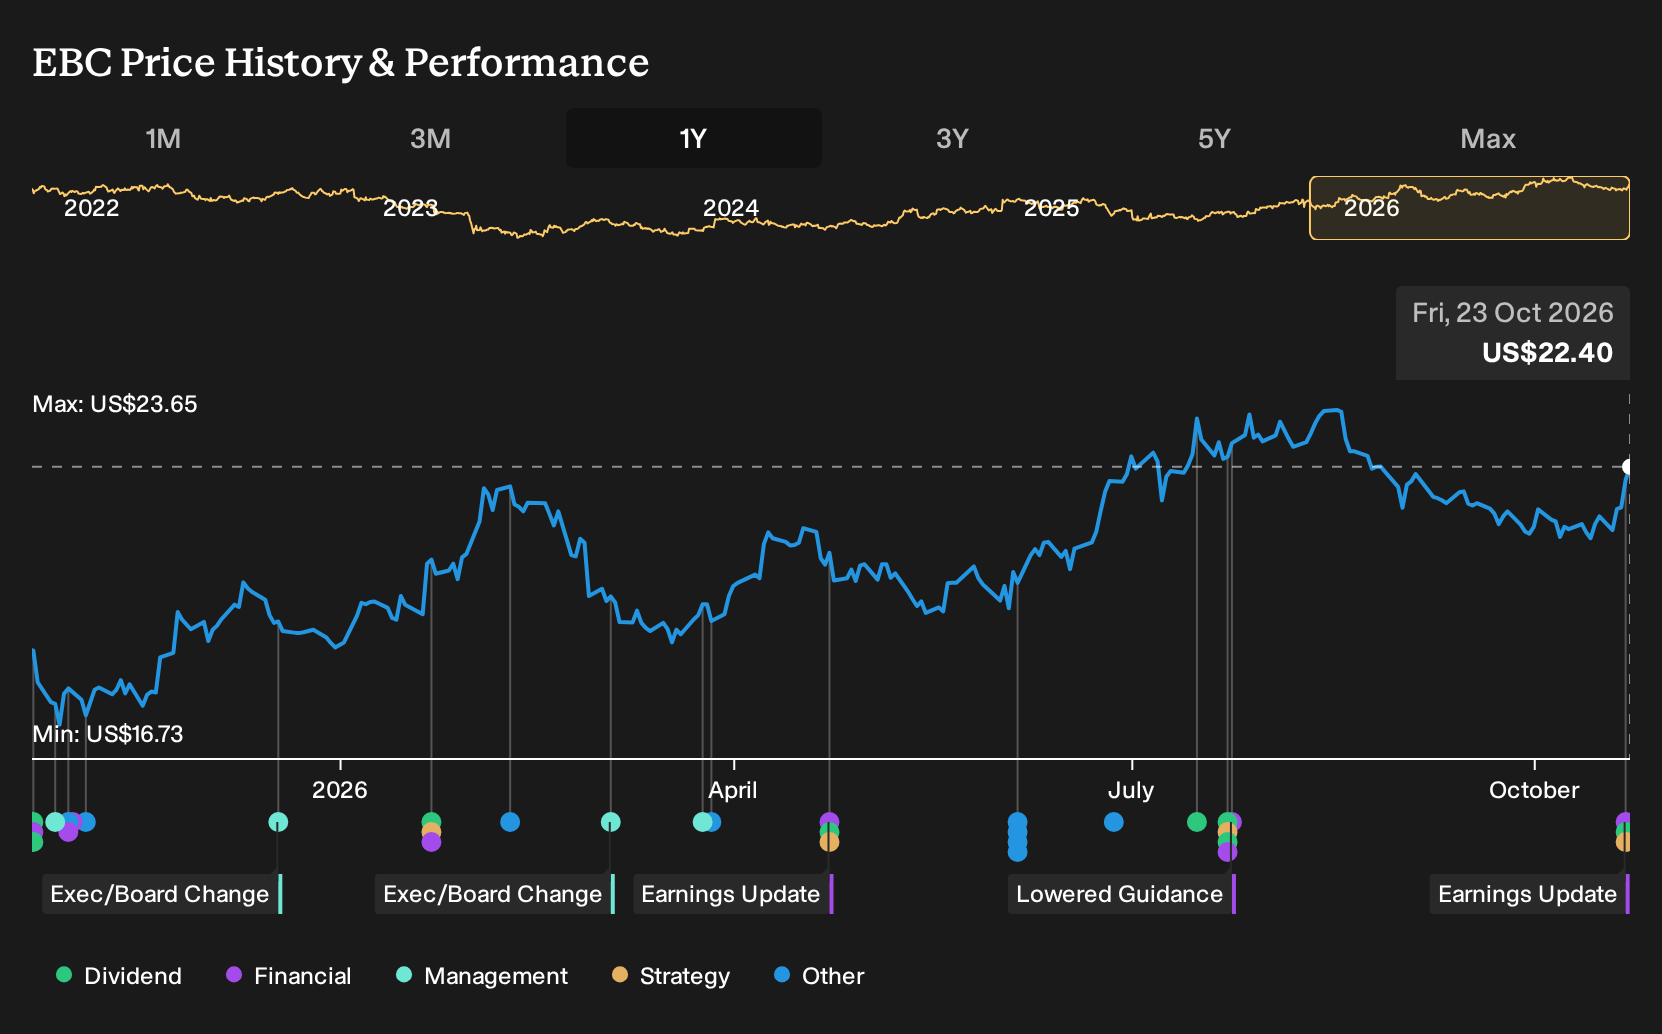
Those same models anchor the current consensus price target of US$25.12, which is about 14.6% above the recent US$21.46 share price. To line up with that view, you would need to be comfortable with Eastern Bankshares trading on a 16.3x P/E in 2029, compared with 12.5x today and an industry level quoted at 11.6x.
The implied valuation story is straightforward. If revenues do reach about US$1.4b and earnings land around US$507.2 million, then a higher earnings multiple would be doing part of the work in that target, not just profit growth alone.
Analysts fold these projections back to today using a discount rate of about 7.2% to 7.24%. That rate tries to reflect both the risk profile of a New England focused regional bank and broader funding and credit conditions mentioned in recent commentary.
Uncover why Eastern Bankshares' fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between US$25.13 and US$36.81, leaving plenty of room for disagreement on what Eastern Bankshares is worth. When these are set against rising deposit competition and merger driven scale benefits, it becomes clear why opinions can diverge. Explore multiple angles before anchoring your own stance.
Explore 2 other Eastern Bankshares fair value estimates, including one that suggests as much as 64% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eastern Bankshares research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eastern Bankshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eastern Bankshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Eastern Bankshares?
If Eastern Bankshares has sharpened your sense of what you want from a financial stock, use that checklist to scan the wider market. The Simply Wall St Screener can help you quickly narrow thousands of options down to a focused short list that better matches your risk tolerance, income needs, and return goals.
- If you want high quality companies that the market may be pricing cautiously, start by reviewing 29 high quality undervalued stocks that pair solid fundamentals with potentially attractive entry points.
- For readers who care most about income stability, consider stocks in the 5 dividend fortresses that combine 5%+ yields with a focus on resilience.
- If capital preservation and balance sheet strength sit at the top of your checklist, filter your universe with the 30 resilient stocks with low risk scores to see businesses scoring well on financial robustness.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com