


EN
Did Quarterly Earnings Slip Just Shift Handelsbanken Stock's Investment Narrative?
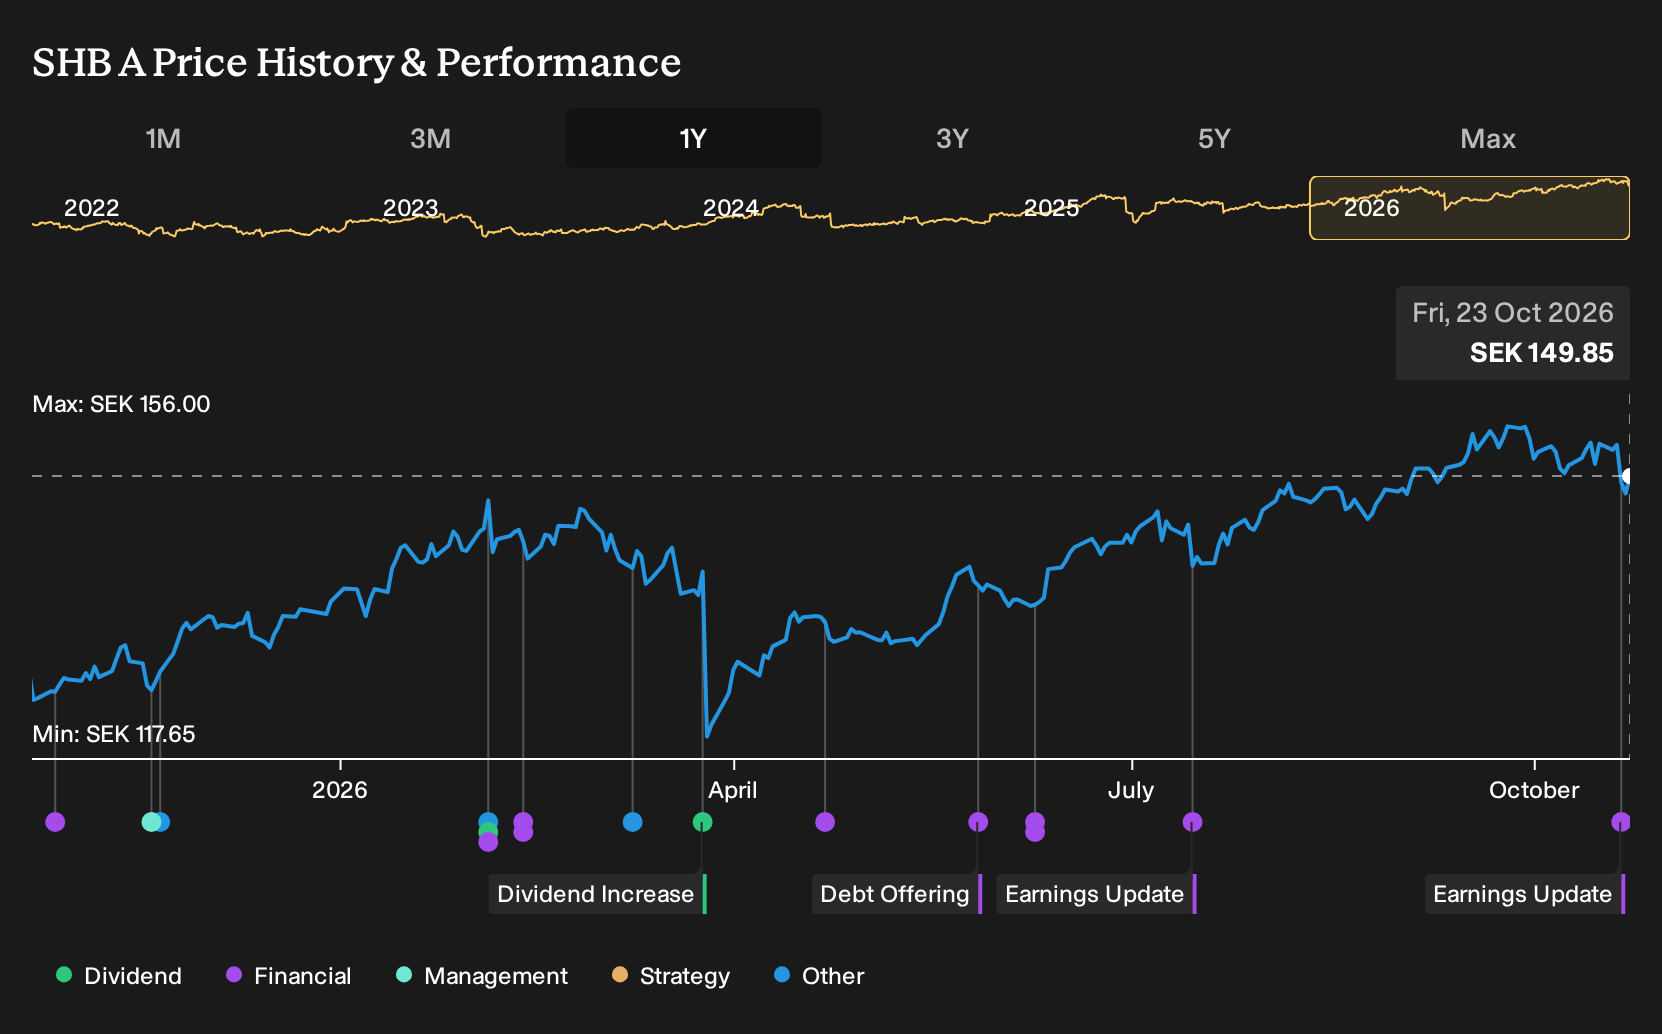
- Svenska Handelsbanken reported third quarter 2026 results with net interest income of SEK 10,053 million and net income of SEK 5,751 million, both slightly lower than the same period a year earlier, and basic earnings per share from continuing operations of SEK 2.87.
- The nine month figures showed net interest income of SEK 30,079 million and net income of SEK 17,336 million, indicating earnings pressure that aligns with earlier concerns about margin compression and the bank’s reliance on interest driven income.
- We will now examine how Svenska Handelsbanken’s investment narrative holds up against slightly lower net interest income in the latest quarterly update.
Svenska Handelsbanken Investment Narrative Recap
To own Svenska Handelsbanken, you need to be comfortable with a story built on solid credit quality, cost control and a gradual shift toward savings and fee income, rather than heavy loan expansion. The latest quarter shows slightly lower net interest income and earnings, which keeps the near term spotlight on margin pressure as the key swing factor.
In the short run, the main potential catalyst is whether fee and commission lines from the savings and mutual fund businesses can hold close to recent levels while costs stay tight. The biggest risk is that net interest income keeps softening for several more quarters, which would make that offset much harder to achieve. The current update does not fundamentally change that risk reward balance.
The latest earnings release for the third quarter and first nine months of 2026 matters because it directly tests this thesis. Net interest income and net income for both periods are slightly below the prior year, which lines up with earlier concerns about margin compression and the impact of earlier rate cuts on a bank that leans heavily on interest driven income.
For you as a shareholder or potential shareholder, this update gives fresh data on whether Svenska Handelsbanken is managing that pressure through its other levers, such as the capital light savings franchise and cost discipline. It also intersects with the dividend and funding questions, since very high payouts combined with higher funding costs could keep weighing on interest income if similar policies continue in future periods.
Svenska Handelsbanken's narrative projects SEK 61.1b revenue and SEK 24.8b earnings by 2029. This projection is based on 3.4% yearly revenue growth and an earnings increase of about SEK 1b from SEK 23.8b today.
Uncover why Svenska Handelsbanken's fair value indicates a 5% potential downside to its current price, suggesting that this premium may not be sustainable.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between SEK 142 and SEK 244 per share, so some private investors see Svenska Handelsbanken as close to their upper range while others sit far lower. Set that beside the recent earnings pressure in net interest income, and it is a reminder that opinions can split sharply. Use that spread to test your own thesis and explore alternative viewpoints before you commit fresh capital.
Explore 2 other Svenska Handelsbanken fair value estimates, including one that suggests as much as 5% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Svenska Handelsbanken research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Svenska Handelsbanken. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Svenska Handelsbanken's overall financial health at a glance.
Looking For More Investment Ideas Beyond Svenska Handelsbanken?
If this update on Svenska Handelsbanken has sharpened your views on bank earnings quality and risk, it can help to compare that thinking with companies that have different balance sheet profiles and income drivers. The Simply Wall St Screener surfaces focused lists so you can quickly spot stocks that better match your return goals and comfort with volatility.
- If capital preservation sits high on your priority list, start with a group of companies assessed for resilience using a low risk score framework through the 221 resilient stocks with low risk scores.
- For readers who care most about getting more value for every dollar paid, check out stocks that combine quality fundamentals with pricing that may look appealing using the 193 high quality undervalued stocks.
- If you prefer potential opportunities that are less widely followed, scan companies with strong underlying metrics that are not heavily on the market’s radar through the 613 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com