


EN
How Investors May Respond To Simmons First National Stock Returning To Profitability
- Simmons First National reported third quarter 2026 results with net interest income of US$203.98 million and net income of US$47.11 million, compared with net interest income of US$186.66 million and a net loss of US$562.79 million a year earlier.
- The shift from a very large loss to positive earnings, alongside higher interest income, signals a meaningful reset in Simmons First National's core banking performance and risk profile.
- We will now see how Simmons First National's investment narrative aligns with this return to profitability and higher net interest income.
Simmons First National Investment Narrative Recap
Simmons First National now looks like a cleaner earnings story, but the big picture still hinges on steady net interest income and tighter costs. To stay comfortable as a shareholder, you would need to believe the repricing of loans, efficiency moves and relationship focused lending can keep the bank on a more predictable profit footing after the swing from last year’s loss.
The main near term swing factor remains how deposit pricing and loan competition feed through to margins and fee income. The biggest risk is that intense funding competition or aggressive loan pricing erodes this newly restored profitability, leaving the recent quarter as more of a one off reset rather than a base to build from.
The third quarter 2026 earnings release is the key update here. Simmons First National reported US$203.98 million of net interest income and US$47.11 million of net income, after reporting a net loss of US$562.79 million a year earlier. For anyone tracking catalysts, that shift points directly to how the asset mix and expense actions are flowing through to the income statement.
The same filing also confirmed that no shares were repurchased between July 1 and September 30 under the existing buyback, after 662,082 shares had already been retired earlier in 2026. That choice leaves more capital available to support loan growth, absorb credit costs if needed and keep flexibility for dividends or future capital actions if conditions change.
Simmons First National's narrative projects US$1.6b revenue and US$673.4 million earnings by 2029. This would require revenue to grow at 144.2% per year and an earnings increase of about US$1,022.9 million from current earnings, compared with a US$349.5 million loss today.
Uncover why Simmons First National's fair value indicates an 11% potential upside to its current price that could narrow quickly.
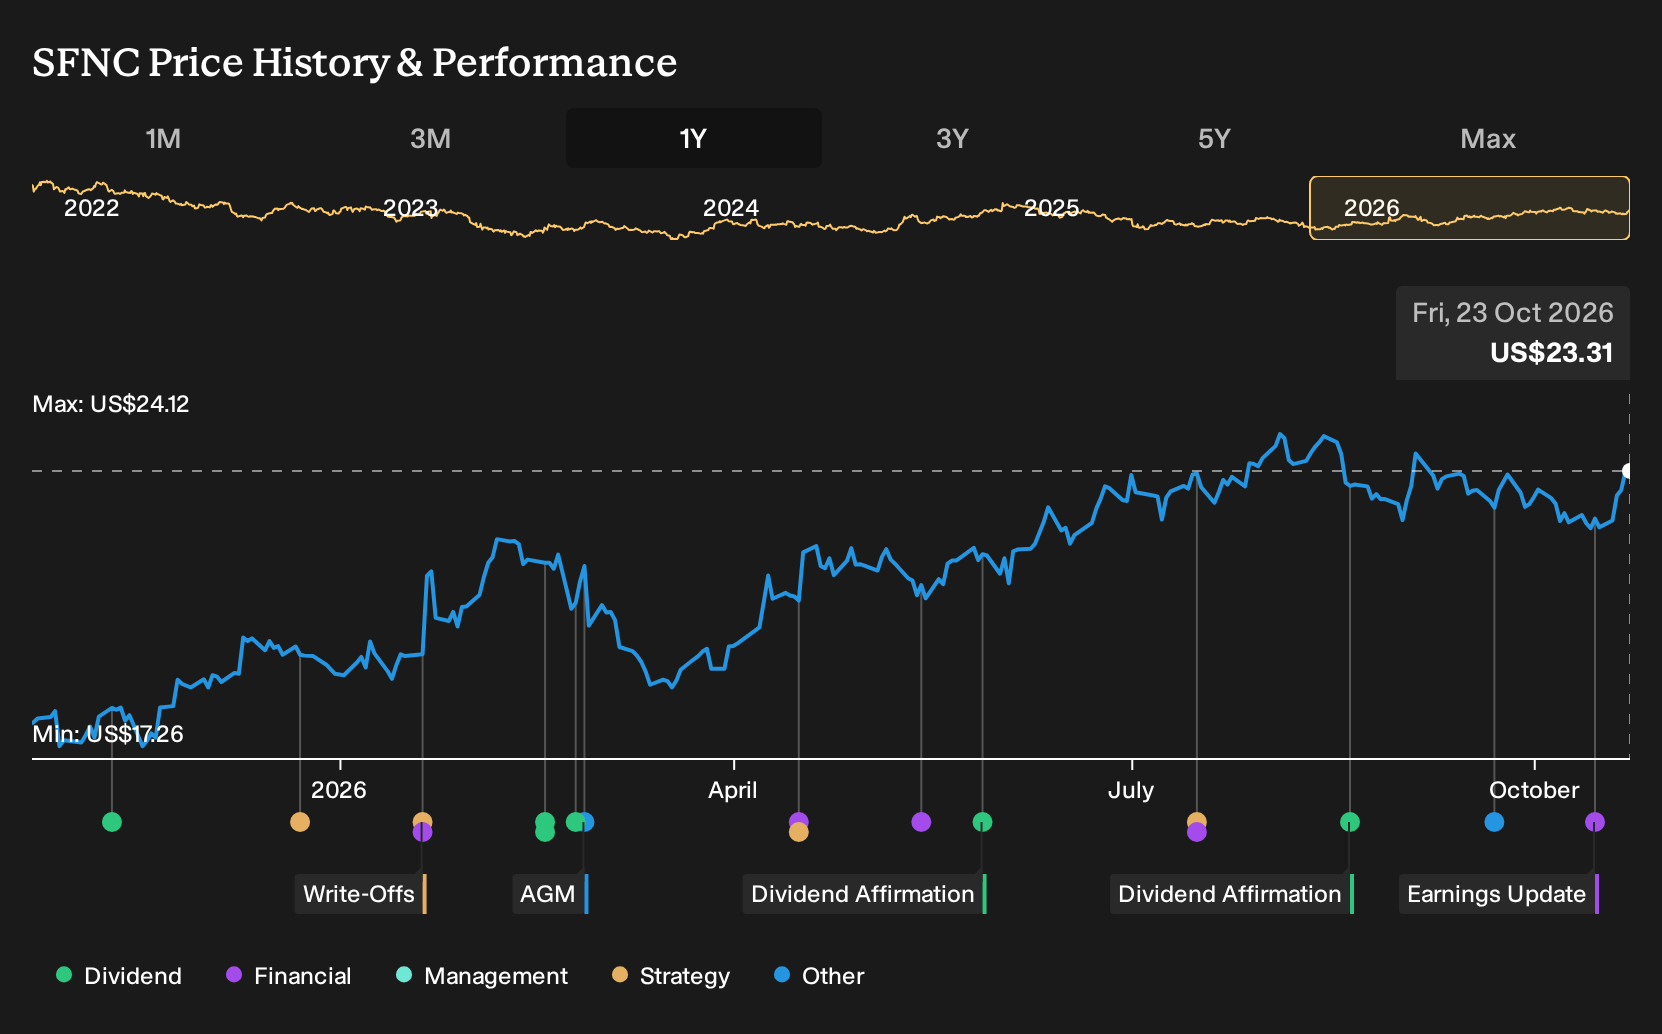
Exploring Other Perspectives
The Simply Wall St Community currently includes 2 fair value views on Simmons First National, clustered between US$25.93 and US$37.99, which already shows how far opinions can stretch. Those assessments were formed before the latest earnings and buyback pause. Revisit the thesis yourself, because community sentiment can move quickly as new information lands.
Explore another Simmons First National fair value estimate, including one that suggests it could be worth just $25.93.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Simmons First National research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Simmons First National. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Simmons First National's overall financial health at a glance.
Looking For More Investment Ideas Beyond Simmons First National?
If this Simmons First National review has sharpened your thinking, you can use that same lens across the wider market. The Simply Wall St Screener lets you quickly filter for balance sheets, earnings profiles and dividend histories that match the kind of risk and return trade off you want.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (24 results) to help you focus on companies with sturdier foundations.
- If value is your priority, you can filter for potentially mispriced opportunities by checking out a 29 high quality undervalued stocks that already meets quality and balance sheet checks.
- Income focused investors can examine payout strength by reviewing a 5 dividend fortresses that screens for higher yield profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com