


EN
Hilltop Holdings (HTH) Faces A Valuation Test Following Softer Q3 Profits
Hilltop Holdings (HTH) just paired softer Q3 2026 profits with an activist governance challenge, as Gerald J. Ford pressed the board to split the CEO and chair roles.
Recent trading reflects that tension. Hilltop Holdings' share price has eased in the short term, with a 1-month share price return of down 5.7% and a 90-day share price return of down 5.6%, even though the year-to-date share price return is up 7.3% and the 3-year total shareholder return sits at 42.2%. This suggests that investors may be reassessing near term earnings risk rather than abandoning the longer run story.
Spot similar bank stocks where governance pressure and rate sensitive earnings are already in focus by screening for a curated set of 30 resilient stocks with low risk scores.For Hilltop Holdings, the choice now is simple but uncomfortable. Investors can either lean into the pullback after softer Q3 profits and activist noise, or wait for clearer earnings from PrimeLending and the bank before deciding what the current valuation really offers.
Most Popular Narrative: 13% Undervalued
On the most followed view of Hilltop Holdings, a fair value of about $41.67 sits above the recent $36.36 close, which puts the current pullback against a thesis that already incorporates slower earnings and mortgage pressure.
The main thing that has to go right is that PlainsCapital Bank sustains its targeted 5 to 7% held for investment loan growth and stable net interest income, while PrimeLending’s cost cuts and restructuring narrow its pretax losses in a still pressured mortgage market.
See why 1 investors see Hilltop Holdings as 13% undervalued.
Result: Fair Value of $41.67 (UNDERVALUED)
Still, the Hilltop Holdings narrative could be knocked off course if mortgage losses at PrimeLending drag on longer, or if fresh credit issues force higher provisioning.
Find out about the key risks to this Hilltop Holdings narrative.
Another View: Hilltop Holdings On Earnings Multiples
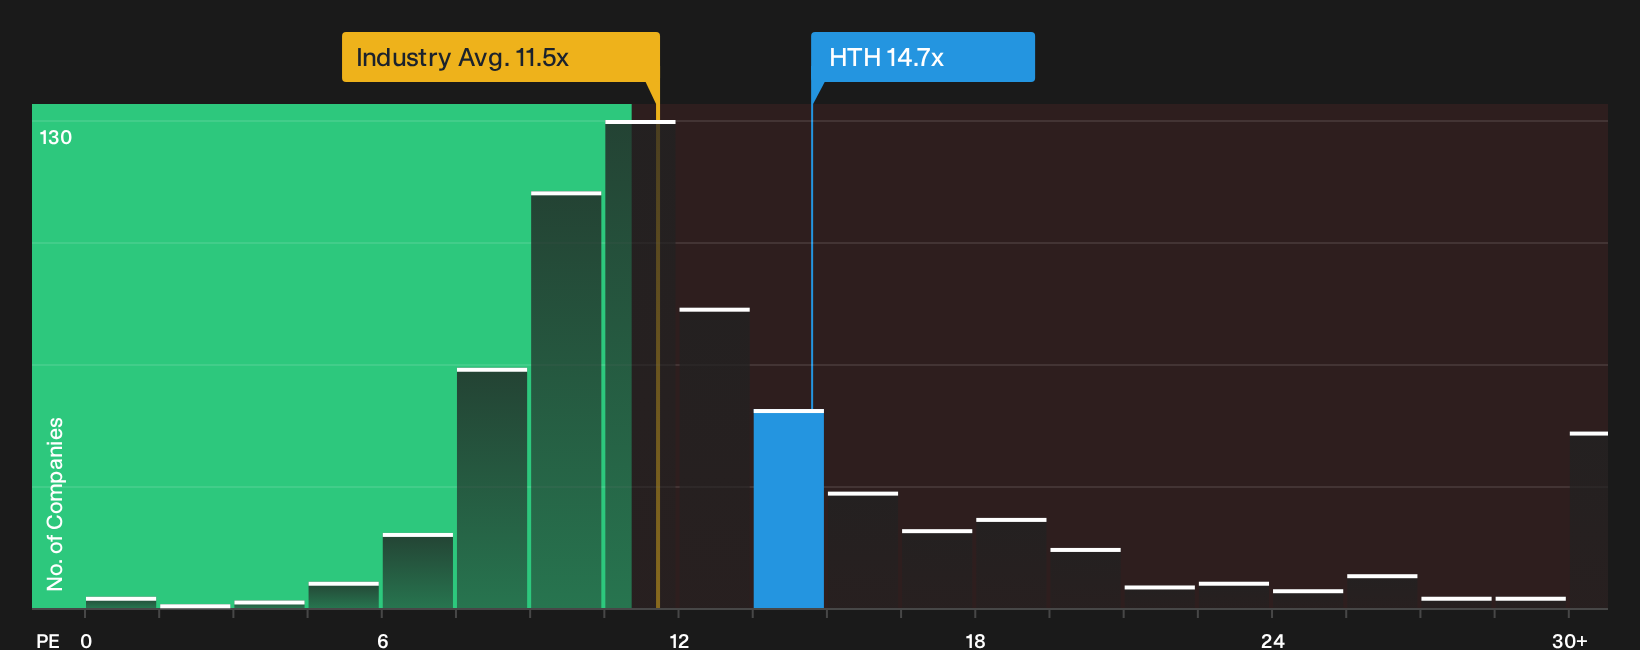
There is a catch to the 13% undervalued story for Hilltop Holdings. On current numbers the stock trades on a P/E of 14.7x, which screens higher than the US Banks industry at 11.5x, the peer group at 11.6x, and a fair ratio of 9.7x that the market could move toward.
In practice that means investors are paying a richer earnings tag than both the sector and the modelled fair ratio. Anyone buying into the pullback needs to decide whether the extra multiple is compensation for quality or a source of valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Hilltop Holdings so far. Act while opinions are split, and pressure test the potential upside and downside using our breakdown of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Hilltop Holdings?
If Hilltop Holdings has sharpened your focus on valuation and risk, do not stop here. Broader idea hunting can help you build a more resilient portfolio.
- Target potential mispricing by scanning a curated set of 29 high quality undervalued stocks that combine solid fundamentals with market skepticism.
- Strengthen your income stream by reviewing a focused group of 5 dividend fortresses that aim to pair yield with staying power.
- Protect your downside by zeroing in on a list of solid balance sheet and fundamentals (24 results) that can better handle earnings bumps and rate swings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com