


EN
L'Air Liquide (ENXTPA:AI) Expands In Vietnam And New Projects Build, Is It Fully Priced?
L'Air Liquide: Why Fresh Projects Matter Now
L'Air Liquide (ENXTPA:AI) is back in focus after a cooperation deal with Vietnam's Vinachem and fresh spending on semiconductor gases and biomethanol projects, spotlighting its long-term decarbonisation and industrial growth agenda.
Recent news around L'Air Liquide’s Vinachem partnership and new capex plans lands on top of a strong backdrop, with a 1-month share price return of 4.29% and a year-to-date share price gain of 20.85%. The 5-year total shareholder return of 76.84% points to momentum built over several years.
Scan 222 resilient stocks with low risk scores that reflect L'Air Liquide’s focus on long-term industrial projects and decarbonisation, allowing you to compare this story with other lower-volatility opportunities in one place.
After that strong run and fresh project pipeline, the central question for L'Air Liquide is straightforward: does the current price still leave enough potential upside in the risk‑reward balance for new money?
Preferred P/E of 31.4x: Is it justified?
L'Air Liquide currently trades on a P/E of 31.4x, which is well above several benchmarks even though the SWS DCF model points to a fair value of €181.65 versus the recent €174.68 share price.
The P/E ratio compares the share price with earnings per share and shows how much investors are paying today for each euro of profit. For a mature gases and engineering group with global reach, a higher P/E can signal that the market is comfortable paying up for earnings quality, balance of industrial and healthcare exposure, and a long operating history.
For L'Air Liquide, the data suggests that optimism comes at a clear premium. The stock is described as expensive on a P/E of 31.4x versus a fair P/E estimate of 24.3x. This is a level the market could eventually move towards. It is also labelled expensive relative to the European chemicals sector on 16.7x and against a peer average of 18.9x. Buyers today are therefore accepting a materially richer valuation than both the sector and peer group.
Explore the SWS fair ratio for L'Air Liquide.
Result: Price-to-earnings of 31.4x (OVERVALUED)
Still, L'Air Liquide’s premium P/E looks exposed if large project returns lag expectations or if industrial and healthcare end markets weaken from current conditions.
Find out about the key risks to this L'Air Liquide narrative.
Another View: What The SWS DCF Model Says
The SWS DCF model paints a softer picture than the rich 31.4x P/E. On this approach, L'Air Liquide looks modestly undervalued, with a fair value of €181.65 against the current €174.68 share price, which implies a 3.8% discount rather than a premium story.
That kind of gap is not huge. Yet it suggests the P/E premium might be less about froth and more about the market leaning toward the cash flow outlook. The open question for you is simple: Which signal carries more weight, the earnings multiple or the cash flow model?
Look into how the SWS DCF model arrives at its fair value.
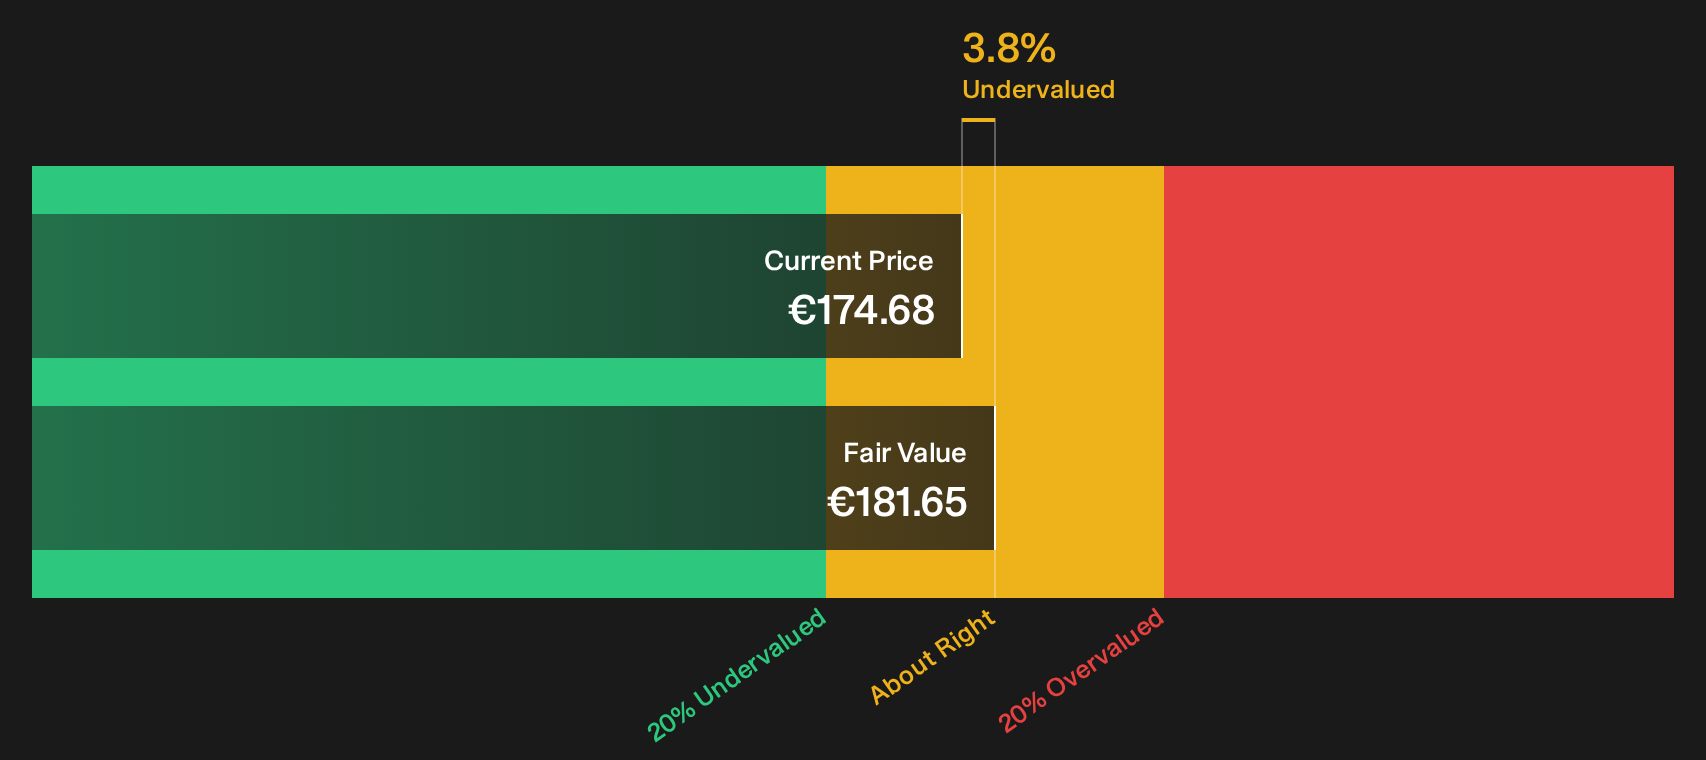
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out L'Air Liquide for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on L'Air Liquide leave you torn, that is the point. This story includes both concerns and bright spots. Consider acting while the data is fresh and weigh both sides using our breakdown of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond L'Air Liquide?
Do not stop with L'Air Liquide when the broader market might hold a better fit for your goals and risk comfort.
- Target resilient balance sheets and steadier cash profiles by scanning our list of solid balance sheet and fundamentals (205 results) for companies that may better match your downside tolerance.
- Hunt for potential mispricing by reviewing the 195 high quality undervalued stocks and compare businesses where quality and current pricing look more aligned with your return expectations.
- Stack potential income ideas by scanning the 225 dividend fortresses so you are not relying on just one stock for future cash payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com