


EN
Texas Instruments (TXN) Following Strong Earnings And AI Push Looks Undervalued
Why the latest quarter matters for Texas Instruments
Texas Instruments (TXN) just paired a strong third quarter with fresh fourth quarter guidance, giving investors new numbers to work with on both recent performance and near term expectations.
The company reported US$6.06b in third quarter sales and net income of US$2.43b, and projected fourth quarter revenue between US$5.80b and US$6.30b with earnings per share in a US$2.45 to US$2.79 range.
Texas Instruments shares have been grinding higher, with a 60.37% year to date share price return and a 72.69% total shareholder return over the past year. This suggests momentum has been building as upbeat quarterly results and new AI data center products reset expectations around both growth potential and risk.
Scan beyond Texas Instruments and see which AI infrastructure players are already on the move with our hand picked 55 AI infrastructure stocks as this earnings story unfolds.
After a 60% year to date run and fresh enthusiasm around Texas Instruments' AI data center push, the key issue now is simple. Is most of the upside already priced in, or is this just the first leg of the move?
Most Popular Narrative: 35% Undervalued
Texas Instruments last closed at $284.69, while the most followed narrative on Simply Wall St assigns a fair value of $435.69 using an 9.0% discount rate. This frames the recent rally as still leaving a sizeable valuation gap.
Texas Instruments is in the midst of a multiyear capacity-expansion cycle that is temporarily suppressing free cash flow but materially enhancing the company’s long-term competitive position. The buildout of U.S.-based 300mm analog manufacturing is expected to structurally improve cost efficiency, support higher gross margins, and increase supply-chain resilience. As these assets ramp and utilization normalizes, TXN should regain its historical free-cash-flow profile, supported by diversified end-market exposure across industrial, automotive, aerospace/defense, and energy infrastructure.
See why 20 investors see Texas Instruments as 35% undervalued.
Result: Fair Value of $435.69 (UNDERVALUED)
Still, the Texas Instruments story could be knocked off course if the multiyear fab build drags on cash generation longer than expected or if AI hardware spending cools materially.
Find out about the key risks to this Texas Instruments narrative.
Another take on Texas Instruments’ valuation
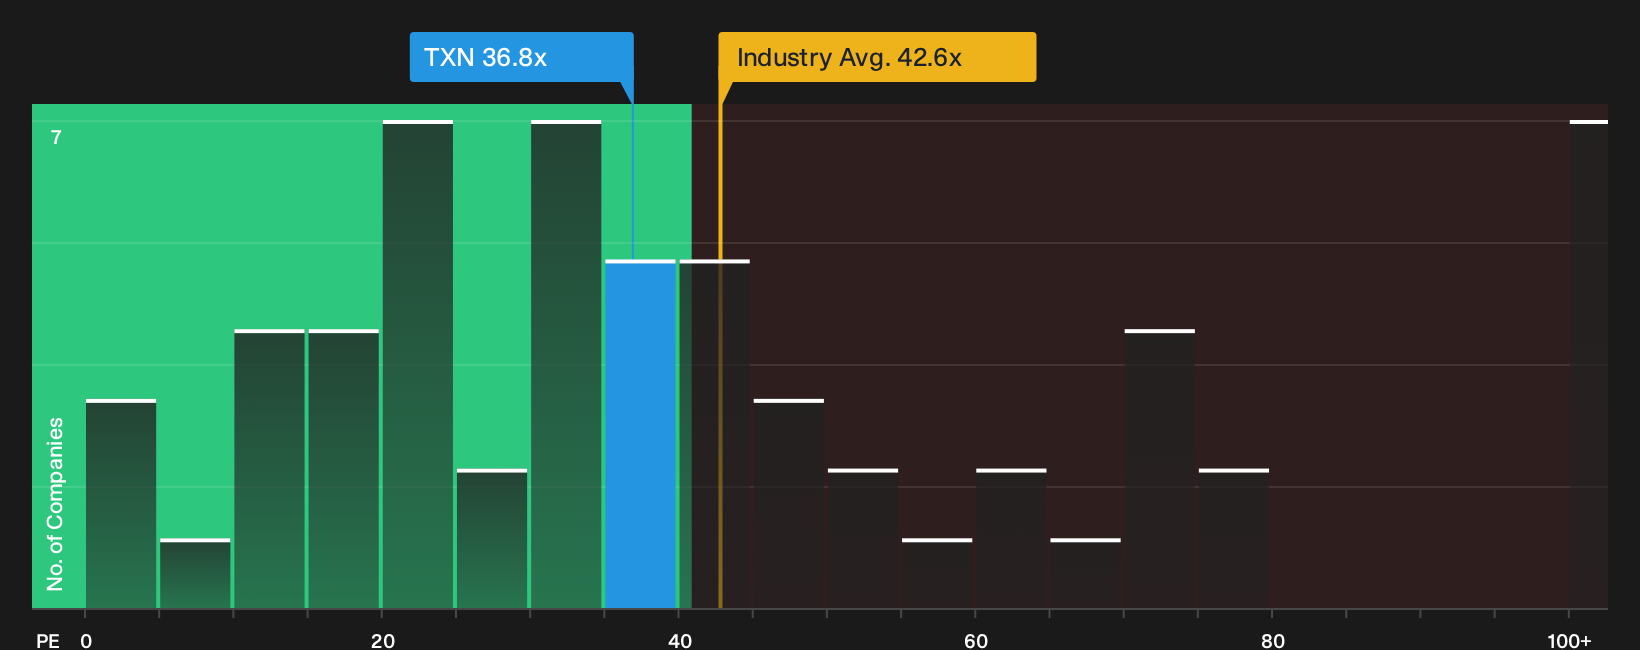
The DCF story is one thing, but the market’s own P/E signals tell a different side of Texas Instruments. The stock trades on 36.8x earnings compared with a 42.6x average for the US Semiconductor group and 40.5x for peers, yet its fair ratio is flagged at 34.5x.
That gap cuts both ways. A lower P/E than the sector hints at some cushion if enthusiasm cools, while a premium to the 34.5x fair ratio points to less room for error if growth or margins fall short. Which crowd is closer to being right, the market today or the fair ratio model?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Texas Instruments for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and risk around Texas Instruments feels finely balanced, act quickly to review the details, compare the trade offs, and weigh both sides of the story with 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Texas Instruments?
Texas Instruments may be front of mind today, but keeping your edge means constantly refreshing your watchlist with fresh, high quality ideas from other corners of the market.
- Target resilient compounding potential by scanning companies that combine durable earnings power with a 30 resilient stocks with low risk scores.
- Hunt for mispriced quality by reviewing a curated 29 high quality undervalued stocks that pairs healthy balance sheets with attractive valuations.
- Get in early on future leaders by checking a 21 high quality undiscovered gems before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com