


EN
Is Verastem (VSTM) A Bargain On Fresh VS 7375 Data And FDA Trial Alignment?
Verastem (VSTM) has become a focus for investors after fresh TARGET-D 101 data on its KRAS G12D inhibitor VS-7375, along with FDA alignment on a first-line pancreatic cancer Phase 3 trial design.
That clinical update has arrived alongside a sharp move in Verastem’s share price, with a 7-day share price return of 16.1%, a 30-day gain of 29.7% and a 90-day jump of 65.1%. The 1-year total shareholder return of 26.3% sits against a much weaker 5-year total shareholder return of 67.8%, which reflects how recent momentum is rebuilding after a difficult longer period for holders.
Scan other oncology-focused opportunities moving on clinical catalysts with our hand-picked 34 healthcare AI stocks that blend advanced therapeutics and data-driven medicine.
Verastem now trades at a sizeable discount to both analyst targets and estimated fair value after its latest surge. Is that a genuine mispricing, or a market warning label on clinical, funding and execution risk?
Most Popular Narrative: 41.7% Undervalued
The prevailing narrative values Verastem at $17.22 per share, well above the last close at $10.04. This sets a clear tension between modeled upside and current pricing.
The combination of an active commercial franchise and a RAS or MAPK focused pipeline, underpinned by a cash position of US$137.7 million and a stated runway into the second half of 2026, gives Verastem room to fund launch activities and clinical development, which directly touches future earnings and the potential to narrow current net losses.
See why 4 investors see Verastem as 42% undervalued.
The most followed narrative framework applies a 7.57% discount rate and arrives at fair value of $17.22, compared with the $10.04 trading level. That gap, combined with the modeled path to $312.2 million in revenue and $50.1 million in earnings by 2029, underpins the view that the stock trades at a steep discount while still recognizing Verastem is loss making today and not forecast to reach profitability within the next 3 years.
Result: Fair Value of $17.22 (UNDERVALUED)
Still, Verastem’s current annual loss of US$202.7 million and a cash runway projected only into the second half of 2026 leave little room for execution missteps.
Find out about the key risks to this Verastem narrative.
Another View On Verastem’s Valuation
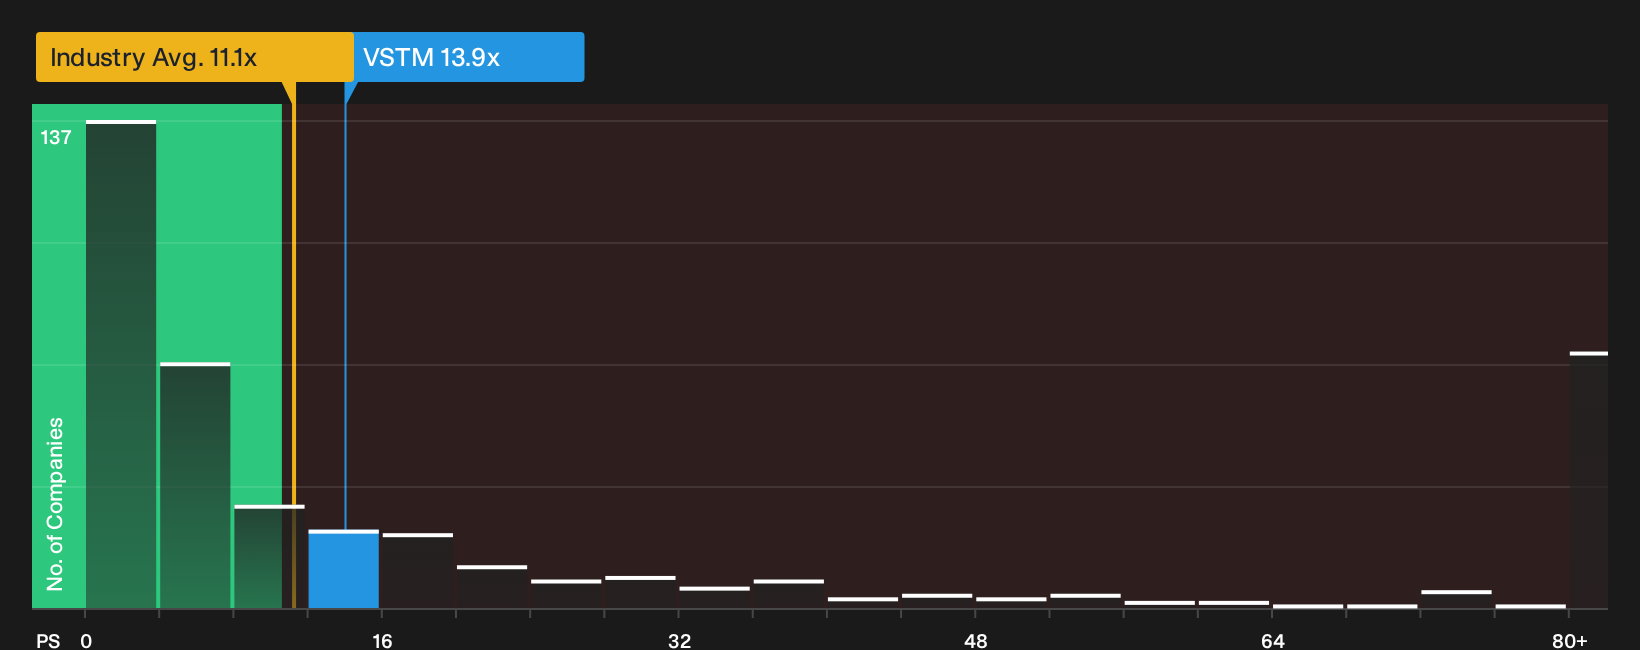
The earlier fair value work leaned on long term earnings forecasts and analyst targets. A much simpler lens, the current P/S of 13.9x, tells a different story. Verastem trades richer than the US Biotechs industry at 11.1x, its peer set at 12.3x, and even its own fair ratio of 12.6x. That premium suggests investors are already paying up for growth, so the remaining safety margin may be limited.
To see how those P/S gaps stack up against the underlying business assumptions, and where the ratio could reasonably move over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Verastem’s valuation and risk profile make this a stock where you need to look under the hood yourself and move promptly if you decide it fits your approach. To weigh both the concern and the upside in one place, start with the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Verastem?
If Verastem has your attention, do not stop there. Broaden your watchlist with focused, data-backed ideas that could help inform your next move.
- Target stronger balance sheets by scanning the list of solid balance sheet and fundamentals (24 results) that highlight companies with financial cushions designed to handle shocks.
- Look for potentially mispriced opportunities by reviewing the 21 high quality undiscovered gems that spotlight lesser-known businesses with solid fundamentals.
- Prioritize capital preservation by filtering for the 30 resilient stocks with low risk scores that surface stocks with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com