


EN
Progressive (PGR) Is Back In The Spotlight, What Is Catching Attention?
Progressive earnings spark fresh attention on the stock
Progressive (PGR) just posted nine month 2026 results that included revenue of US$68.989b and net income of US$8.671b, with earnings per share from continuing operations also above the prior year.
Investors have reacted positively to Progressive's update, with the share price delivering a 10.98% 30 day share price return and a 10.87% 1 year total shareholder return. The recent 4.38% 7 day share price gain suggests momentum has been building around the earnings release.
Scan beyond Progressive and see how other insurers with strong recent earnings trends stack up using our curated list of 30 resilient stocks with low risk scores.
After a strong run following Progressive's latest numbers, the real tension now sits in the price. Does the current tag still leave enough upside to justify new risk, or is most of the payoff already on the table?
Most Popular Narrative: 1% Undervalued
On the latest numbers, Progressive's narrative fair value of $231.38 sits only slightly above the last close at $228.07. The story is less about a big gap and more about what could shift the balance over time.
Progressive's scale, data analytics, and rapid pricing response mechanisms continue to support share gains in personal auto as it now holds 18.6% market share and has become the largest U.S. personal auto writer by direct premiums written, which can influence net premiums written and earnings.
See why 72 investors see Progressive as 1% undervalued.
Result: Fair Value of $231.38 (UNDERVALUED)
Still, rising claim severity, a higher consolidated combined ratio, and the June 2026 31% net income drop could quickly challenge the current Progressive narrative.
Find out about the key risks to this Progressive narrative.
Another view on Progressive's valuation
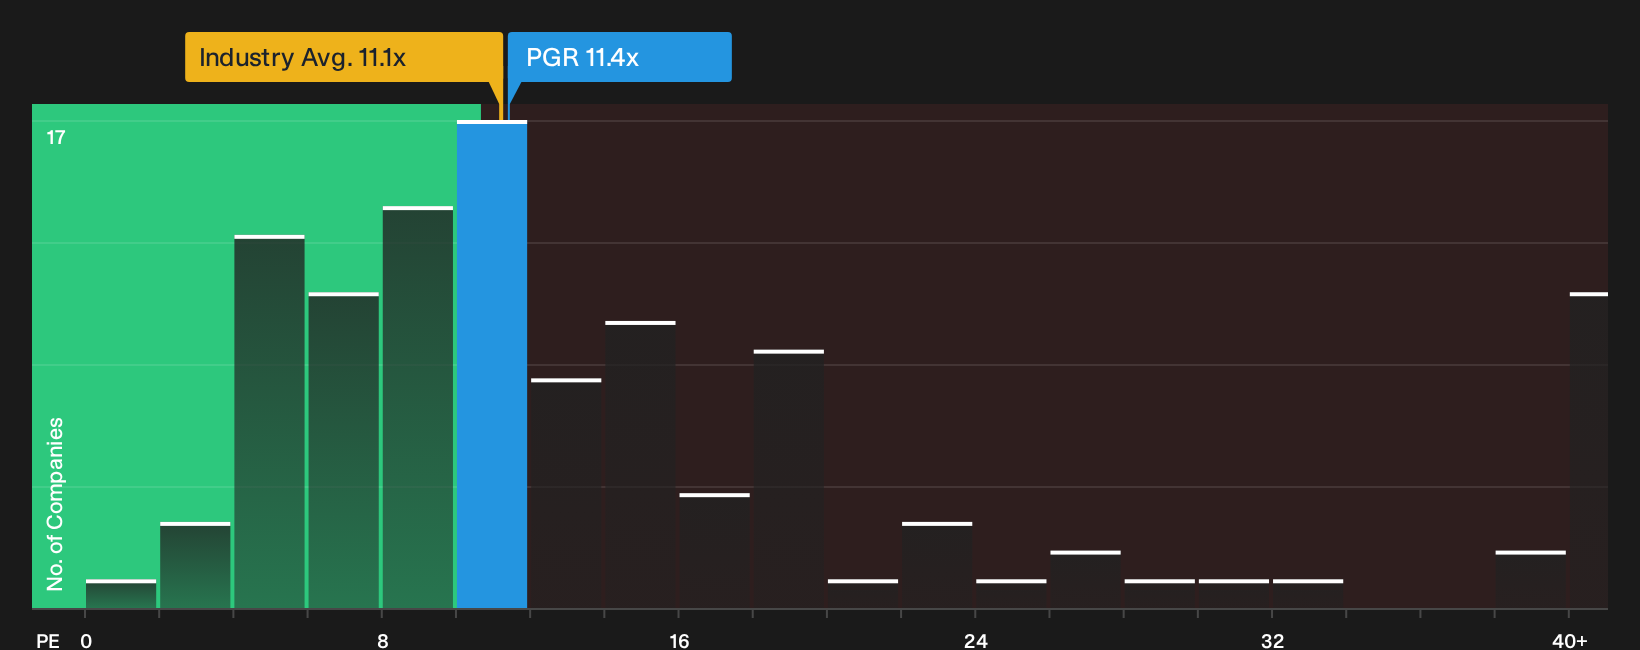
The first story paints Progressive as modestly undervalued based on fair value and analyst targets. A different lens tells a trickier story. On a P/E of 11.4x, the stock trades above both peers at 8.6x and a fair ratio of 10.7x, which points to less margin for error if earnings disappoint.
That richer earnings multiple can signal confidence in Progressive's track record, or it can simply mean you are paying up for qualities the rest of the sector does not receive. The question is whether that premium still feels comfortable once you line it up against your own expectations for future profit trends and risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Progressive's value story can be useful if you use them as a prompt rather than a verdict. If you want to move quickly and form your own view using both the risks and the potential upside highlighted by recent data, start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Progressive?
If Progressive has your attention, do not stop here. Use the same structured thinking to compare fresh ideas and avoid leaving better risk and reward trade offs on the table.
- Target resilient balance sheets and steady fundamentals with our curated list of solid balance sheet and fundamentals (24 results) tailored for investors who want financial strength front and center.
- Hunt for opportunities that combine quality with potential value gaps using the focused 29 high quality undervalued stocks so you can quickly sort through what deserves a closer look.
- Zero in on income ideas that aim to pay you while you hold by working through our hand picked 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com