


EN
Catena (OM:CATE) Expands In Finland As Investors Weigh Whether Its Value Story Still Holds
Catena (OM:CATE) has agreed to develop a 5,800 m² logistics facility in Pirkkala, Finland, which is fully leased on a seven-year contract and has an expected annual operating surplus of about SEK 9.7 million.
The new Finland project lands at a time when Catena’s share price has picked up in the very short term, with a 1-day share price return of 5.85% and a 7-day gain of 4.55%. This comes even though the year-to-date share price return is down 19% and the 1-year total shareholder return is down 23.2%, which points to improving short-term momentum after a tougher period for longer term holders.
Spot other logistics-focused plays gaining traction alongside Catena by scanning our curated list of 42 power grid technology and infrastructure stocks.For Catena, that sharp short-term rebound sits against weaker 1-year and year-to-date returns, which raises a simple question: Is the latest move pointing to improving fundamentals being recognised, or just a quick swing in sentiment before valuation takes the stage?
Most Popular Narrative: 23% Undervalued
Catena’s most followed valuation storyline points to a fair value of about SEK463.88 per share, compared with the last close at SEK358.20, which suggests the recent share price bounce still sits below that narrative anchor.
The completion of new and ongoing development projects is expected to add approximately 90,000 square meters to the portfolio, which, with a targeted yield on cost of 7%, is expected to enhance earnings and profitability. A robust balance sheet with low leverage (LTV at 37.8%) is described as positioning Catena to capitalize on growth opportunities and potentially drive higher earnings in the future.
See why 4 investors see Catena as 23% undervalued.
Result: Fair Value of SEK463.88 (UNDERVALUED)
Still, geopolitical uncertainty and regional oversupply in areas like Mälardalen and Jönköping could pressure Catena’s occupancy, margins, and ultimately challenge that 23% undervaluation case.
Find out about the key risks to this Catena narrative.
Another View: Catena Through A Cash Flow Lens
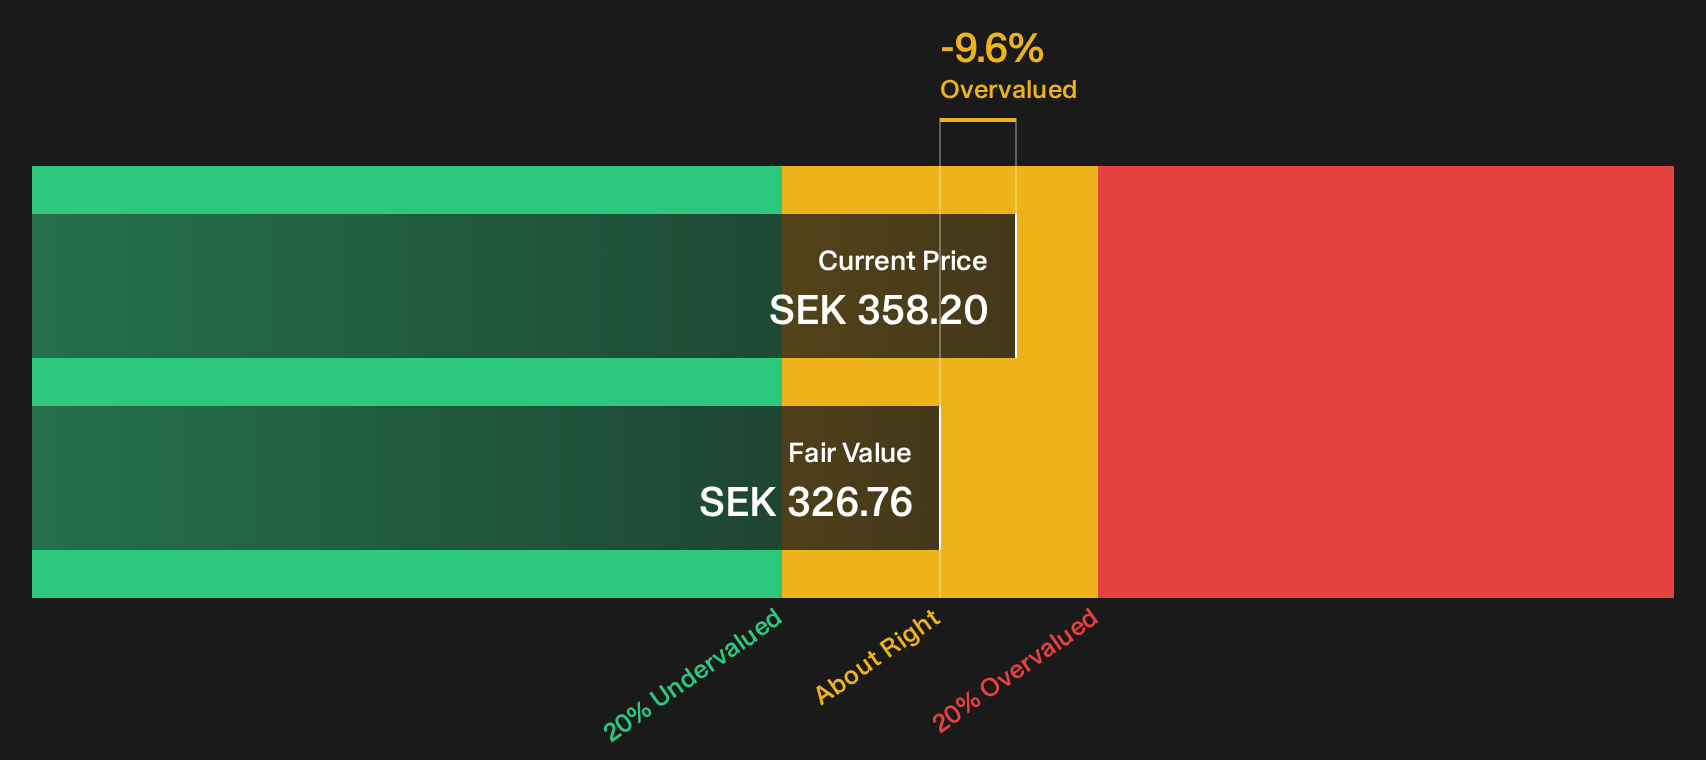
While the most followed Catena narrative leans on earnings forecasts and target prices, our DCF model, which values the business on estimated future cash flows, points to a fair value of about SEK326.76 per share, below the current SEK358.20 level. That reading suggests less upside and prompts a simple question for you: which story feels more realistic?
To unpack what sits behind that cash flow view in plain terms, take a look at how the SWS DCF model pieces together value for Catena, then compare it with the narrative assumptions you find more reasonable Look into how the SWS DCF model arrives at its fair value..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Catena for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in Catena’s story make this a moment to move fast, review the data yourself, and weigh both sides through the 5 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Catena?
If you only stop at Catena, you miss a wider field of opportunities. Put a few minutes into fresh ideas today and your future self may thank you.
- Target potential mispricings by scanning a curated set of quality candidates through the 196 high quality undervalued stocks.
- Strengthen your income stream by checking companies that aim to combine resilience with meaningful payouts using the 225 dividend fortresses.
- Reduce portfolio stress by focusing on businesses with sturdier finances through the 222 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com