


EN
3 Defensive Dividend Stocks For Steady Income When Rates Stay Higher
Central banks are keeping investors on edge, bond markets are swinging and inflation data is still dictating every move, which makes dependable dividends feel oddly rare. When cash yields look tempting, missing resilient payout stocks that can handle higher rates can be costly. This article filters the noise by using a Global Large-Cap Defensive Dividend Stocks screener and presents three stocks exposed to these macro catalysts for closer examination.
The stocks covered below are only a small sample of the Global Large-Cap Defensive Dividend Stocks idea. The full screen surfaces 14 more companies with similarly resilient profiles and income stories for you to review. If you want to move straight from reading to doing, use the Global Large-Cap Defensive Dividend Stocks screener to identify, analyze, and prioritize the dividend payers that best fit your risk and income targets.
Coca-Cola FEMSA. de (KOF)
Coca-Cola FEMSA is included in this defensive dividend screen because its large-cap Latin American beverage footprint and established payout track record align with the quest for resilient income as rates and inflation keep shifting.
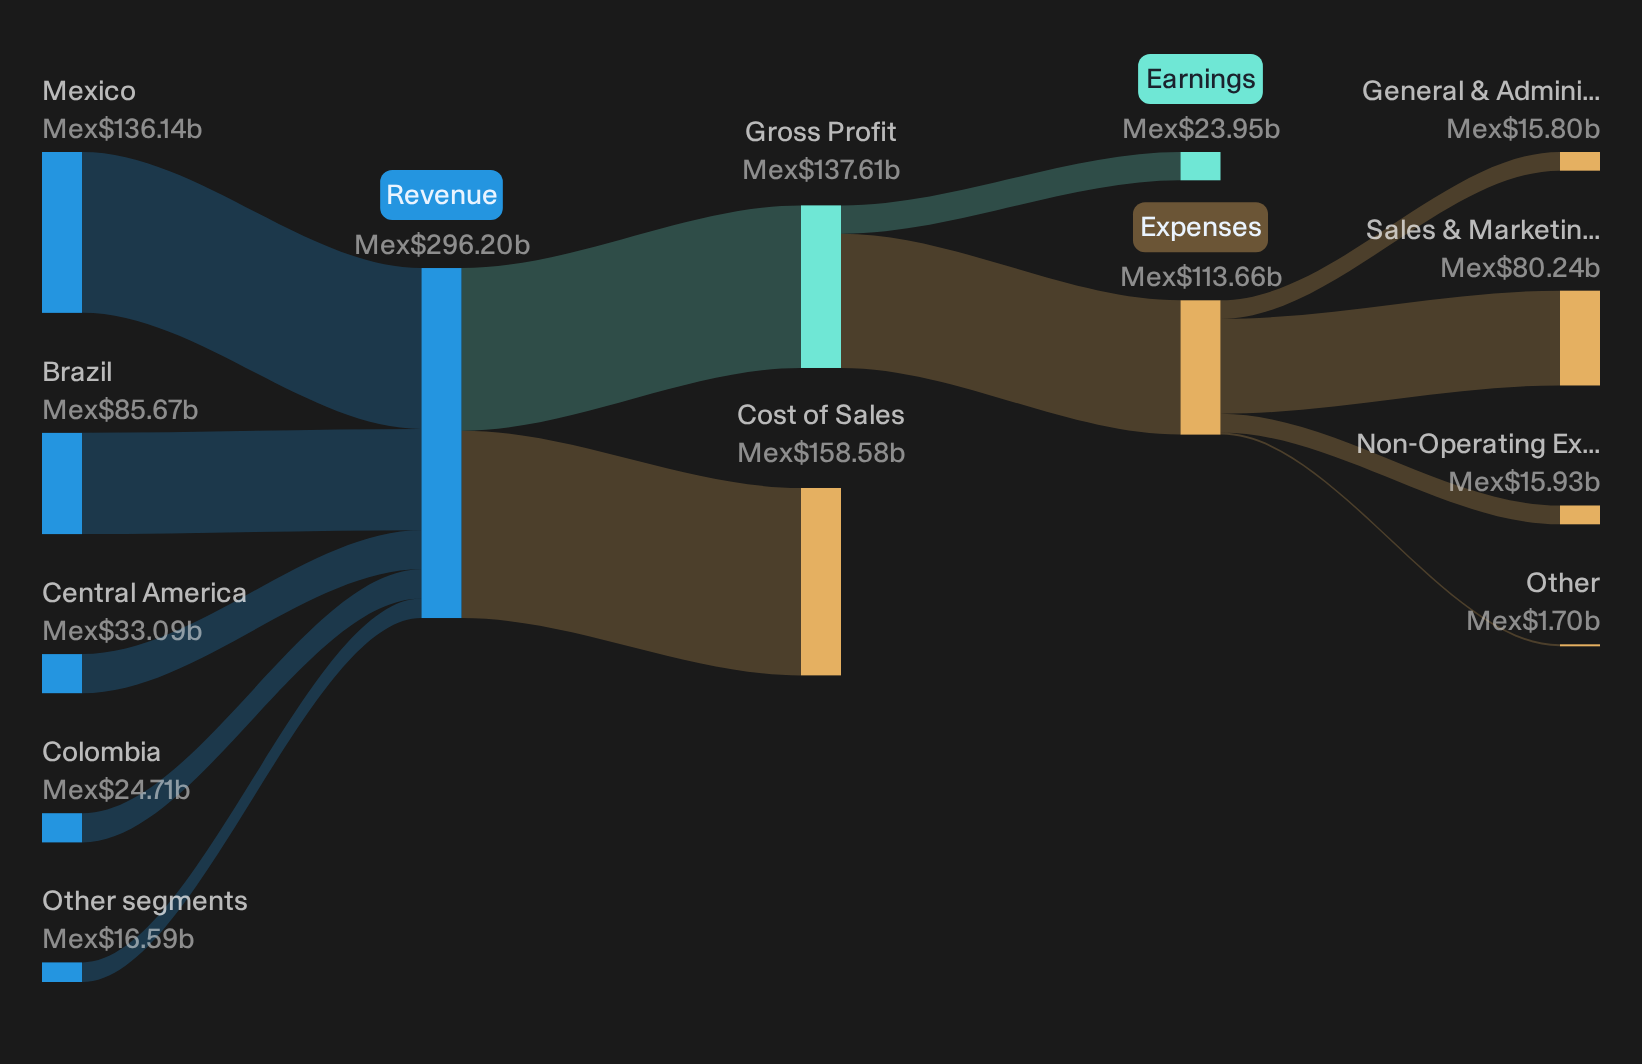
Coca-Cola FEMSA is the largest Coca-Cola bottler in Latin America, producing and distributing a wide range of non-alcoholic drinks that generated about MX$296.2b from beverages, with a market cap near US$24.8b, which helps anchor its role in this dividend-focused screen.
"Further rollout of Coca-Cola FEMSA’s Juntos+ digital ordering and Juntos+ Advisor tools into additional territories beyond Mexico and Brazil could extend the uplift in purchase frequency, average ticket and cooler coverage already seen in these markets."
What happens to margins and cash generation if one quietly building shift in how customers order and what they buy accelerates from here?
That ordering shift is exactly what sits underneath the full narrative for Coca-Cola FEMSA. de. In that context, you can see how Coca-Cola FEMSA’s digital push could reshape pricing power and cash generation.
Medtronic (MDT)
Medtronic is a healthcare heavyweight that fits this defensive dividend screen because device-based treatments for chronic diseases tend to produce steady demand and cash flows. This is exactly the sort of profile income-focused investors look for when rates and inflation keep moving around.
Medtronic plc develops device-based therapies across cardiovascular, neuroscience, and medical surgical portfolios, generating about $14.6b from Cardiovascular, $10.5b from Neuroscience, $9.0b from Medical Surgical and $3.4b from Other, with a market value near $116.8b.
"The rapid global growth in chronic diseases such as cardiovascular disease and diabetes is still supporting demand for Medtronic therapies. This is now reinforced by strong momentum in Cardiac Ablation Solutions, renal denervation through Symplicity and newer pelvic health options like Altaviva, which together have the potential to lift organic revenue growth and earnings over time."
The real tension for Medtronic is whether one subtle shift in how its higher value procedures scale ultimately tilts margins or dividends more than investors expect.
When that shift in higher value procedures really kicks in, the full narrative for Medtronic outlines how Medtronic’s demand, pricing power and dividend story could decouple from expectations.

Archer-Daniels-Midland (ADM)
Archer-Daniels-Midland fits this defensive dividend screen because essential food and nutrition ingredients tend to keep cash coming in even when rates stay high and inflation is choppy, which makes its mix of biofuels, crush and Nutrition particularly relevant right now.
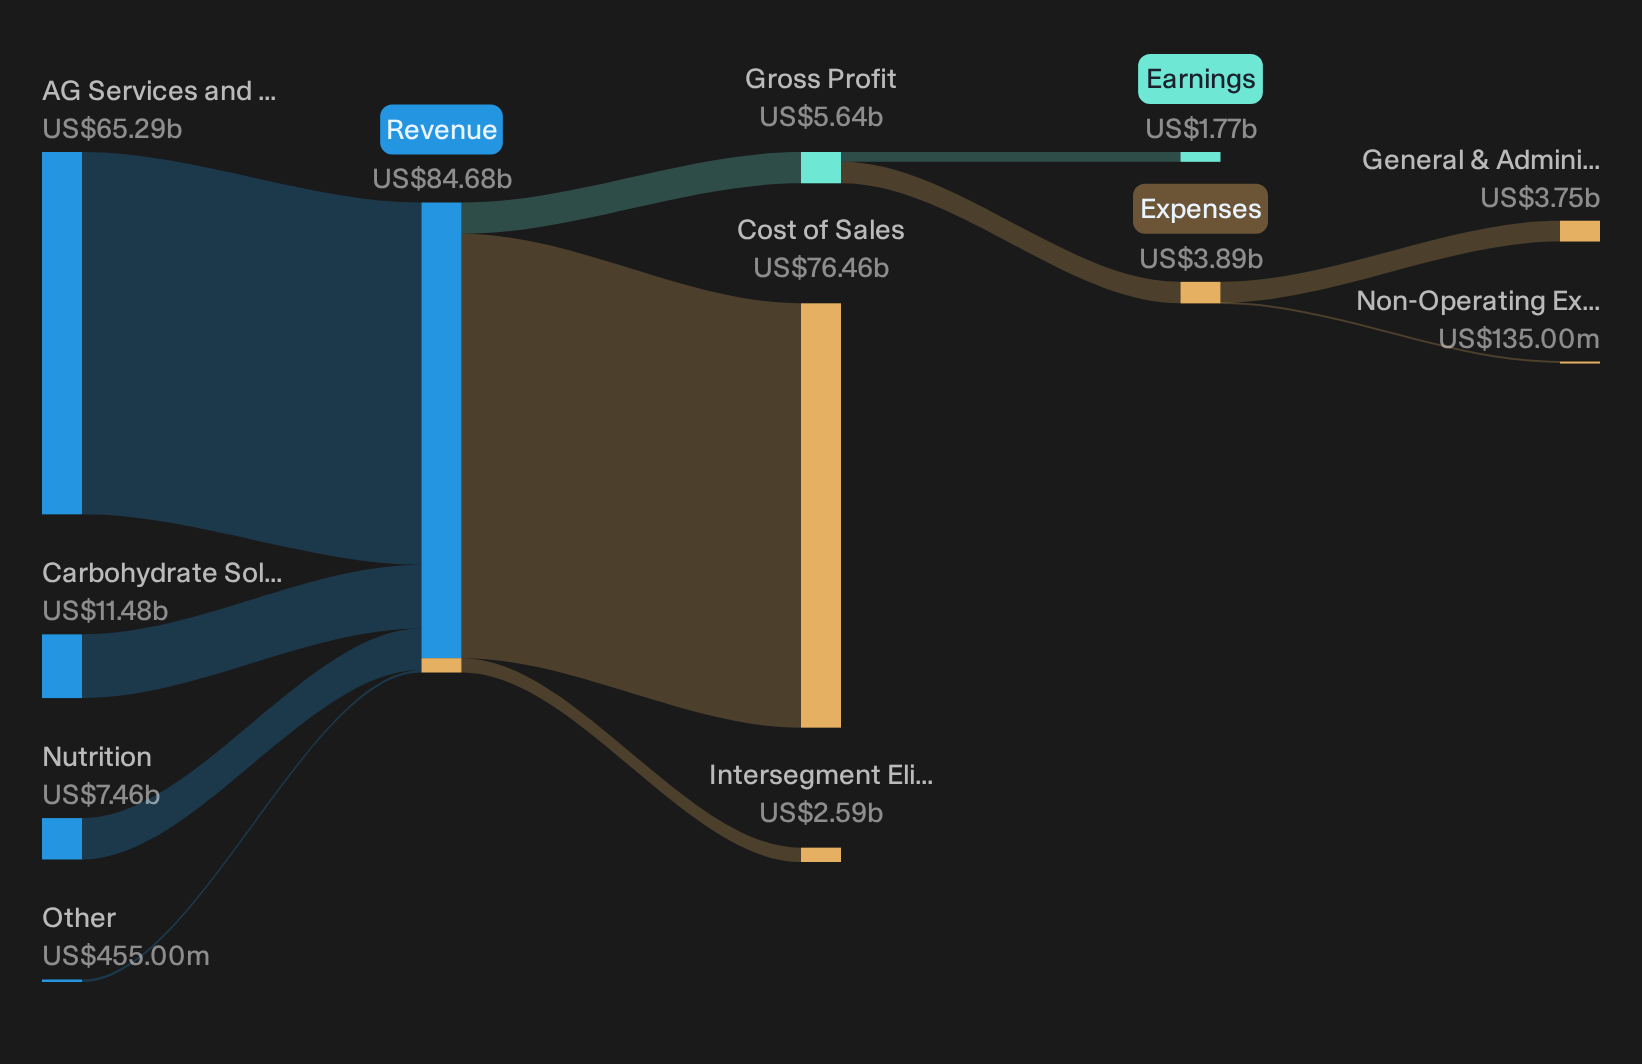
ADM processes agricultural raw materials into human and animal nutrition products, with most revenue from Ag Services and Oilseeds at about $65.3b, followed by Carbohydrate Solutions at roughly $11.5b and Nutrition at about $7.5b, and the group is valued near $38.6b.
"Policy clarity and government support for biofuels, including the 45Z production tax credit that Archer-Daniels-Midland now expects to contribute about US$250 million in 2026, together with favorable blending mandates and domestic feedstock incentives, are expected to support crush economics and feed into revenue and earnings."
What really matters now is how one shift in where ADM earns each marginal dollar affects the balance between steady income and future growth.
That balance is exactly what the full narrative for Archer-Daniels-Midland unpacks, revealing how Archer-Daniels-Midland’s cash engine, risk mix and dividend profile could be quietly accelerating.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. By the time momentum headlines hit, early entries are already flying. Scan these curated themes that are under the radar for now and consider them before participation broadens.
- Look for strong payout engines before yields are affected by higher demand with a curated mix of 5 dividend fortresses built to keep income front and center.
- Explore the infrastructure backbone of AI while valuations remain a key focus by scanning 55 AI infrastructure stocks that support chips, data centers, and high-intensity compute.
- Monitor possible rate and grid upgrades by tracking 42 power grid technology and infrastructure stocks that provide hardware, software, and services to keep electricity flowing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com