


EN
Sugi HoldingsLtd (TSE:7649) Could Be 52% Below Fair Value On September Sales Update
Sugi HoldingsLtd (TSE:7649) just reported September 2026 net sales for all stores at 105.5% of the prior year, a fresh data point that gives investors a snapshot of current trading momentum.
For context, Sugi HoldingsLtd’s share price closed at ¥1,256. The stock logged a 1 day share price return of 1.74%, yet it is still down 13.42% over 3 months and 31.46% year to date. The 3 year total shareholder return of 33.31% contrasts with a 27.17% decline over the past 12 months, which points to recent momentum fading after a stronger multi year run.
Spot fresh momentum at Sugi HoldingsLtd, then compare it with a hand picked 14 high quality undervalued stocks that also pair solid fundamentals with recent price pressure.Sugi HoldingsLtd has slid hard over the past year even as analysts see upside and one valuation model suggests a large discount to intrinsic value. Is the caution around this drugstore group excessive or entirely reasonable?
Preferred P/E of 15.9x: Is it justified?
Sugi HoldingsLtd trades on a P/E of 15.9x, which sits above both its industry peers and the level suggested by one fair value model, even though the share price is down sharply over the past year.
The P/E ratio links what investors are paying today to the earnings the retailer currently generates. For a drugstore and pharmacy operator like Sugi HoldingsLtd, that metric often reflects how the market weighs relatively steady consumer demand against execution risks and capital needs.
Here, the stock is described as good value against an estimated fair P/E of 17.3x. This implies the market is assigning a lower multiple than that model suggests could be justified. At the same time, the shares are labelled expensive versus both the peer average of 14.9x and the broader JP Consumer Retailing industry on 13.1x. This points to a richer tag than many rivals that investors may only be willing to pay if they have confidence in future earnings growth and cash flow durability.
Explore the SWS fair ratio for Sugi HoldingsLtd.
Result: Price-to-earnings of 15.9x (ABOUT RIGHT)
Still, Sugi Holdings Ltd faces pressure if recent share price weakness continues or if Japan-focused drugstore spending cools and compresses earnings expectations.
Find out about the key risks to this Sugi HoldingsLtd narrative.
Another view on Sugi HoldingsLtd: cash flows paint a different picture
P/E tells you what people pay for today’s earnings, but the SWS DCF model asks a different question. It estimates what Sugi HoldingsLtd’s future cash flows might be worth in today’s money. On that score, the shares trade at roughly half of the model’s ¥2,591.13 value, which raises a simple question: Is the current price reflecting risk, or opportunity that others are ignoring?
Look into how the SWS DCF model arrives at its fair value.
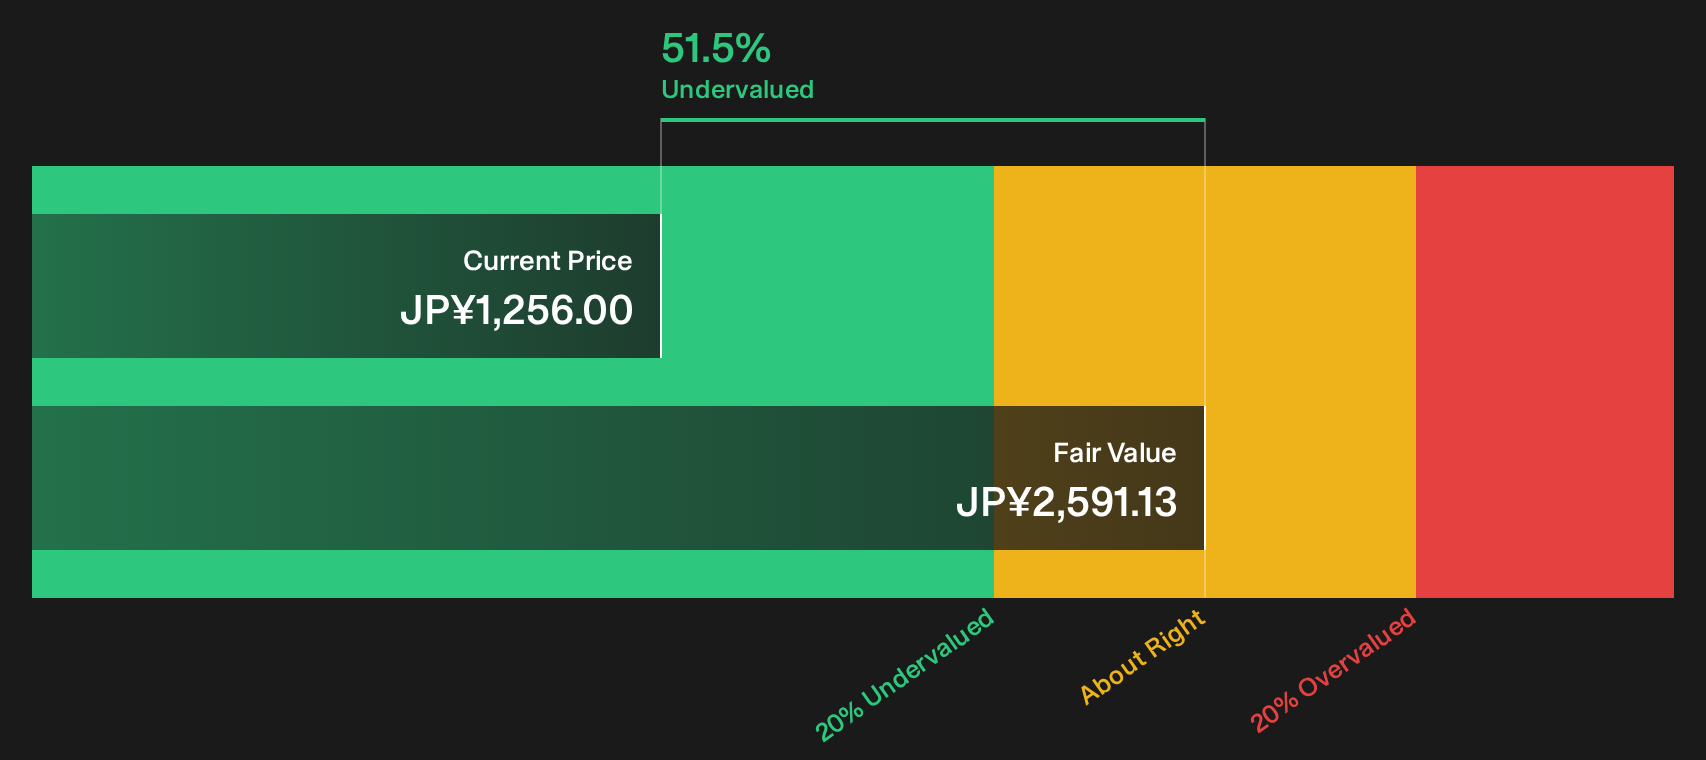
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sugi HoldingsLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Sugi HoldingsLtd can either paralyse you or push you to test the numbers yourself and decide what really matters. Move quickly from headline moves to actual risk and reward by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sugi HoldingsLtd?
If Sugi HoldingsLtd has caught your attention, do not stop there. The best opportunities often appear where recent price moves and solid fundamentals meet.
- Target resilient potential by scanning companies that score strongly on financial strength with the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality selling at compressed prices through the 14 high quality undervalued stocks before sentiment shifts and the market reassesses them.
- Stack potential income and stability by reviewing the 29 dividend fortresses that may offer higher yields backed by durable underlying businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com