


EN
Walmart (WMT) Draws Staples Flows And AI Buzz But Is It Already Fully Valued
Walmart (WMT) is benefiting from a sharp sector rotation out of technology, as investors lean into consumer staples while eyeing its new AI shopping tools and growing membership club footprint.
The recent sector rotation into staples has helped Walmart hold onto October’s strong run, even though the share price slipped 1.02% over the last day to US$119.89. A 30 day share price return of 11.03% and 1 year total shareholder return of 13.87% show momentum has been building. The 3 year total shareholder return of 130.29% and 5 year total shareholder return of 156.24% underline how optimism around AI tools, richer membership economics and recent bond offerings has been building over a much longer stretch as well.
Capitalize on the rotation fueling Walmart by lining up your next ideas with a curated set of 29 high quality undervalued stocks.After a sharp October surge and a P/E near 44x, Walmart now trades only about 6% below the average analyst target. Is that discount a reflection of renewed earnings power, or simply caution catching up with a hot chart?
Most Popular Narrative: 22% Undervalued
The most followed narrative on Walmart pegs fair value at $154.58, well above the last close at $119.89, which implies a sizeable valuation gap that bulls are watching closely.
Given the strong GMV and profit trajectory, valuation multiples for the “Other” SBU are likely to trend upward, especially if digital penetration rebounds and margin expansion persists. Looking ahead, we expect: Sustained double-digit GMV growth, albeit at a moderating pace as the base expands; merchandise profit margins to improve through cost optimization and premium offerings; and digital penetration to stabilize or recover, driven by targeted digital campaigns and platform enhancements.
See why 63 investors see Walmart as 22% undervalued.
Result: Fair Value of $154.58 (UNDERVALUED)
Still, the thesis can crack if Walmart’s “Other” segment loses digital traction, or if execution missteps keep those projected margin gains from materializing.
Find out about the key risks to this Walmart narrative.
Another View On Walmart’s Valuation
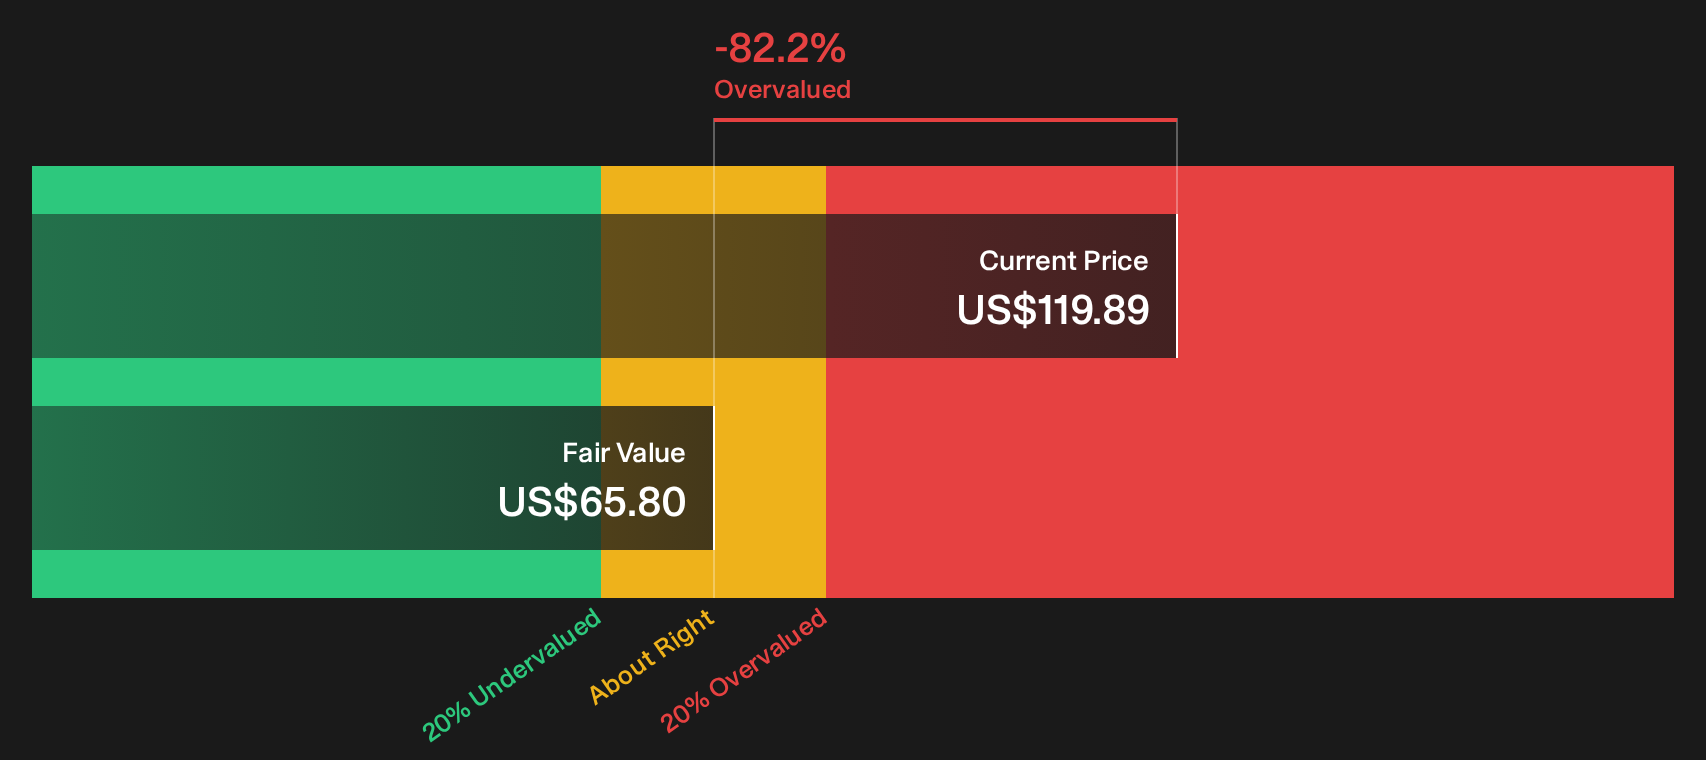
A second lens tells a very different story. Our DCF model estimates Walmart’s future cash flow value at about $65.80 per share, well below the current $119.89 price, which screens as overvalued on this framework. If one method points to a 22% upside and another flags downside, which signal gets your attention?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
That is a wide range of opinions for one ticker, and timing often matters more than consensus. Move quickly, review the underlying data yourself, and then test your view against the 2 key rewards.
Looking for more ideas beyond Walmart?
Walmart might be front of mind today, but your next edge probably sits in a corner of the market you have not checked yet. Let the data do the heavy lifting.
- Target reliable income streams by reviewing companies in the 5 dividend fortresses that prioritize steady payouts supported by consistent financials.
- Hunt for quality at a discount by scanning the 21 high quality undiscovered gems where strong fundamentals have not yet attracted broad attention.
- Reduce portfolio stress by focusing on the 30 resilient stocks with low risk scores that carry resilient balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com