


EN
Q3 Earnings Pressure Could Reshape The Case For Old Republic International Stock
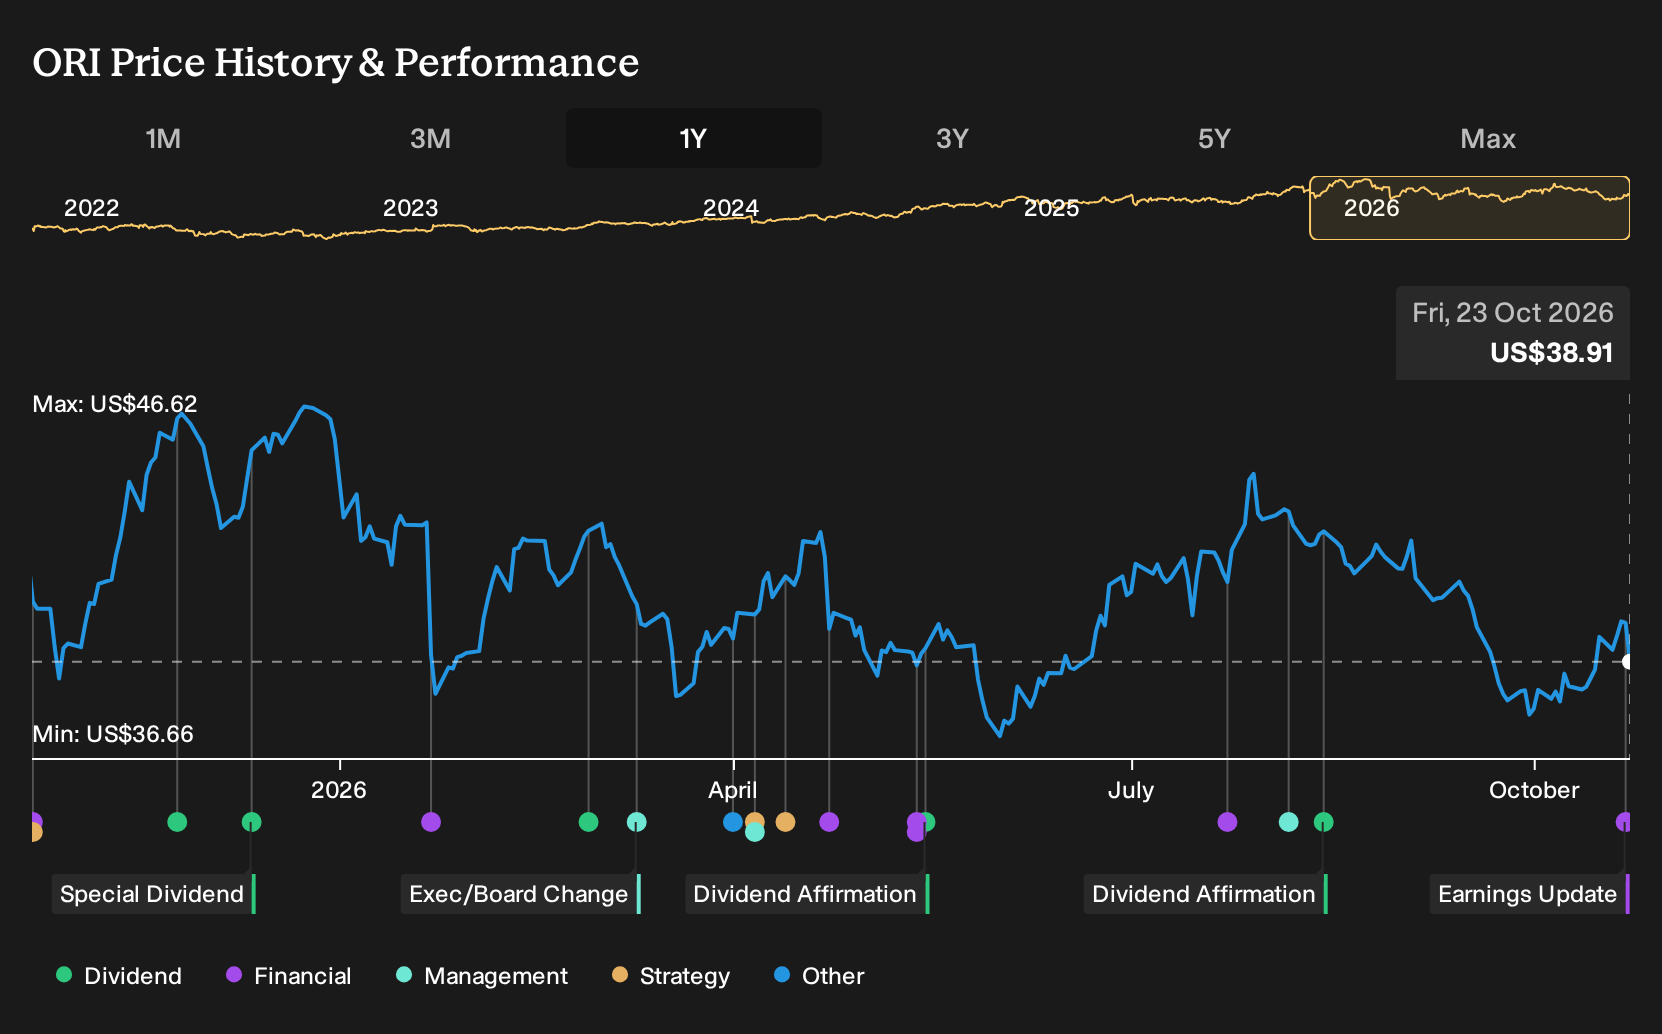
- Old Republic International reported Q3 2026 revenue of US$2,550.5 million and net income of US$243.2 million, alongside nine month revenue of US$7,453.8 million and net income of US$895.6 million, reflecting different earnings trends over the shorter and longer reporting periods.
- The latest update shows Old Republic International balancing growth in auto warranty and the ECM acquisition with expense ratio pressure, technology spending and a soft title insurance market, which together provide context for how efficiently current investments might translate into future underwriting and operating results.
- We will look at how Old Republic International's investment narrative aligns with Q3 margins holding near a 96.1% combined ratio.
Old Republic International Investment Narrative Recap
To own Old Republic International, you need to be comfortable with a slow and steady underwriting story where technology spending and new specialty platforms eventually support cleaner margins. The Q3 2026 report fits that script. Revenue for the quarter and year to date moved higher, while earnings told a mixed story across the shorter and longer periods.
The key near term catalyst is whether the expense ratio stabilizes as auto warranty and the ECM acquisition scale. The biggest current risk is that higher technology and Specialty costs linger without clear productivity gains. That outcome would keep the combined ratio pinned near current levels rather than easing lower.
The latest quarterly earnings release is the focal point. Management reported Q3 2026 revenue of US$2,550.5 million and net income of US$243.2 million, with nine month figures of US$7,453.8 million and US$895.6 million. That pattern gives you a cleaner look at how underwriting and fee income are tracking against rising operating costs.
For catalysts, the most relevant detail is that auto warranty growth and the ECM farm and agriculture business are now contributing inside reported numbers. Those pieces, together with ongoing digitalization and data projects, form the operational test. If they scale cleanly against current spending and a soft title insurance backdrop, Old Republic International can keep its combined ratio within management’s preferred zone.
Old Republic International's current narrative assumes annual revenue growth of 4.1% and earnings today of about US$1.1b, with consensus forecasts pointing to US$11.0b in revenue and US$674.8 million in earnings by 2029. This would equate to an earnings decline of roughly US$425 million from current levels.
Uncover why Old Republic International's fair value indicates a 12% potential upside to its current price. This reflects a valuation gap that could narrow quickly as sentiment shifts.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$43.5 to about US$77.9 per share, which shows how far apart individual views on Old Republic International can sit. Set that against margin pressure in Specialty, heavier technology spending and a softer insurance market, and you are reminded to explore several sharply different viewpoints.
Explore another Old Republic International fair value estimate, including one that suggests it could be worth just $43.50.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Old Republic International research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Old Republic International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Old Republic International's overall financial health at a glance.
Looking for more investment ideas beyond Old Republic International?
Once you have formed a view on Old Republic International, it can help to widen the lens and compare it with other businesses that share similar qualities or offer something completely different. The Simply Wall St Screener is built for exactly that, letting you filter by balance sheet strength, income potential or mispriced quality in a few quick steps.
- If capital preservation is high on your list, start with a short list of companies that score well on resilience and risk by reviewing the 30 resilient stocks with low risk scores.
- For investors focused on finding strong businesses that the market may be overlooking, scan through the 21 high quality undiscovered gems and see which fundamentals line up with your checklist.
- If steady income matters more than rapid capital gains, narrow your search to companies offering higher yields and robust payout profiles using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com