


EN
Norwegian Cruise Line Holdings (NCLH) Stock Looks Like A Bargain Despite Debt Worries
Norwegian Cruise Line Holdings has had a rough ride in the market, with the share price under pressure while investors weigh debt, fuel costs and future demand. The open question is whether the current valuation really lines up with what the company earns.
- Over the past 5 years the stock has fallen 41.3%, which puts the focus squarely on whether today's earnings can justify even the current lower price level.
- Recent commentary around a large debt load and higher fuel expenses, along with concerns about future yield trends, can influence how much value investors are willing to place on Norwegian Cruise Line's profit stream.
- There is a second opinion on Norwegian Cruise Line Holdings worth weighing. See what analysts think Norwegian Cruise Line Holdings's shares could be worth.
The issue now is whether Norwegian Cruise Line's current share price is supported by its earnings when set against the Fair Ratio benchmark.
If you want a benchmark while you assess whether Norwegian Cruise Line Holdings at US$15.10 reflects its earnings risks, compare it with stocks in the 29 high quality undervalued stocks.
Is Norwegian Cruise Line Holdings Still Cheap on Earnings?
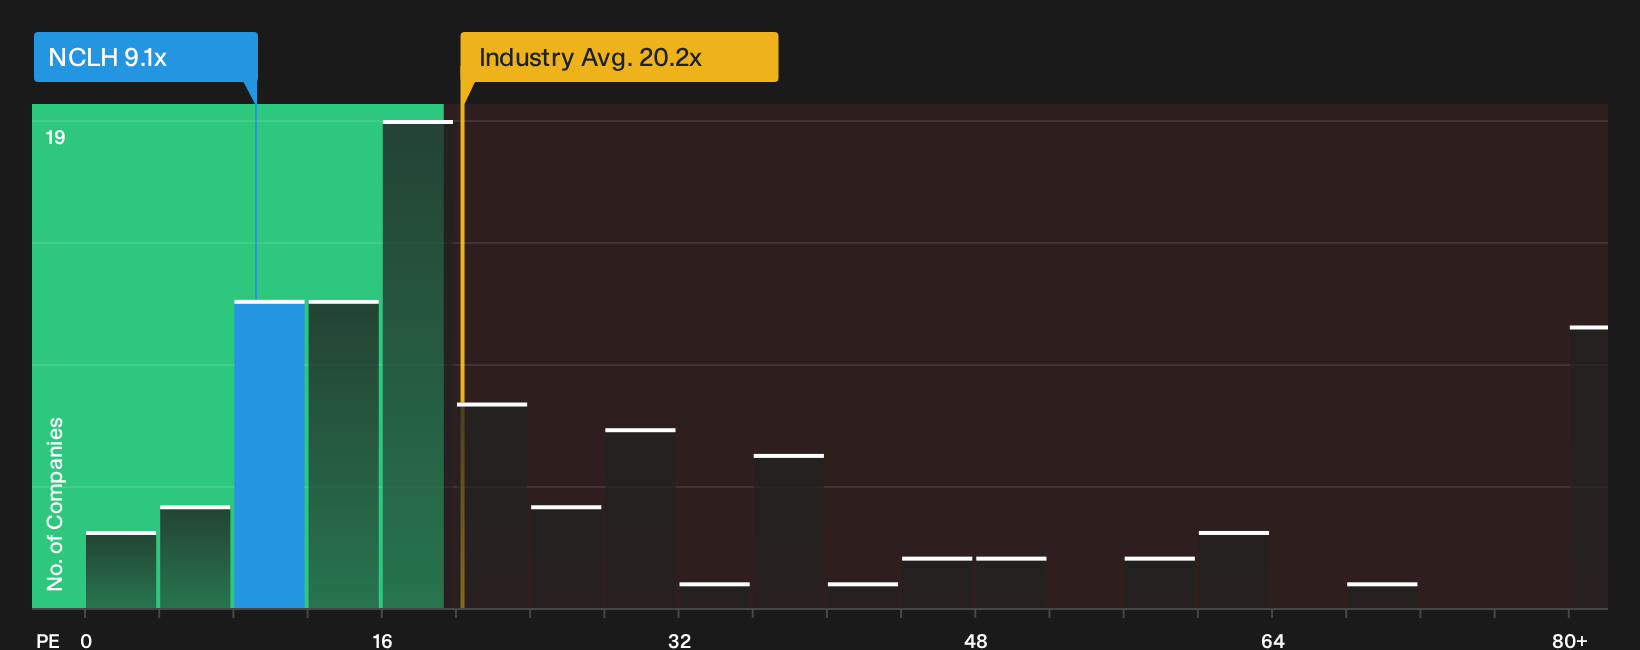
The P/E ratio is a useful lens for Norwegian Cruise Line Holdings because it ties the current share price directly to the earnings the business is generating today. On this measure, the stock trades on a P/E of 9.1x, which is well below the hospitality sector average of 20.2x and the peer group at 43.3x. That gap means the market is attaching a lower price tag to each dollar of Norwegian Cruise Line's earnings compared with many listed travel operators.
The Fair Ratio framework, which considers factors like industry, profitability profile, size and risk, points to a higher P/E than where Norwegian Cruise Line currently trades, so the shares screen as undervalued on this yardstick. Because JPMorgan recently cut its rating on the stock over debt and yield concerns, the current discount suggests investors are already pricing in a fair amount of that caution. If you think the business can sustain its earnings against fuel costs and balance sheet pressure, the present multiple looks like it bakes in those risks to a meaningful degree. Explore the numbers behind Norwegian Cruise Line Holdings's P/E valuation.
The Norwegian Cruise Line Holdings Narrative: What Would Justify Today's Price?
Narratives for Norwegian Cruise Line Holdings pick up where this valuation puzzle leaves off and spell out which earnings, margin and growth paths would need to hold for the shares to be worth materially more or less than today’s price. Each scenario links a fair value estimate to a specific mix of potential catalysts and risks for Norwegian Cruise Line Holdings' business, so you can watch over time which version of events appears to be taking shape on Simply Wall St’s Community page.
Community views on Norwegian Cruise Line split between a delayed but intact turnaround and a much tougher grind against yield pressure and leverage.
Bull case: 22% undervalued
"Structural SG&A and marketing savings, including more than US$500m of identified cost actions since 2024 and an expected 15% reduction in salary and benefits, are already reflected in lower adjusted NCC ex fuel guidance and provide a foundation for future net margin and EPS improvement if revenue stabilizes..."
Discover why this Narrative puts Norwegian Cruise Line Holdings at 22% undervalued.
Bear case: 28% overvalued
"Although Norwegian Cruise Line Holdings is identifying hundreds of millions of dollars of annualized savings and guiding to a slight decline in net cruise cost ex fuel, repeated cuts to 2026 net yield guidance and expectations for net yield to fall around 5% for the year, with declines of about 8.9% in Q3, 6.5% in Q4 and further pressure into H1 2027, point to a scenario where cost initiatives are overwhelmed by weaker pricing and leave EBITDA margins and earnings below what current forecasts imply..."
Explore why this Narrative puts Norwegian Cruise Line Holdings at 28% overvalued.
Norwegian Cruise Line Holdings' valuation is only part of the story
Price and earnings paint one picture of Norwegian Cruise Line, but Simply Wall St's broader checks have flagged specific risk signals that deserve a closer look before you lean on the valuation alone. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com