


EN
TC Energy (TSX:TRP) Following Indigenous Deal Is It A Buying Opportunity Or Priced In
Indigenous investment deal reframes the TC Energy story
TC Energy (TSX:TRP) just closed an Indigenous-led investment agreement tied to its Coastal GasLink project, giving five First Nations an economic interest and long-term revenue exposure to the pipeline corridor.
Recent trading tells a mixed story. TC Energy’s share price is now CA$87.32, with a 30-day share price return of 4.99% but a 90-day share price return that has fallen 9.48%, while the 3-year total shareholder return of 139.22% signals powerful long-term compounding.
Scan Indigenous partnership and energy infrastructure opportunities with a curated list of 16 nuclear energy infrastructure stocks that reflect the long-duration, contracted profile investors often associate with TC Energy.
TC Energy now pairs a long-lived pipeline network with fresh Indigenous partnerships and a CA$87.32 share price that has bounced in the last month but slipped over 90 days. Is that combination currently priced fairly?
Most Popular Narrative: 13% Undervalued
TC Energy’s most followed narrative puts fair value at CA$100.41, above the CA$87.32 last close. This frames the current Indigenous investment news against a stock that the narrative treats as undervalued when using a 6.7% discount rate.
The company has sanctioned roughly $3b of new natural gas pipeline growth projects in 2026 at about 12% weighted-average unlevered after-tax IRRs and 5 to 7 times build multiples, while growing its late-stage and origination backlog. This may underpin future EBITDA as these projects enter service.
See why 70 investors see TC Energy as 13% undervalued.
Result: Fair Value of CA$100.41 (UNDERVALUED)
Still, that upbeat story depends on TC Energy managing its sizeable debt load in a higher rate world, while also avoiding costly delays on major pipeline and power projects.
Find out about the key risks to this TC Energy narrative.
Another View: TC Energy looks expensive on earnings
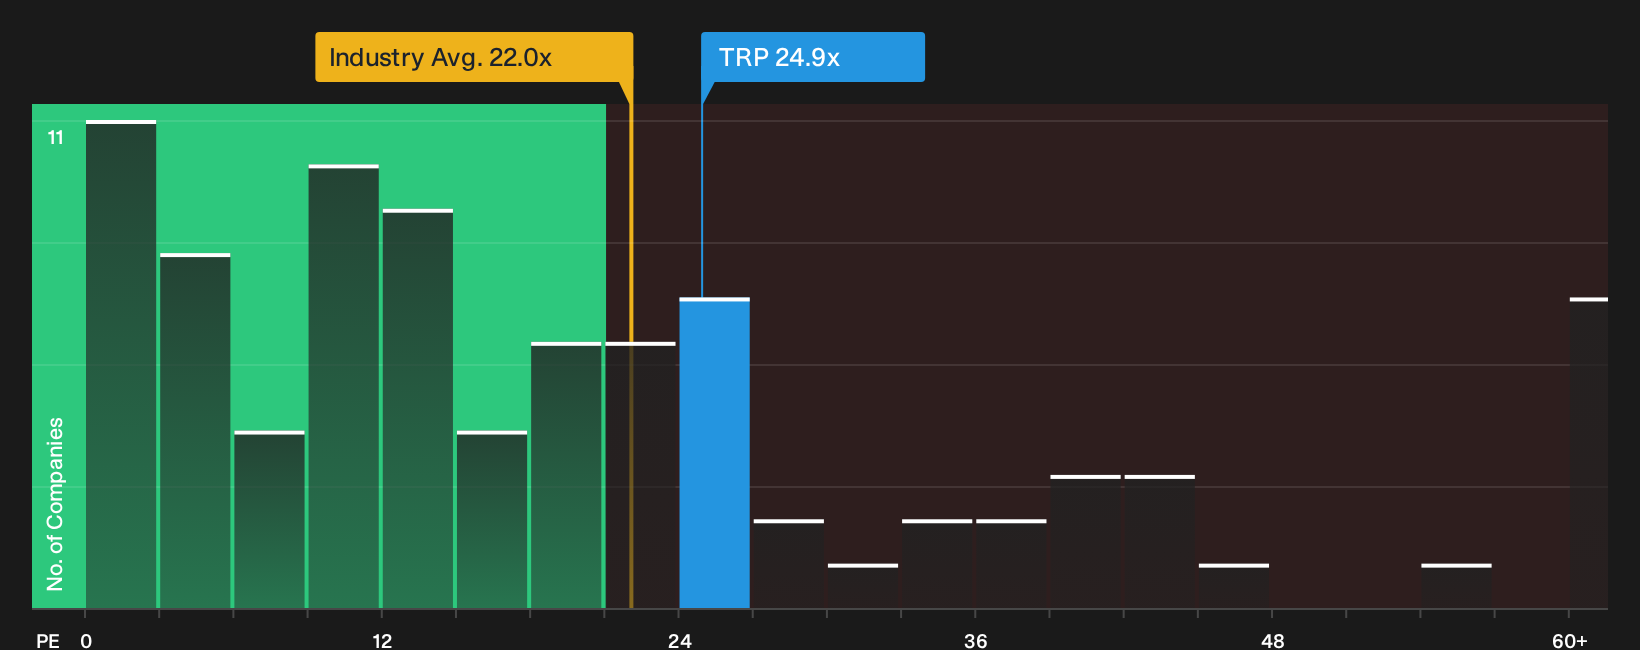
That CA$100.41 fair value narrative leans on future growth. A simpler yardstick, the current P/E of 24.9x, tells a tougher story. TC Energy trades richer than the Canadian Oil and Gas industry at 22x and even above its own fair ratio of 21x, which lifts valuation risk if sentiment cools.
For investors who prefer to anchor decisions to current earnings multiples rather than long-range narratives, this gap between today’s 24.9x P/E and a 21x fair ratio raises a clear question. Is the premium a reasonable price for TC Energy’s project pipeline, or are you paying too much for comfort at CA$87.32.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on TC Energy can leave you torn, which is exactly why it helps to review the data side by side and decide for yourself. To see both the upside case and the concerns investors are flagging, start with the 1 key reward and 2 important warning signs.
Looking for more TC Energy sized investment ideas?
If TC Energy has your attention, do not stop here. Broaden your watchlist with other stocks that match clear fundamentals and focused themes.
- Target potential mispricings and hunt for quality companies trading below their estimated worth through our hand picked set of 2 high quality undervalued stocks.
- Explore income ideas by reviewing a focused group of 3 dividend fortresses that combine higher yields with business strength.
- Manage portfolio risk by scanning a 8 resilient stocks with low risk scores that filters for resilience and financial durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com