


EN
THOR Industries (THO) Could Be 62% Overvalued After Its 3.8% Dividend Increase
Dividend increase puts THOR Industries in focus
THOR Industries (THO) has drawn fresh attention after its board approved a 3.8% increase in the regular quarterly cash dividend to $0.54 per share at its October 13, 2026 meeting.
The updated payout is scheduled for November 10, 2026, for investors recorded as shareholders at the close of business on October 27, 2026. The move highlights the company’s ongoing commitment to cash returns.
Against this dividend decision, THOR Industries’ shares trade at US$70.10, with the price having fallen 33.51% year to date and the 1-year total shareholder return down 35.54%, while the recent 7-day share price return of 2.43% hints at only modest short-term momentum.
Scan how THOR Industries compares with income-focused peers by running through our hand-picked 5 dividend fortresses while this dividend move is fresh.
THOR Industries has raised its dividend while the share price sits well below recent highs. Is that an opening for income investors now, or a signal to wait for an even cheaper entry before committing fresh capital?
Preferred P/E of 20.4x: Is it justified?
THOR Industries now trades on a P/E of 20.4x, which is rich next to both its peer group and wider auto businesses, despite the weak 1-year share return you have just seen.
The P/E ratio compares the current share price with earnings per share. For a manufacturer like THOR Industries that already generates profits, this metric gives a direct sense of how much investors are paying for each dollar of earnings today.
On current forecasts, earnings are expected to grow 20.22% per year, which is faster than the US market projection of 17% and is described as significant over the next three years. That sort of outlook can help explain why the stock trades above the estimated fair P/E of 16.6x. It also means a lot of that earnings recovery story is already reflected in the valuation.
The comparison with peers is stark. THOR Industries is described as expensive against its sector on several fronts, with its 20.4x P/E higher than the peer average of 15.2x, above the Global Auto industry average of 13.2x, and above the estimated fair P/E of 16.6x that the market could move toward if sentiment cools.
Explore the SWS fair ratio for THOR Industries.
Result: Price-to-Earnings of 20.4x (OVERVALUED)
Still, THOR Industries faces risks if consumer demand for recreational vehicles softens or if dealer inventories build. This could pressure earnings expectations already baked into that P/E.
Find out about the key risks to this THOR Industries narrative.
Another view on THOR Industries' valuation
The SWS DCF model paints a very different picture of THOR Industries. On that framework, the current $70.10 share price sits well above an estimated future cash flow value of $26.94, which points to the stock looking expensive rather than offering a margin of safety today.
That kind of gap can matter. If the cash generation implied by the DCF proves closer to reality than the P/E driven optimism, investors relying on the richer multiple could be taking on more downside risk.
Look into how the SWS DCF model arrives at its fair value.
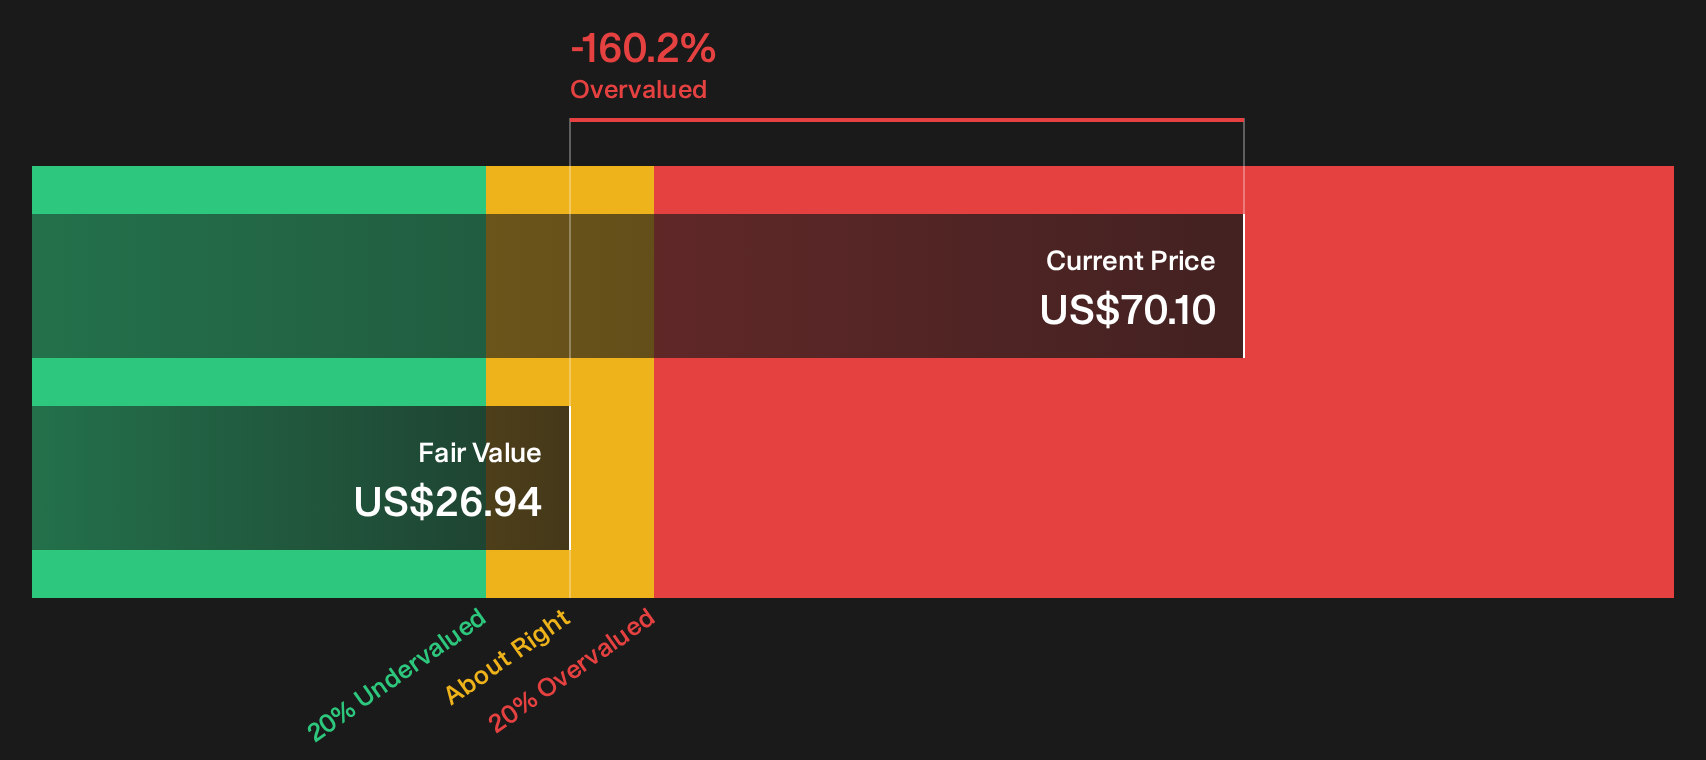
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out THOR Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of signals around THOR Industries point in different directions, so move quickly and check the underlying data for yourself before opinions harden. To weigh those cross currents directly, spend a moment with the 2 key rewards and 1 important warning sign.
Looking for more THOR Industries style investment ideas?
If THOR Industries has you thinking harder about value and income, do not stop here. The next opportunities could be sitting in plain sight on a broader screener.
- Target resilient cash generators by scanning our list of solid balance sheet and fundamentals (24 results) that pair healthier balance sheets with underlying fundamentals.
- Hunt for better value by reviewing the 29 high quality undervalued stocks that filters for stronger quality at prices that may look more reasonable.
- Strengthen your income watchlist by checking the 5 dividend fortresses that highlights higher yielding payouts with more robust profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com