


EN
Learn Why The Bull Case For J. Front Retailing Stock Could Change Following Profit Guidance Raise
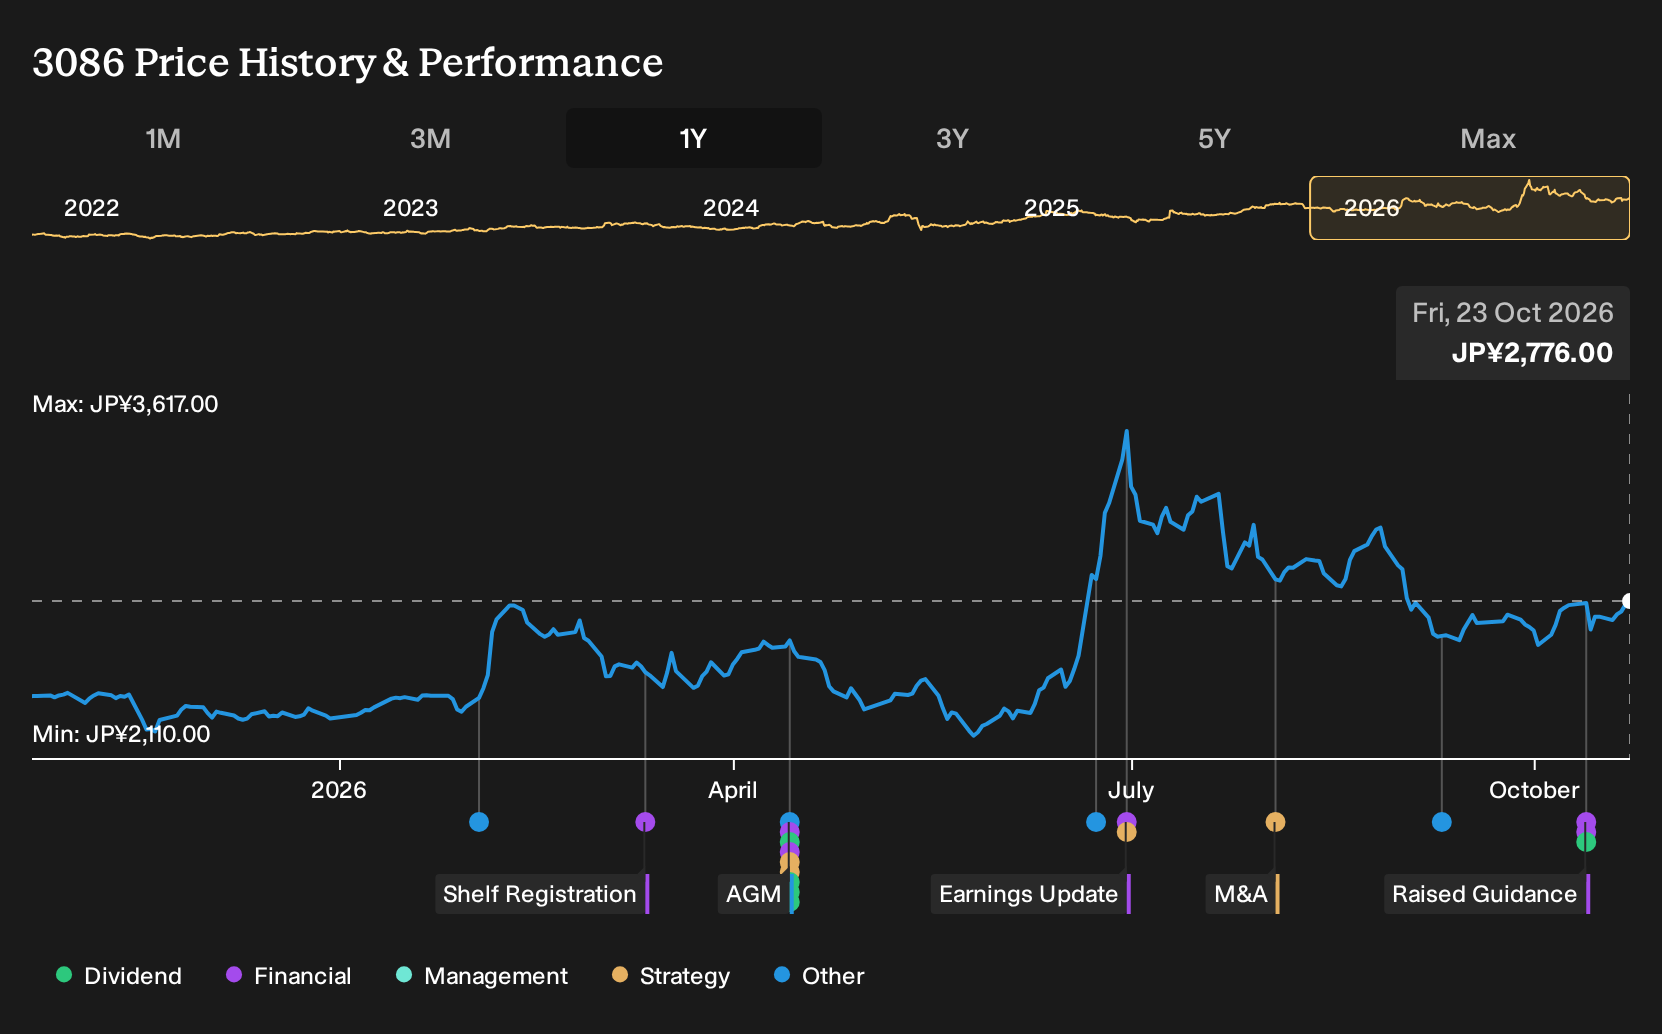
- J. Front Retailing reported that September 2026 consolidated revenue declined 3.5% year over year, while first half sales reached ¥213,821 million with net income of ¥17,379 million.
- Despite softer recent revenue and earnings, J. Front Retailing raised full year business profit guidance and nudged up its second quarter dividend to ¥28 per share.
- Next, the focus shifts to what this higher full year profit guidance, built on strong duty free demand, could mean for the investment narrative.
J. Front Retailing Investment Narrative Recap
To own J. Front Retailing, you need to believe the multi business model can convert strong duty free and out of store demand into steadier profit, even while traditional department store sales face pressure. The raised full year business profit guidance leans on that thesis and suggests management still sees operating momentum in key traffic driven categories.
The short term swing factor remains inbound tourism and duty free spending, which currently supports earnings but is exposed to currency moves and luxury demand. The biggest risk is that renovation disruption, higher SG&A and front loaded investment outpace any revenue uplift. The latest numbers do not remove that concern.
The most relevant update for this catalyst mix is the October guidance revision. J. Front Retailing now expects full year sales revenue of ¥470,000 million and business profit of ¥53.5 billion, with profit attributable to owners of parent of ¥29,000 million and basic EPS of ¥118.23, all referencing the fiscal year ending February 2027.
This guidance sits beside softer first half sales of ¥213,821 million and net income of ¥17,379 million, so the key question is execution. Strong out of store and duty free sales in the Department Store Business currently underpin the higher profit view. Any slowdown in inbound demand or delays in renovation payoffs could quickly test that outlook.
J. Front Retailing's current analyst narrative points to revenues of ¥476.0 billion and earnings of ¥35.8 billion by 2029, based on forecast revenue growth of 2.6% per year and an earnings increase of ¥8.3 billion from current earnings of ¥27.5 billion.
Uncover why J. Front Retailing's fair value indicates an 11% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
One alternate angle on J. Front Retailing leans heavily on renovation risk. The most cautious analysts were working off slower revenue growth of about 1.0% a year and earnings of ¥33.4b by 2029 before this guidance and dividend news. That more pessimistic script assumes construction costs and disruption weigh harder, so you may want to compare both sets of assumptions and decide which feels closer to your own view.
Explore another J. Front Retailing fair value estimate, including one that suggests as much as 11% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your J. Front Retailing research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for J. Front Retailing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate J. Front Retailing's overall financial health at a glance.
Looking For More Ideas Beyond J. Front Retailing?
If the J. Front Retailing setup feels finely balanced and you want a few more candidates on your watchlist, the Simply Wall St Screener can help you zero in on other businesses that match your risk and return preferences.
- For investors hunting for mispriced quality, start with companies that blend strong fundamentals with what still looks like modest market attention through our 72 high quality undiscovered gems.
- If capital preservation sits near the top of your priority list, focus on businesses that score well on stability and financial risk by scanning our 22 resilient stocks with low risk scores.
- When you care most about robust balance sheets and underlying financial strength, look for companies that pass strict liquidity and solvency filters using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com