


EN
3 UK Stocks Linked To New Council Spending On Housing And Infrastructure
Fresh government money flowing into social housing, local transport and regional infrastructure has just redrawn part of the UK investing map, and many investors are not looking there yet. New funding streams, preferential lending rates and extra firepower for councils and mayors could shift where future projects land. This article unpacks that story and introduces 3 UK-listed stocks exposed to this news that merit a closer look.
The three stocks below are just a starting sample from this theme, and the full screen surfaced 5 more UK Municipal Housing and Local Infrastructure Beneficiaries with equally compelling narratives that are not covered in this article. To pinpoint ideas that best fit your risk profile, head straight into the UK Municipal Housing & Local Infrastructure Beneficiaries screener to identify, filter and analyze the highest conviction plays.
Living REIT (LSE:LIVE)
Living REIT fits directly into the UK Municipal Housing & Local Infrastructure Beneficiaries theme, because its specialist supported housing, senior living and care homes portfolio sits at the intersection of policy support, social need and inflation-linked residential rents.
Living REIT currently generates about £40.6 million of rental income from UK residential REIT activities and has a market value of roughly £328 million.
Expansion into senior living through the addition of 2,163 rental homes valued at £185m broadens Living REIT’s earnings base beyond supported social housing and is guided to deliver high single digit earnings accretion in full-year 2027, which could support higher adjusted EPRA earnings and dividend capacity.
The real test lies in how a single pressure point on funding costs and leverage shapes what flows through to margins and future income potential.
That pressure point is exactly what the full narrative for Living REIT unpacks, explaining how funding risk, rent indexation and pipeline execution could still accelerate the story.

Marshalls (LSE:MSLH)
Marshalls is a fixture in UK streetscapes, supplying paving, kerbs, drainage and roofing into the same public realm, regeneration and housing upgrade work that councils and housing associations are being nudged to accelerate.
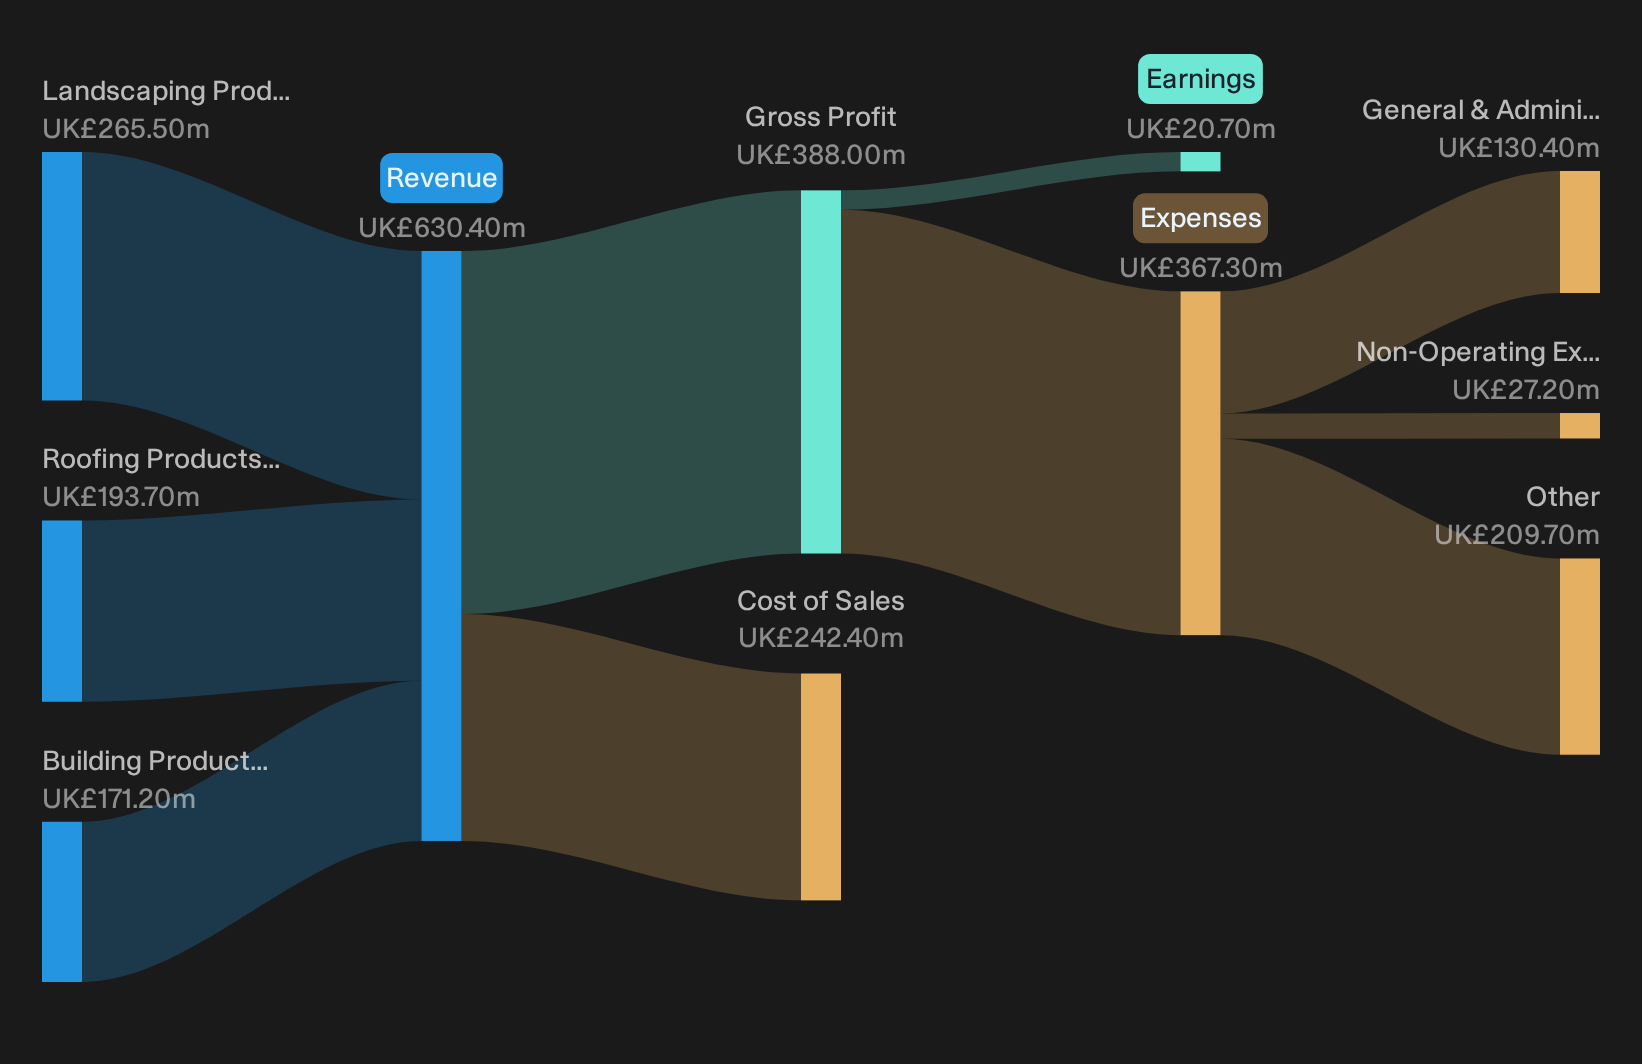
Marshalls manufactures landscaping, building and roofing products, closely tied to estate upgrades and local infrastructure, with around £265.5 million from Landscaping Products, £193.7 million from Roofing and £171.2 million from Building Products. The group is valued at roughly £440.1 million.
The group’s consistently high cash conversion, at 88% in 2025 and 98% in H1 2026, together with leverage moving toward the 0.5 to 1.5 times EBITDA target range, creates room for future capital allocation choices that could support additional revenue streams and improve net margins.
What happens to Marshalls earnings power if a single pressure point on public realm demand and council-led regeneration tilts in its favour?
If that tilt arrives in earnest, the full picture only really comes through in the full narrative for Marshalls, where Marshalls’ cycle sensitivity and upside are laid bare.
Travis Perkins (LSE:TPK)
Travis Perkins is central to the UK Municipal Housing & Local Infrastructure Beneficiaries theme because its builders’ merchant branches, civils units and social housing repair services sit in the supply chain that feeds council-led housing projects and regeneration work.
Travis Perkins runs a broad building materials network in the UK, supplying contractors and social housing landlords. Merchanting produced about £3.7b of revenue and Toolstation about £849 million, with the whole group generating roughly £4.5b. The business carries a market value near £1.3b.
For investors tracking this municipal housing angle, the core question is how Travis Perkins can turn that exposure into steadier earnings rather than just higher volumes.
Ongoing work to protect and expand gross margin through disciplined price pass through, tighter control of low margin work and more professional procurement could create room for Travis Perkins to convert flat or even slightly lower volumes into higher operating profit and stronger net margins.
What happens if a single unseen pressure on that margin focused playbook shifts, just as council and housing association projects start to move again?
If that unseen pressure is what you are watching, the full narrative for Travis Perkins shows how Travis Perkins’ margin work could decouple earnings from the project cycle.

Seeking Alternatives Before The Crowd
Fresh ideas do not stay quiet for long. Once the breakout momentum is caught, ideal entry points can start dropping fast. These are under the radar for now, act now.
- Target steadier income streams by scanning 5 dividend fortresses, built to spotlight businesses where cash payouts and balance sheets already do the heavy lifting.
- Ride early momentum shifts with 8 high quality undervalued stocks, which can flag financially solid operators before valuation gaps close and prices start moving.
- Channel your curiosity into potential advantages by reviewing 4 resilient stocks with low risk scores, curated to highlight resilient operators before crowd attention sends volatility higher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com