


EN
China Mobile (SEHK:941) Stock Looks Hard To Fault On Current Earnings
China Mobile has delivered a powerful 5 year share-price run, so the immediate question for investors is whether that performance lines up with the earnings the telecom group is producing today. With the stock now back from its recent highs, the core issue is whether the current valuation still matches what the underlying profit stream can reasonably support.
- Over the past 5 years, China Mobile has returned about 128%, which puts real pressure on the numbers to show that kind of price performance is grounded in enduring earnings power.
- The business model leans on recurring mobile and broadband service income, which can support a relatively stable earnings base and gives investors a clearer view when judging what they are paying for each unit of profit.
- Your read on China Mobile is one view; the desks covering it have another. See what analysts think China Mobile's shares could be worth.
The stock's next move may depend on whether the price investors see today is adequately explained by China Mobile's current and expected earnings profile.
If you want a wider lens on whether China Mobile's earnings-based valuation still appeals, it can help to compare it with other 196 high quality undervalued stocks
Is China Mobile Fairly Priced on Earnings?
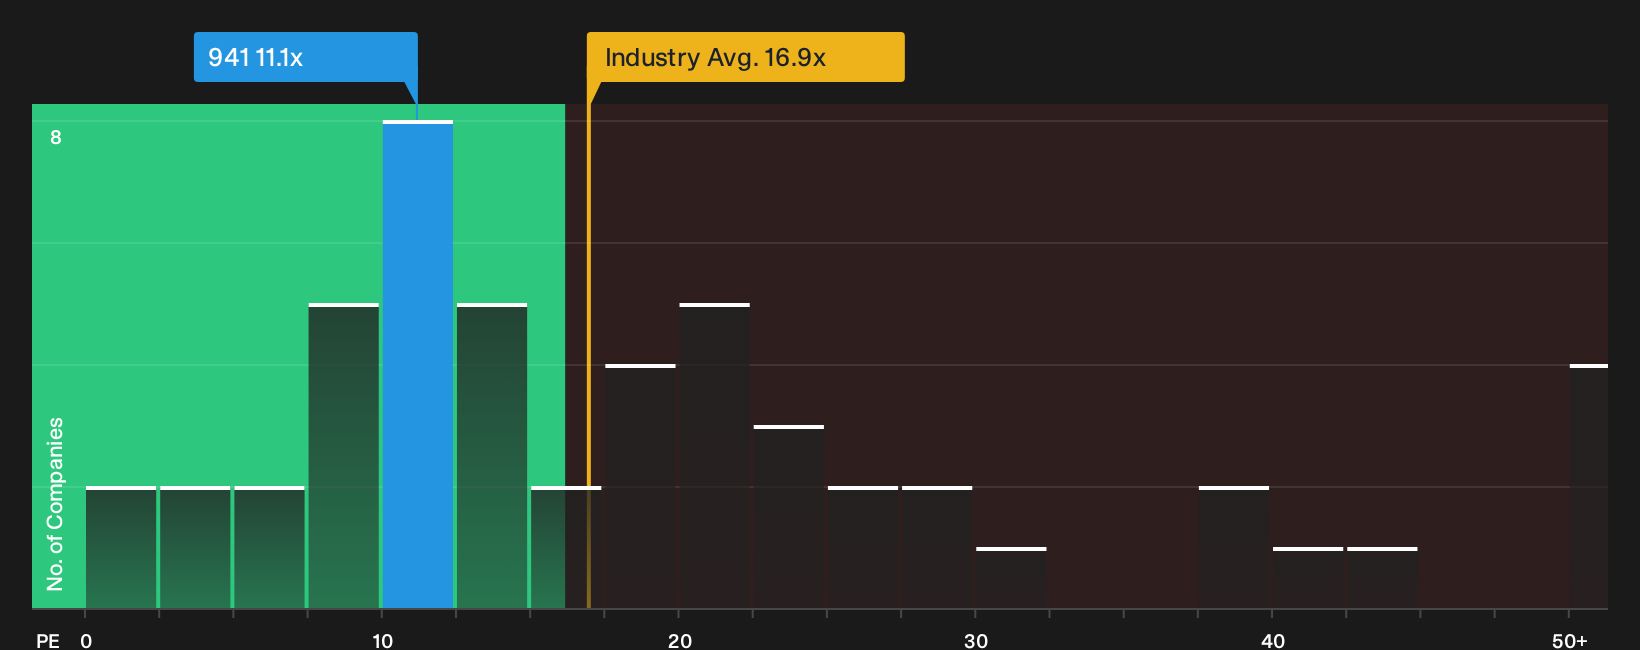
P/E fits China Mobile because investors are mainly paying for a steady stream of telecom earnings rather than a big speculative story. On this metric, the stock trades on about 11.1x earnings, which sits below the Wireless Telecom industry average of roughly 15.0x. It also comes in well under the broader peer group at around 22.1x, so the market is not attaching a particularly rich label to each dollar of profit.
The fair P/E level from the valuation model, which blends China Mobile's growth profile, margins, risk and scale, points to a figure close to where the shares trade now. That suggests the current multiple is roughly in line with what would be expected given the business characteristics, rather than sending a clear cheap or expensive signal on its own. To judge whether this P/E is attractive for a portfolio, you still need to weigh it against your view on the durability of China Mobile's cash flows and the income you expect to collect over time. Explore the numbers behind China Mobile's P/E valuation.
The China Mobile Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for China Mobile and describe which paths for growth, profitability and earnings would need to occur for the current share price to look materially higher or lower. Each scenario links its value anchor to a clear view on how China Mobile's growth, margins and risk profile might change over time, so you can revisit those underlying assumptions as new information appears on the Community page.
One of the top community narratives on China Mobile: 35% undervalued
"While traditional telecom services show low growth, emerging segments (cloud, AI, computing) are becoming the primary drivers of long-term value creation..."
Discover why this Narrative puts China Mobile at 35% undervalued.
One more China Mobile check before you stop at the P/E
Price multiples and narratives tell you what the market thinks today, yet broker projections a few years out give you another lens on where earnings could land relative to this share price. Explore where analysts expect China Mobile to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com