


EN
Will Q3 Cash Distribution Change Dorchester Minerals (DMLP) Narrative
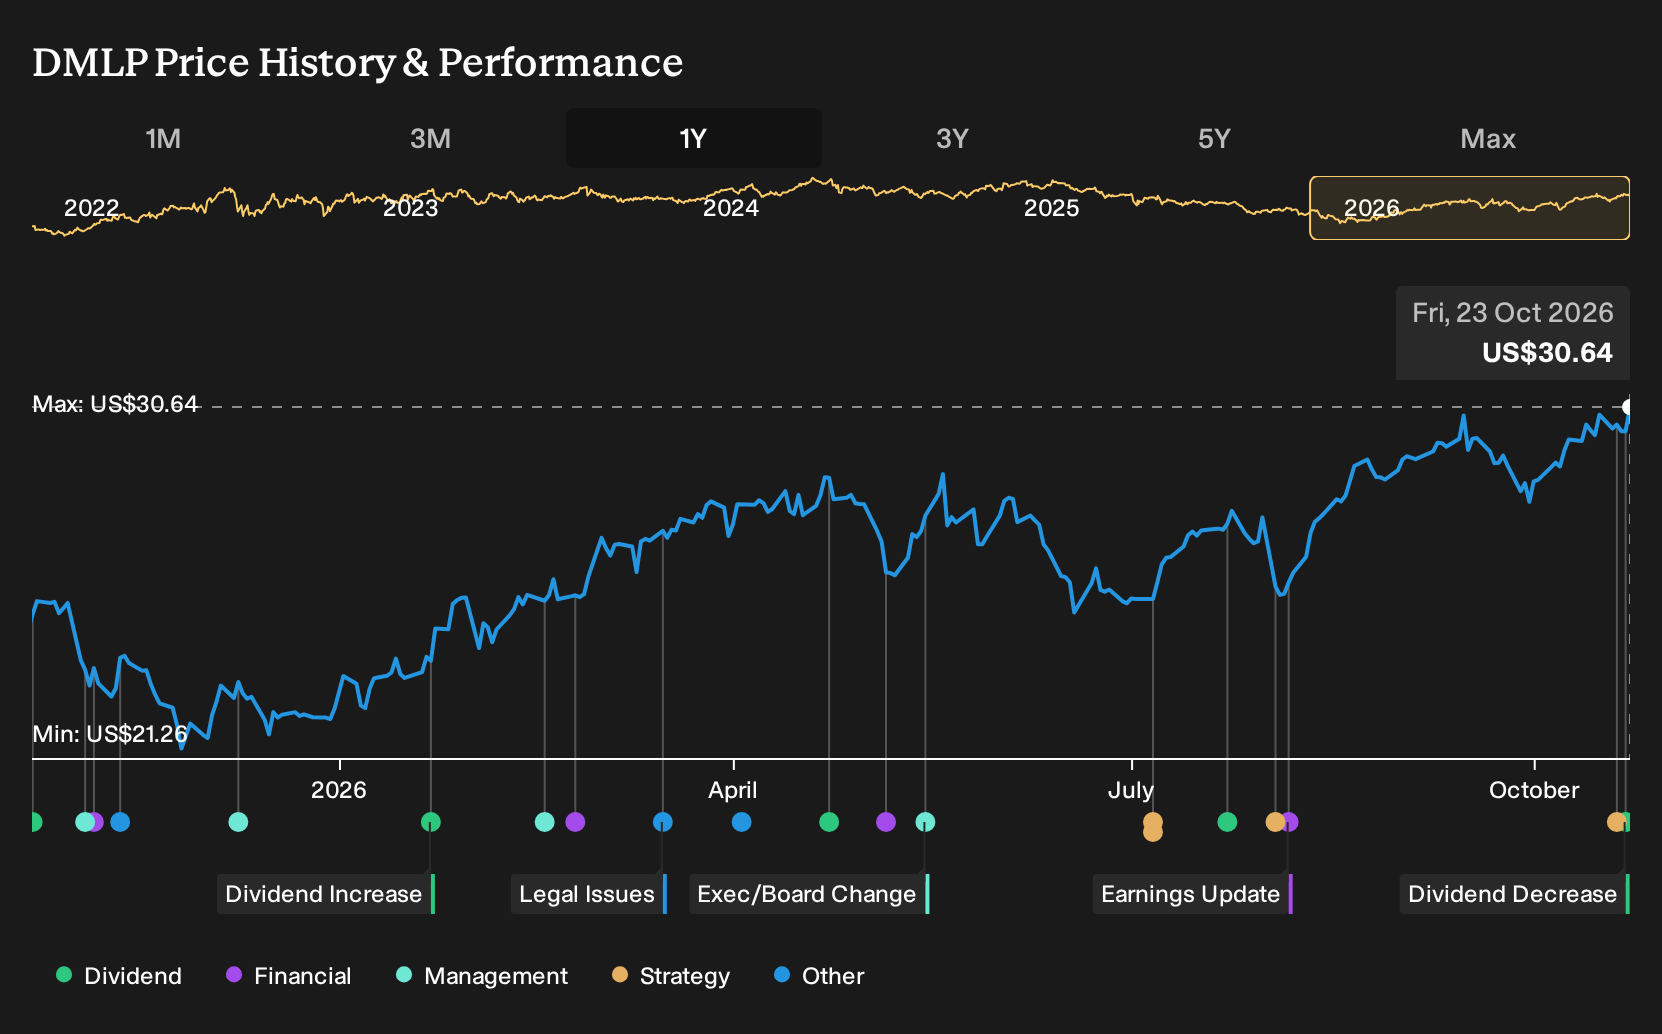
- Dorchester Minerals reported its third quarter 2026 cash distribution of $0.882297 per common unit, tied to activity through September 30 and payable on November 12 to unitholders of record as of November 2.
- The partnership detailed roughly $37.0 million in royalty receipts, $3.0 million from net profits interests and $6.3 million in lease and other income, with investors monitoring how this cash profile aligns with earnings that analysts view as providing limited coverage for distributions.
- The following review considers how Dorchester Minerals’ third quarter cash distribution and disclosed cash flows might influence the broader investment narrative.
What Is Dorchester Minerals' Investment Narrative?
Dorchester Minerals appeals to investors who want direct exposure to U.S. royalty income without funding heavy drilling budgets. The partnership collects royalties and net profits interests from a broad base of properties, so the story hinges on consistent production volumes, realized pricing and disciplined administration of those mineral rights. The latest $0.882297 distribution, backed by royalties, net profits and lease income, reinforces that cash generation is still flowing through the structure.
The tension sits in the mismatch between high cash payouts and earnings coverage. Analysts flag that distributions are not well covered by profits, and earnings have trended weaker over a multi year stretch, even as Dorchester Minerals trades well below some intrinsic value estimates and has delivered solid multi year total returns. This new dividend level feeds the near term income appeal but also highlights that the main risk is less about one quarter’s check and more about longer term sustainability of the payout relative to underlying earnings and cash flow dynamics.
There's only one way to know the right time to buy, sell or hold Dorchester Minerals. Head to Simply Wall St's company report for the latest analysis of Dorchester Minerals's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Dorchester Minerals research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Dorchester Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, which makes it easy to evaluate Dorchester Minerals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Dorchester Minerals?
If Dorchester Minerals has sparked fresh questions about income, risk and valuation, it can help to line it up beside a wider set of opportunities. The Simply Wall St Screener lets you scan across sectors, balance sheet strength and payout profiles so you can pressure test your thesis rather than anchoring on a single stock.
- For investors hunting potential mispricings with stronger financial underpinnings, start with a focused group of 21 high quality undiscovered gems that combine quality fundamentals with relatively low market attention.
- If capital preservation is high on your list, filter for resilient businesses by running a screen on 30 resilient stocks with low risk scores that score well on stability and financial strength.
- Income seekers who also care about balance sheet resilience can zero in on companies with cleaner finances by checking the list of solid balance sheet and fundamentals (24 results) to see which listed businesses clear a higher quality bar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com