


EN
Eaton (ETN) Gains On Analyst Support, Is The Stock Still Cheap?
Eaton stock: why recent analyst moves and sustainability headlines matter
Recent earnings estimate revisions for Eaton (ETN) have put fresh attention on the company’s data center projects, Electrical Americas capacity build out, and expansion in higher value electrical and aerospace markets.
Eaton’s share price has pulled back recently, with a 7 day share price return of down 6.4% and a 30 day share price return of down 16.8%. However, the year to date share price return is 11.9% and the 3 year total shareholder return is 94.6%, which indicates longer term momentum while short term sentiment cools around the data center and sustainability headlines.
Scan other power and grid players riding similar data center and electrification themes by reviewing the hand picked 42 power grid technology and infrastructure stocks alongside Eaton.
So is Eaton’s slide a clean read on the underlying business, or just a reset in enthusiasm around data centers and sustainability stories that now needs to be squared with the valuation on offer?
Most Popular Narrative: 29% Undervalued
Eaton’s last close at $366.11 sits well below the most followed fair value narrative of $517.06. This frames the recent pullback as a valuation gap rather than a broken story.
Eaton Corporation (NYSE: ETN) is one of the rare institutions that has managed to turn the physical constraints of heavy industry and metallurgy to its advantage. Its monopolistic position, benefiting from high material constraints (GOES), years-long delivery times, and in-cabinet thermal densities of 120 kW, along the Voltage Cascades from a 400,000-volt grid to 1 volt on a chip, has provided the company with an unsurpassable economic moat.
See why 15 investors see Eaton as 29% undervalued.
Result: Fair Value of $517.06 (UNDERVALUED)
Still, the Eaton story could be knocked off course if AI data center spending cools, or if transformer and GOES supply constraints ease faster than expected.
Find out about the key risks to this Eaton narrative.
Another angle on Eaton’s valuation
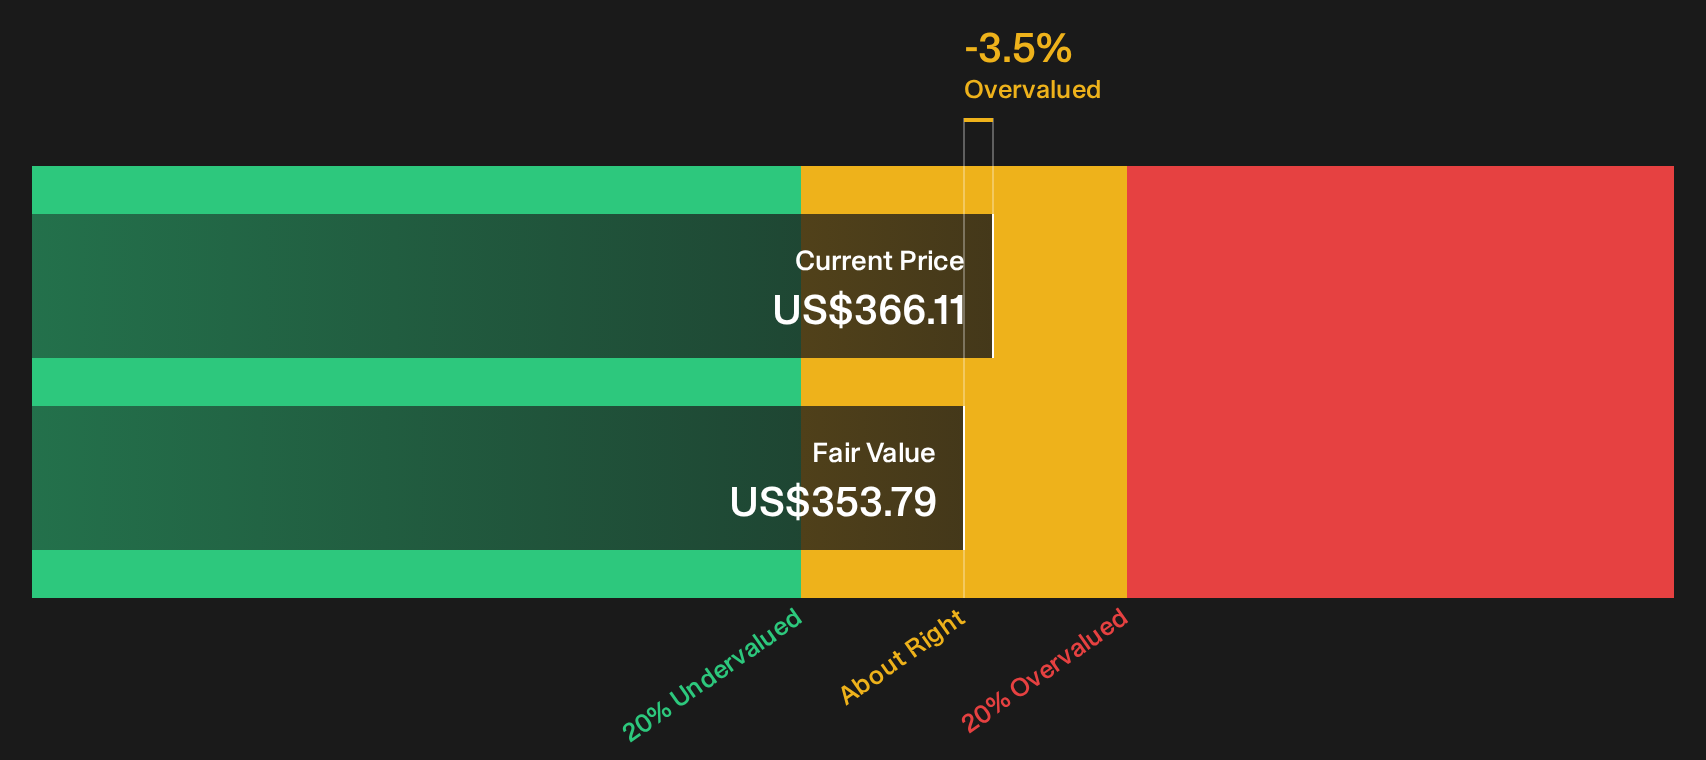
The user narrative pegs Eaton’s fair value at $517.06 based on a rich scenario and multiples blend. Our SWS DCF model paints a cooler picture, with an implied value of $353.79 per share, which makes today’s $366.11 price look slightly expensive on that cash flow view.
That sets up a clear question for investors: Is the market more likely to gravitate toward the higher narrative fair value or toward the more restrained DCF outcome as expectations around data centers and electrification reset over time?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the mixed tone around Eaton has you on the fence, shift your focus from headlines to hard numbers and test both the upside and the downside. Start with the 2 key rewards and 1 important warning sign.
Looking for more Eaton investment ideas?
If Eaton has sharpened your appetite for opportunities in electrification and infrastructure, you can keep your momentum going by searching for other stocks that match your risk and return preferences using Simply Wall Street’s screener.
- Target potential upside in quality names by scanning the 21 high quality undiscovered gems that may not be on every investor’s radar yet.
- Strengthen your downside protection by focusing on a list of solid balance sheet and fundamentals (24 results) that can better handle tough conditions.
- Dial back portfolio volatility by concentrating on a 30 resilient stocks with low risk scores that screens for more resilient businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com