


EN
argenx (ENXTBR:ARGX) Could Be 14% Above Fair Value After Q3 Earnings
argenx (ENXTBR:ARGX) moved into focus after its third quarter 2026 results, as the biopharma group reported higher revenue, net income and earnings per share for both the quarter and the first nine months.
The share price reaction has been mixed, with argenx up 7.5% over the past week but down 7.5% over the past month, even as recent news has included stronger Q3 earnings, fresh Phase 3 data for VYVGART Hytrulo and ongoing attention on its broader autoimmune pipeline. Over a longer stretch, the stock shows positive momentum, with an 8.1% year to date share price return and a 1 year total shareholder return of 11.4%, building on a very large 5 year total shareholder return of just over 3x.
Scan beyond argenx and line up other autoimmune and biotech opportunities. Use our hand-picked 612 high quality undiscovered gems as a starting watchlist after this Q3 update.
After a sharp Q3 beat and a share price that has already delivered strong multi year gains, the key question now is whether argenx still offers meaningful upside or if most of the easy money is behind it.
Most Popular Narrative: 14% Overvalued
The most followed valuation view on argenx pegs fair value at €686.43, below the latest close of €782.20. This frames the debate around whether recent Q3 strength already reflects much of the opportunity that narrative assigns to VYVGART and the wider autoimmune pipeline.
👉 Profile: High-growth biotech compounding story
👉 Investment type:• Growth + clinical optionality
• High volatility👉 Core thesis:
• If VYVGART becomes a multi-indication platform drug → significant upside
• If pipeline fails or pricing pressure intensifies → material downside risk
See why 2 investors see argenx as 14% overvalued.
The fair value figure of €686.43 comes from a narrative authored by kapirey that applies a 7% discount rate and incorporates a 27% profit margin alongside a future P/E of 29. According to kapirey, that framework points to argenx trading about 14% above their estimate of what the cash generation and risk profile justify today.
That narrative leans heavily on VYVGART already being commercial, on reported net income of $1.29b and on a business that has become profitable while still spending $1.36b on R&D and $1.37b on SG&A. It also flags the concentration in a single drug, exposure to pricing pressure and typical late stage biotech clinical risk as reasons not to push fair value closer to current analyst targets, even with earnings forecast to grow 20.3% per year and return on equity expected to reach 20.1% in three years.
On that view, argenx is treated as a growth story with meaningful clinical optionality where current earnings quality and high forecast growth rate are acknowledged, yet balanced against a rich recent share run, P/E of 29.2x and the possibility that pricing or trial setbacks could change the earnings trajectory quickly. In short, the memo frames today’s price as baking in a strong outcome across several indications rather than paying for only the already approved uses.
Result: Fair Value of €686.43 (OVERVALUED)
Still, any serious pricing reset on VYVGART or an unexpected late stage trial failure could quickly weaken confidence in this argenx overvaluation case.
Find out about the key risks to this argenx narrative.
Another View: Market Multiples Point To argenx As Expensive
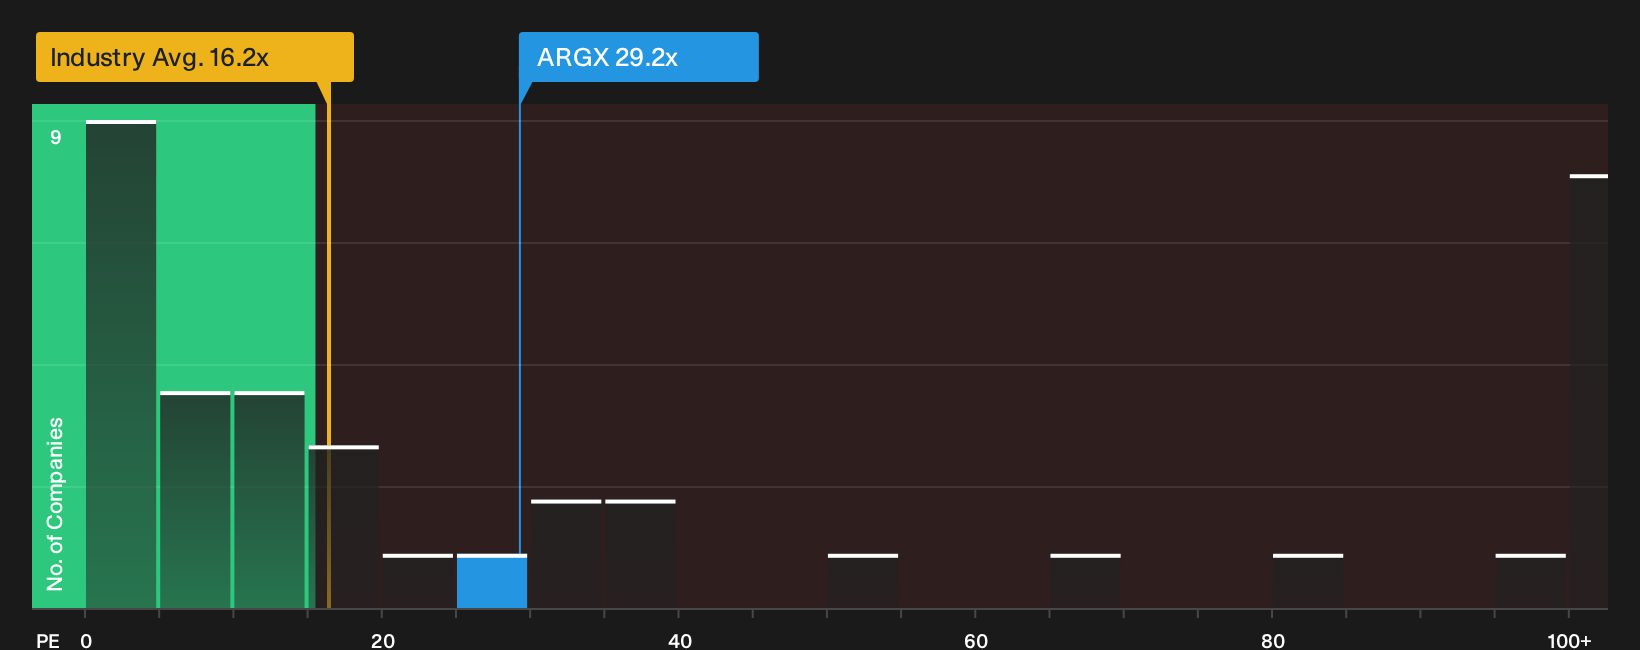
That 14% overvaluation memo is not the only lens. On current numbers, argenx trades on a P/E of 29.2x, below its peer average of 39x but above the European biotech group at 16.2x and above an estimated fair ratio of 25.8x, which suggests limited margin for error if growth under-delivers.
Investors comparing these ratios to their own hurdle rates and risk appetite may want to stress test what happens if sentiment shifts back toward that fair ratio level, particularly given the strong multi year share price run, before deciding how much room they see left in the story. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed signals in the argenx story so far. Act quickly, review the underlying forecasts, risks and rewards, then weigh the 4 key rewards and 1 important warning sign against your own expectations.
Looking for more investment ideas beyond argenx?
If argenx has you thinking more critically about price, quality and risk, now is the moment to widen your opportunity set before the next wave of moves.
- Target steadier potential returns by reviewing companies that show 222 resilient stocks with low risk scores and may better match a cautious risk profile.
- Hunt for quality at a possible discount by scanning 195 high quality undervalued stocks that pair solid fundamentals with what may be mispriced expectations.
- Build a watchlist of sturdier balance sheets by checking the list of solid balance sheet and fundamentals (205 results) to see which businesses back their stories with financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com