


EN
Unite Group (LSE:UTG) Sells School Asset As Debt Cut Keeps Value Question Open
Unite Group (LSE:UTG) has agreed to sell the academy school at its Hawthorne House scheme in London for £40.7m, recycling capital from a non student asset and directing proceeds toward lowering debt.
Unite Group’s latest disposal comes at a time when momentum has been mixed. The 7 day share price return is 2.46%, the 90 day share price return has declined 17.92%, and the 1 year total shareholder return is down 16.71%.
Scan a curated 8 high quality undervalued stocks that, like Unite Group, combines asset-heavy business models with a focus on balance sheet discipline and potential mispricing.
Unite Group now trades at a sizeable discount to both analyst targets and one valuation estimate, even as it trims debt with asset sales. Is that gap a warning sign or a potential opportunity on price alone?
Preferred Price-to-Sales Multiple of 5.7x: Is it justified?
On simple pricing, Unite Group screens as inexpensive compared to several yardsticks, even after a long share price slide. The last close of £4.58 sits against a DCF-derived fair value of £7.25 and a flag that the stock trades at good value versus both peers and the wider Residential REITs industry.
The preferred gauge here is the P/S ratio because this is a property-heavy REIT where revenue is often a more stable reference point than near term earnings. Unite Group trades on a P/S of 5.7x, which is indicated as attractive relative to both similar companies and the broader European Residential REITs group.
Against the industry, that 5.7x P/S is described as good value versus a Residential REITs average of 7.7x. It is also flagged as appealing versus an estimated fair P/S of 7x based on the SWS fair ratio, which points to a level the market could move towards if sentiment or fundamentals line up.
Explore the SWS fair ratio for Unite Group.
Result: Price-to-Sales of 5.7x (UNDERVALUED)
Still, Unite Group carries clear risk flags, including a recent annual revenue decline of 4.1% and a reported net loss of £506.2m, which could weigh on sentiment.
Find out about the key risks to this Unite Group narrative.
Another View: DCF Says The Gap Is Even Wider
Price to sales paints Unite Group as inexpensive, yet the SWS DCF model goes further. With the shares at £4.58 against an estimated future cash flow value of £7.25, that approach also points to undervaluation on paper. The question is whether the cash generation needed to close that gap actually arrives.
Look into how the SWS DCF model arrives at its fair value.
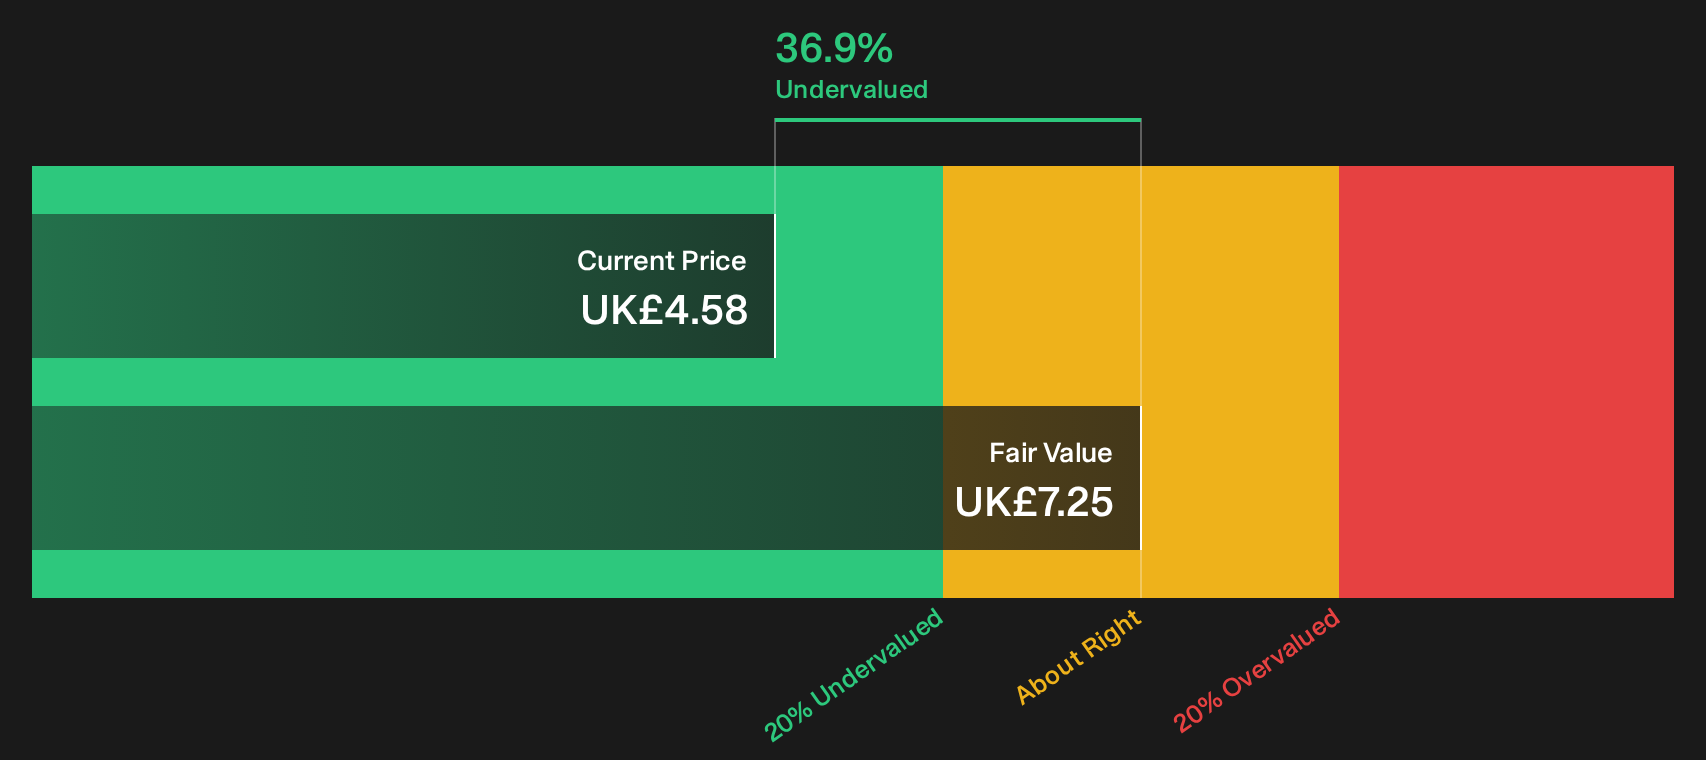
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Unite Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by Unite Group’s mix of risks and potential upsides? Act quickly, work through the numbers yourself, then weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Unite Group?
If Unite Group has sharpened your focus on value and risk, do not stop at a single ticker. A broader watchlist can surface opportunities you might otherwise overlook.
- Target mispriced quality by scanning a curated set of strong businesses that screen as cheap on fundamentals through the 8 high quality undervalued stocks.
- Strengthen your defense by reviewing a list of solid balance sheet and fundamentals (9 results) that can help you focus on sturdier companies when conditions get choppy.
- Hunt for future leaders early by checking a focused group of 5 high quality undiscovered gems that rarely appear on mainstream radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com