


EN
Primary Health Properties (LSE:PHP), Why Is It Back In The Spotlight?
Primary Health Properties (LSE:PHP) has agreed a 50:50 joint venture with Singapore’s GIC, moving 27 private hospitals into a £0.7b vehicle and expecting about £0.5b in cash proceeds.
Primary Health Properties’ joint venture news lands after a mixed year in the market, with the share price down 6.1% year to date, a 1-year total shareholder return of 5.1% and a 3-year total shareholder return of 31.9%, suggesting longer term holders have fared better while near term momentum has been weaker.
Compare this PHP move with other real estate trusts focused on balance sheet strength by scanning our 4 resilient stocks with low risk scores, which already screens for resilient businesses with lower risk scores.
Is this the moment to back Primary Health Properties after the GIC deal and debt paydown, or does it still look wiser to wait for a cheaper entry before the valuation work starts?
Most Popular Narrative: 20% Undervalued
Primary Health Properties last closed at £0.92, while the most followed narrative puts fair value nearer £1.15. This frames the GIC joint venture against a valuation that already assumes long, government-backed cash flows and high occupancy.
Structural barriers to entry, exemplified by near-100% occupancy, very long government-backed leases, and a pipeline of larger-scale developments in Ireland, enable PHP to maintain pricing power and achieve strong rental uplifts, particularly as market rent reviews demonstrate double-digit increases, strengthening long-term earnings visibility and recurring income.
See why 71 investors see Primary Health Properties as 20% undervalued.
Result: Fair Value of £1.15 (UNDERVALUED)
Still, Primary Health Properties relies heavily on government backed tenants and could face pressure if funding, reimbursement models or rent review assumptions shift away from current forecasts.
Find out about the key risks to this Primary Health Properties narrative.
Another View On Primary Health Properties’ Valuation
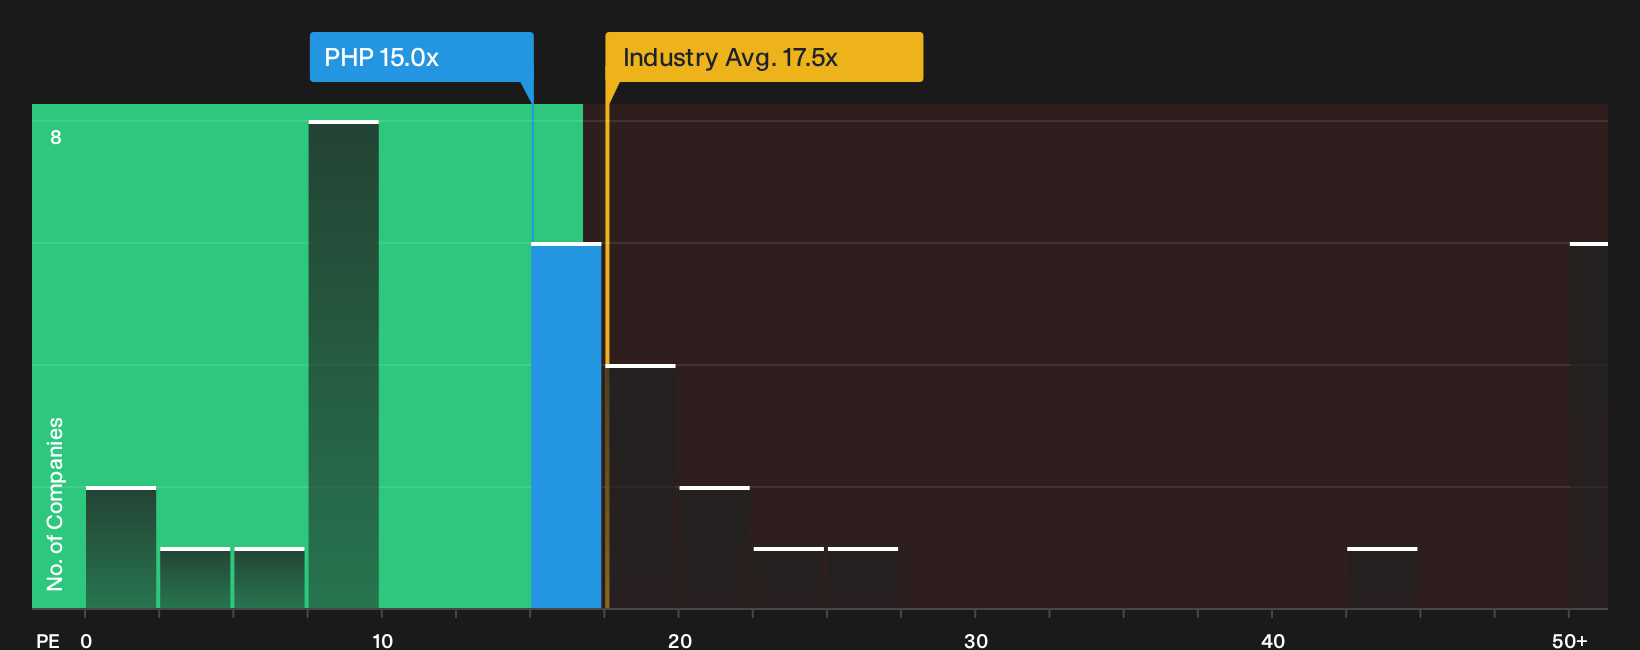
A different lens on Primary Health Properties comes from its P/E ratio. The stock trades at about 15x earnings compared with 17.1x for peers and 17.5x for the wider Health Care REITs group, yet the fair ratio is 13.7x, which implies less upside if sentiment cools.
Put simply, the current multiple suggests investors are paying a small premium to where that fair ratio sits, while still getting a discount to sector averages. The key question is whether you think future earnings quality justifies that middle ground or not.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Primary Health Properties for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by Primary Health Properties’ mix of potential and risk? If you want to move fast and rely on the underlying data instead of headlines, start with the full rundown of 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Primary Health Properties?
If Primary Health Properties has sharpened your thinking, do not stop here. Broaden your watchlist with a few targeted screens that surface very different opportunities.
- Target potential mispricing by scanning high quality companies that look undervalued on fundamentals through the 8 high quality undervalued stocks.
- Prioritise reliable cash returns by hunting for income opportunities screened as 5 dividend fortresses.
- Strengthen your defense by focusing on companies highlighted in the list of solid balance sheet and fundamentals (9 results) that can better handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com