


EN
Box (BOX) Just Drew Fresh Attention, So What Is The Market Weighing?
Why the Mark43 partnership matters for Box
Box (BOX) just deepened its reach into public safety workflows through a fresh integration with Mark43 that connects cloud content to police case files and digital evidence in a single, secure workflow.
The collaboration keeps investigative reports and supporting videos, images and documents tied together, while Mark43 remains the case system of record and Box supplies the controlled environment for storing, sharing and auditing sensitive material.
Investors have treated the Mark43 deal as part of a broader re-rating of Box, with a 30-day share price return of 37.6% helping lift the year-to-date share price return to 49.8%, while the 3-year total shareholder return of 79.4% points to momentum that has extended beyond short-term news flow.
Scan beyond Box and see which other software players are gaining traction with regulated customers through our curated list of list of solid balance sheet and fundamentals (24 results)
After a 37.6% jump in 30 days and a 49.8% gain year to date, Box now forces a simple choice: lean into the rerating today or wait and hope valuation offers a cleaner entry.
Most Popular Narrative: 12% Overvalued
Box last closed at $43.18, while the most widely followed narrative pegs fair value at $38.71. The current price sits above that estimate even after factoring in an 8.9% discount rate on future cash flows.
The current figures on growth, margins and capital returns imply a share price that may not fully reflect Box's potential benefits from higher value per customer and greater AI-driven consumption.
The analysts have a consensus price target of $38.71 for Box based on their expectations of its future earnings growth, profit margins and other risk factors.
See why 7 investors see Box as 12% overvalued.
Result: Fair Value of $38.71 (OVERVALUED)
Still, two pressure points could unravel that story if they worsen: tougher competition from bundled productivity suites and weaker pricing power on Box's higher tier plans.
Find out about the key risks to this Box narrative.
Another View On Box: Cash Flows Tell A Different Story
Price targets suggest Box is 12% overvalued at $43.18 versus a $38.71 fair value. The SWS DCF model points the other way, indicating the shares trade about 25.7% below an estimated future cash flow value of $58.08. Which lens do you trust when the signals conflict this sharply?
Look into how the SWS DCF model arrives at its fair value.
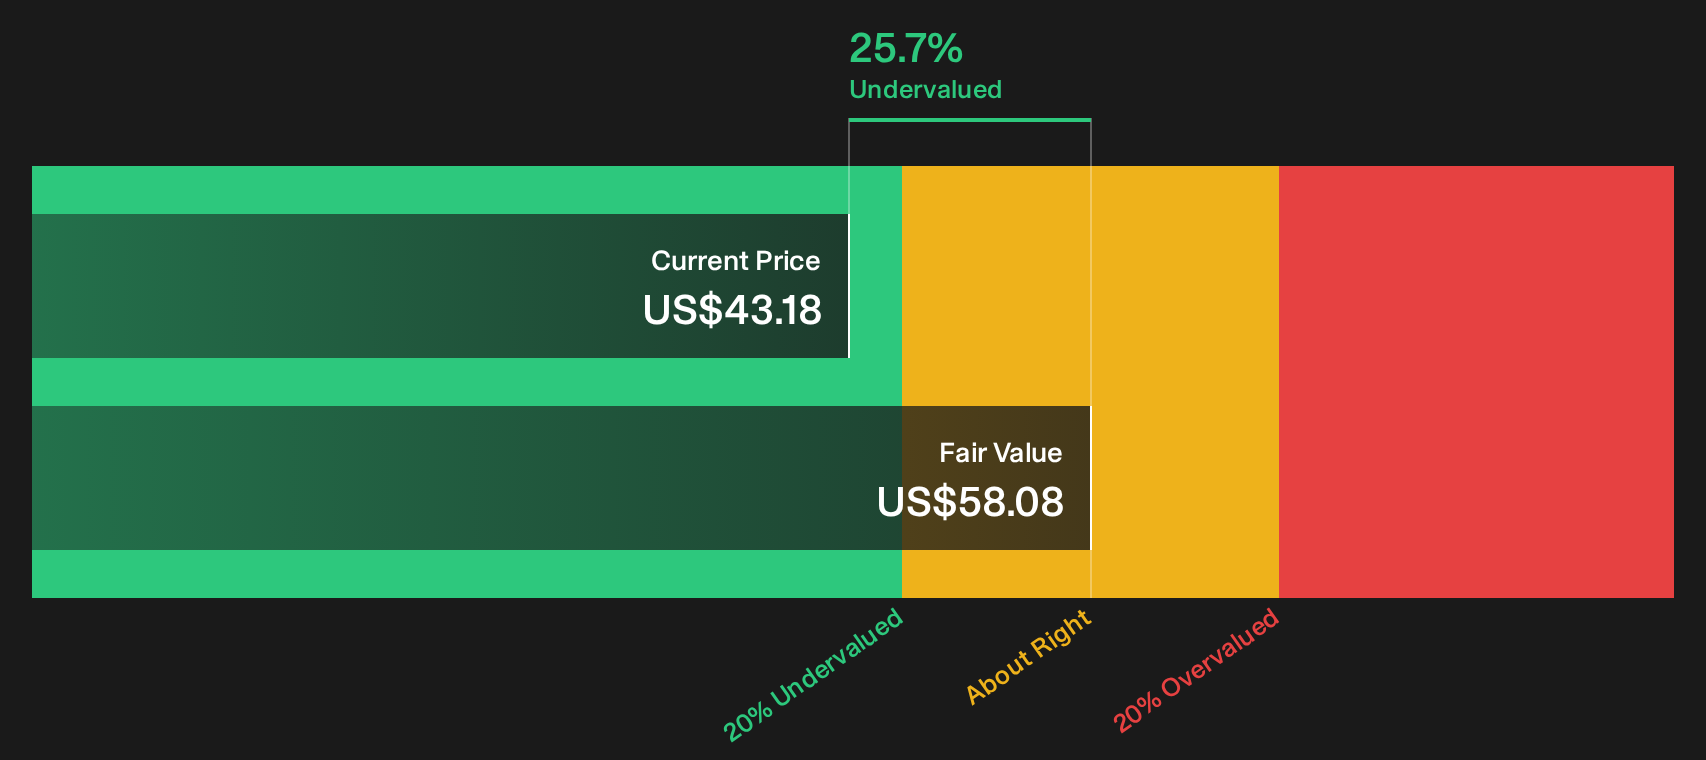
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Box for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
This mix of optimism and caution around Box only matters if you pressure test it yourself, run through the numbers and stress the arguments, then weigh the 2 key rewards and 2 important warning signs.
Looking for more Box-sized opportunities?
If Box has you rethinking what belongs in your portfolio, do not stop here. Use these focused screens to surface ideas you might otherwise overlook.
- Target resilient compounding by scanning for companies that combine durable earnings power with lower volatility using our 30 resilient stocks with low risk scores.
- Hunt for potential mispricings by filtering for quality businesses trading below estimated value with the 28 high quality undervalued stocks.
- Build a cashflow-focused watchlist by zeroing in on reliable payers through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com