


EN
Is Now a Good Time to Buy Lockheed Martin?
Key Points
Lockheed's third-quarter earnings per share hit $7.97, beating Wall Street's estimates.
A deal with the Pentagon to produce 850 F-35 jets also excited investors.
There was plenty to like about Lockheed Martin's (NYSE: LMT) earnings report on Oct. 22. The aerospace and defense manufacturer raised its full-year guidance for the second quarter in a row while beating Wall Street's third-quarter estimates. While the stock has risen more than 20% year to date as of this writing, Lockheed remains a solid buy for long-term investors.
First and foremost, Lockheed's third-quarter sales grew 11% to $20.7 billion. Earnings per share beat analysts' expectations by nearly $0.50 at $7.97. All four of Lockheed's segments grew, with the Missiles and Fire Control business having the greatest gain, increasing 14% from this quarter last year.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Lockheed's management now expects sales to top $80 billion and free cash flow of $7.8 billion to $8 billion in 2026. The free cash flow number increased by $800 million from last quarter. Lockheed also increased its dividend again, marking 24 consecutive years of increases.
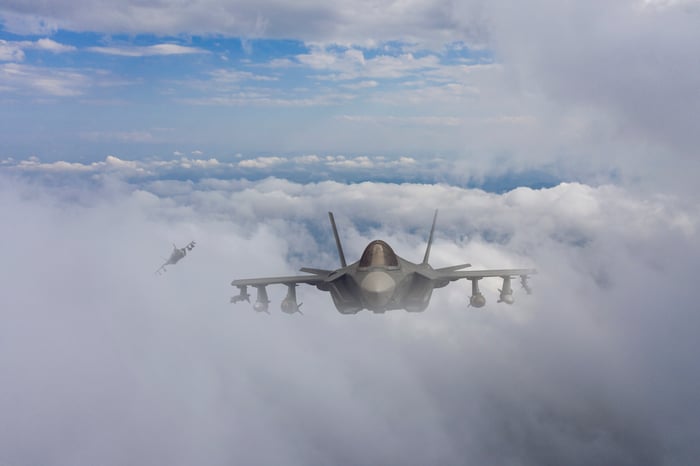
Image source: Getty Images.
The stock is really a buy because of the growth in backlog, which provides substantial revenue visibility. The backlog grew 27% to $292 billion this quarter. In particular, Lockheed signed multiyear deals for a PAC-3 interceptor and 850 F-35 jets.
Of course, Lockheed's success depends on its ability to execute efficiently and effectively, but for buy-and-hold investors, the backlog, rising guidance, and consistently growing dividend are excellent reasons to purchase the stock. Shares are still trading at a reasonable price. The company's forward and trailing price-to-earnings ratios are in the teens, and the dividend yield is respectable, currently around 2.5%.
Catie Hogan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Lockheed Martin. The Motley Fool has a disclosure policy.