


EN
Earnings Beat Might Change Universal Insurance Holdings Stock Narrative
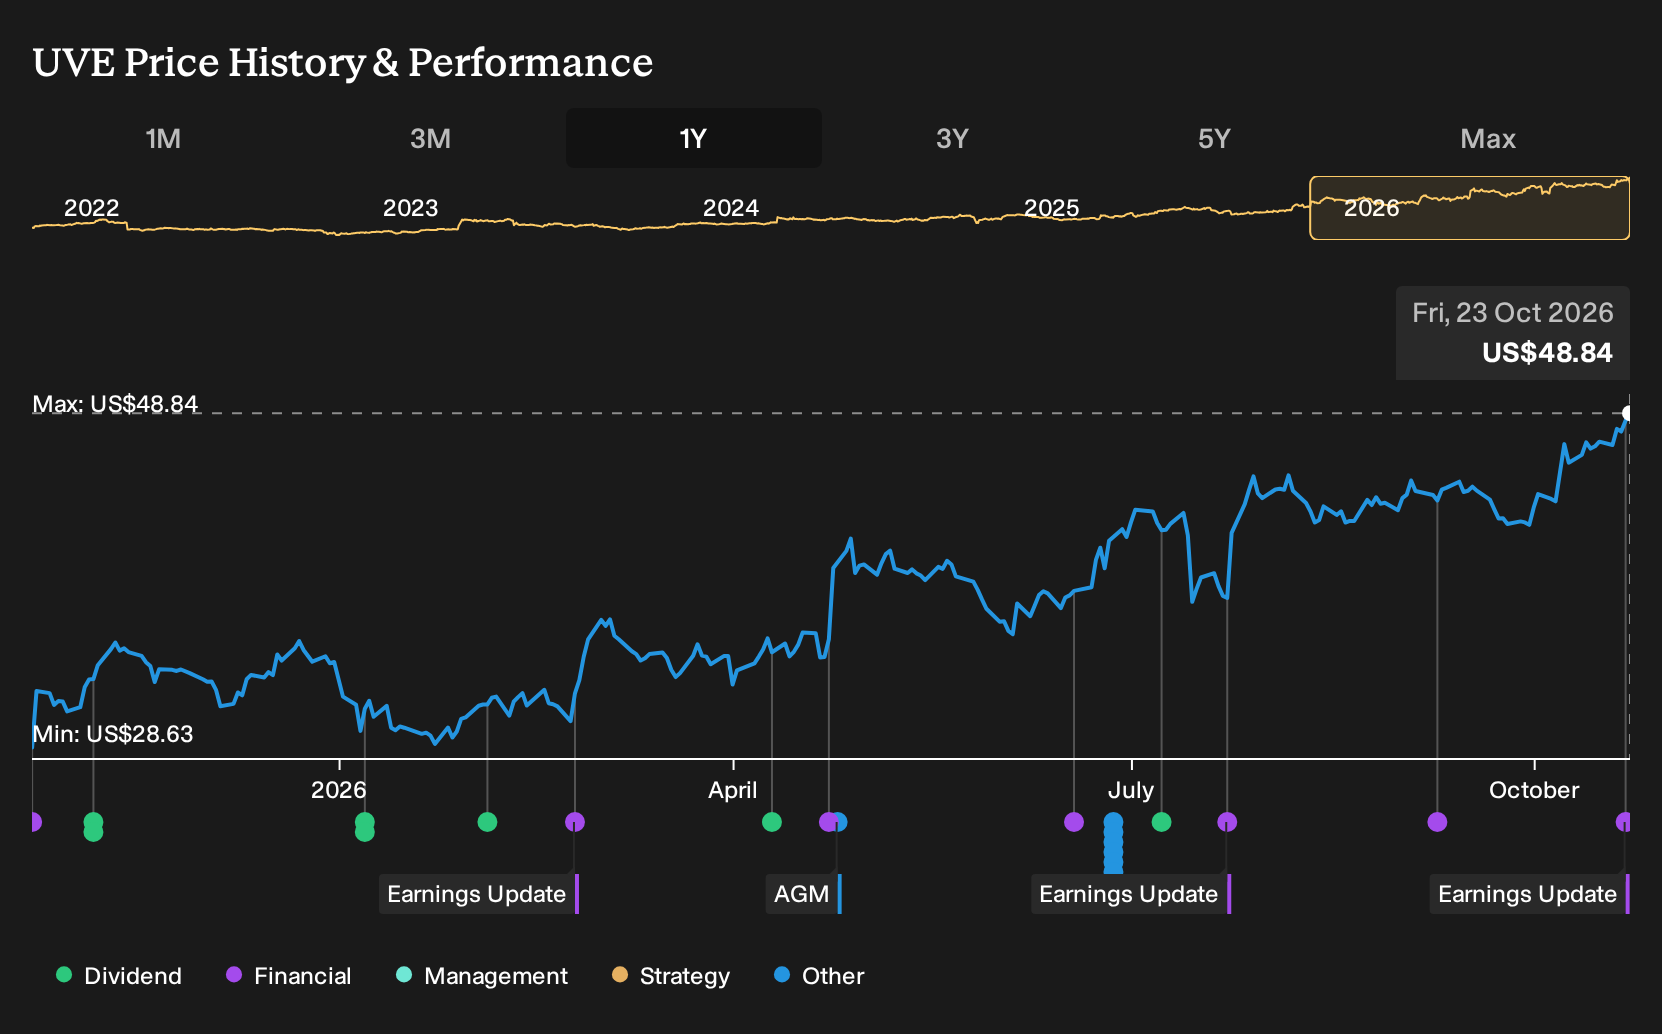
- Universal Insurance Holdings reported stronger third quarter and nine month results, with revenue of US$439.32 million and net income of US$52.51 million for the quarter, alongside continued share repurchases that completed a US$18.82 million buyback program.
- Underlying performance included higher earnings per share and policy growth across multiple states, reflecting diversification outside Florida and tighter underwriting discipline at Universal Insurance Holdings.
- We will now examine how Universal Insurance Holdings' investment narrative could be affected by this stronger earnings performance and improving return profile.
Scan how Universal Insurance Holdings' latest earnings momentum compares with other insurers by reviewing our hand picked 30 resilient stocks with low risk scores that have kept financial risk scores in check.
Universal Insurance Holdings Investment Narrative Recap
For Universal Insurance Holdings, the key belief is that disciplined underwriting, reinsurance access and geographic diversification can offset pressure in Florida and rising claims costs. The latest quarterly numbers, with higher revenue, net income and earnings per share versus a year ago, support that operating thesis in the short term.
The near term swing factor is whether underwriting profitability and reinsurance terms stay supportive through upcoming storm seasons. The biggest risk is still catastrophe exposure and inflation in claims and expenses. Recent momentum helps, but it does not remove the possibility that a single difficult event year could dent that return profile.
The clearest announcement that ties back to this story is the completed US$18.82 million share repurchase program, including US$7.4 million in buybacks during the third quarter. Universal Insurance Holdings retired roughly 1.79% of its share count through this plan.
For you as a holder or prospective investor, that matters because it tightens the share base around the current earnings power. At the same time, the business is reporting stronger profitability and a 32.7% annualized return on common equity. The buybacks sit alongside the regular US$0.16 quarterly dividend as part of the near term return catalyst set.
Universal Insurance Holdings' analyst narrative points to forecast revenue of US$1.5b and earnings of US$78.0 million by 2029, based on an assumed 1.8% yearly decline in revenue and an earnings decrease of US$117.8 million from US$195.8 million today.
Uncover why Universal Insurance Holdings' fair value indicates a 10% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Across 2 fair value estimates from the Simply Wall St Community, targets range from US$44.00 up to about US$60.87, which is a wide gap for Universal Insurance Holdings. You are seeing private investors split on upside, while underwriting pressure, Florida competition and reinsurance costs keep the operating outlook finely balanced.
Explore another Universal Insurance Holdings fair value estimate, including one that suggests up to 10% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal Insurance Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Insurance Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Universal Insurance Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Universal Insurance Holdings?
Once you have a view on Universal Insurance Holdings, it can help to widen the lens and compare it with other companies that match your risk, income, or quality preferences using the Simply Wall St Screener.
- If capital preservation is near the top of your checklist, start with a curated 30 resilient stocks with low risk scores that have kept overall risk scores relatively contained.
- Income focused investors can scan for resilient payers by reviewing a 5 dividend fortresses that pair higher yields with supporting fundamentals.
- To hunt for potential future leaders before they are widely followed, work through a 21 high quality undiscovered gems filtered for stronger quality signals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com