


EN
Reply (BIT:REY) Could Be 20% Above Fair Value As AI Launches Draw Focus
Reply’s AI Experiences Put Product Storytelling In Focus
Reply (BIT:REY) has rolled out two AI-driven offerings, Reply Immersive Experience and Symbiosis, that bring its technology into physical storytelling spaces and enterprise decision workflows, drawing fresh attention to the stock.
These launches land after a strong run in Reply’s shares, with a 30-day share price return of 9.08% and a 90-day share price gain of 31.03% lifting the stock to €130.9, while the 1-year total shareholder return of 9.43% suggests steadier long-term compounding.
Spot other AI-driven stories at a similar inflection point by scanning our hand picked 39 profitable AI stocks that aren't just burning cash that already back their ambition with real earnings power.Reply now has visible AI momentum and a share price that has moved sharply in recent months. Does a strong operating story still line up with a sensible entry point at €130.9?
Price-to-Earnings of 18.5x: Is It Justified For Reply?
Reply trades on a P/E of 18.5x at a share price of €130.9, which places the stock at a richer level than both local peers and the wider European IT group, even though its fair ratio points to more headroom than current pricing reflects.
The P/E ratio links what investors are paying today to each euro of Reply’s earnings. This matters for a consultancy and software specialist with €2.54b in revenue and €258.0m in net profit. For a business with high quality earnings and a history of profit growth, a higher multiple can indicate that the market is assigning a premium to the consistency of those profits rather than focusing only on top line expansion.
There is a tension in the numbers. Reply screens as expensive versus a peer average P/E of 11.8x and sits slightly above the 18.3x European IT industry average. However, it is assessed as good value when set against an estimated fair P/E of 32.5x that the market could move towards if confidence in its earnings durability holds.
Explore the SWS fair ratio for Reply.
Result: Price-to-Earnings of 18.5x (OVERVALUED)
Still, Reply faces real pressure if client spending on digital projects slows or if its AI platforms fail to gain traction across those core industry verticals.
Find out about the key risks to this Reply narrative.
Another View: Reply’s DCF Says The Price Runs Ahead Of Cash Flows
The P/E story paints Reply as having room to run. The SWS DCF model tells a cooler story. On that lens, the stock at €130.9 sits above an estimated future cash flow value of €108.84, which points to an overvalued signal. Which yardstick should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
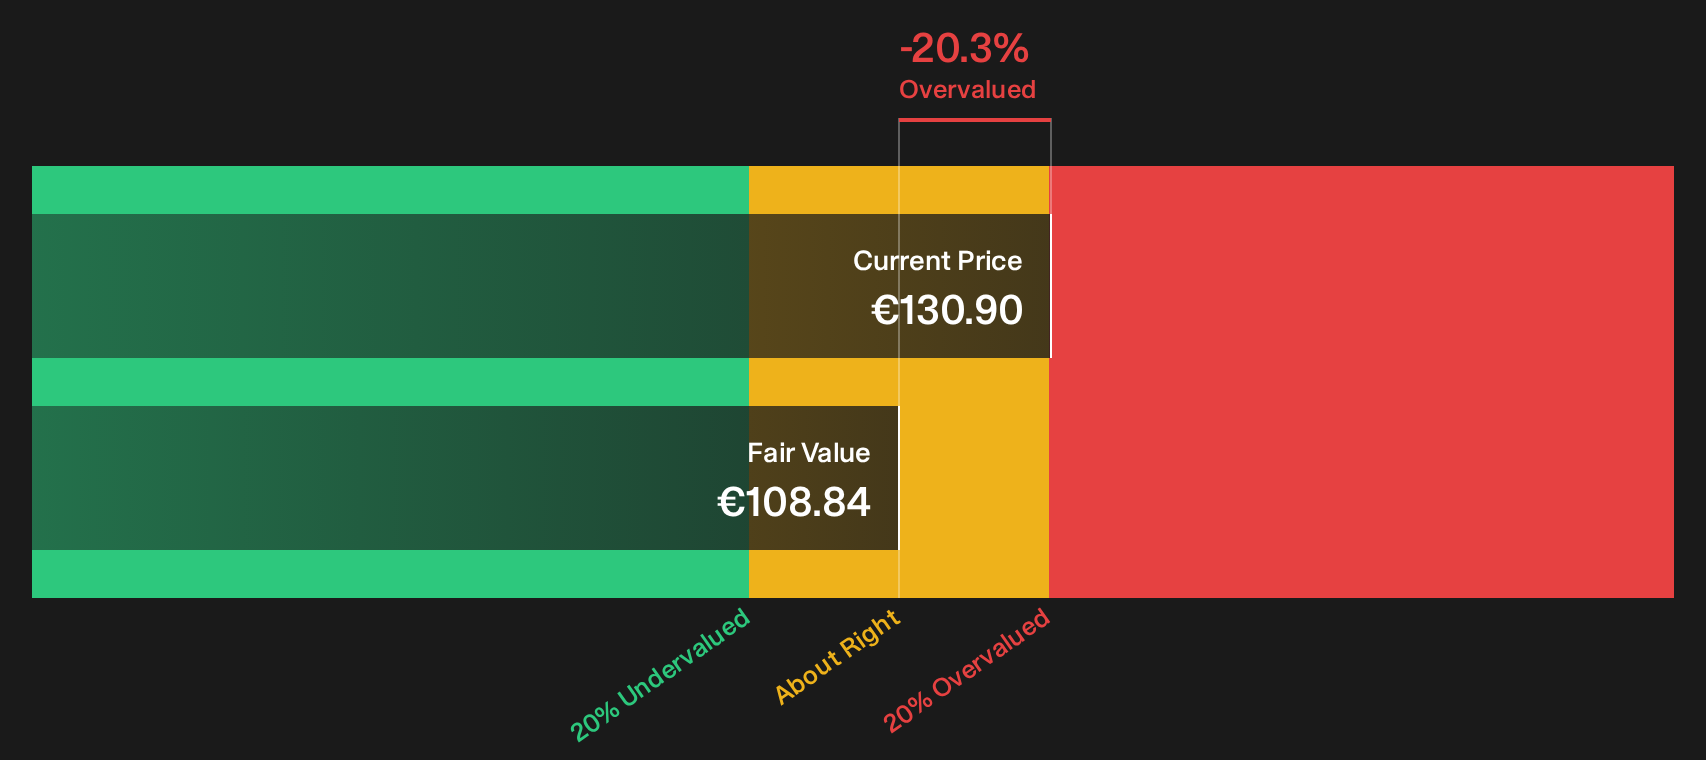
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Reply for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the optimism around Reply is deserved or overdone right now? Move quickly, review the numbers for yourself, and stress test the ideas behind those 2 key rewards
Looking For More Investment Ideas Beyond Reply?
Reply may be front of mind today, but your next worthwhile opportunity could be hiding in a very different corner of the market.
- Target resilience by scanning companies with sturdier finances through our list of solid balance sheet and fundamentals (206 results), which filters for balance sheets built to handle tougher conditions.
- Hunt for pricing gaps using the 192 high quality undervalued stocks, which surfaces stocks where fundamentals and market expectations look out of sync.
- Prioritise stability and income through the 227 dividend fortresses, featuring higher yielding payers that still clear quality and sustainability checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com