


EN
Should Slowing Organic Growth Require Action From Mettler Toledo Stock Investors?
- Mettler-Toledo International recently drew attention as slowing organic revenue growth and a weaker return on invested capital pointed to softer underlying demand and less productive new investments.
- This combination of cooling core activity and underwhelming returns on recent spending raises fresh questions about how comfortably the business supports its current rich P/E multiple.
- We will now explore how Mettler-Toledo International's investment narrative could be reshaped by slowing organic revenue growth flagged in recent updates.
Pressure test Mettler-Toledo International's rich P/E by comparing it with hand-picked alternatives screened for quality and valuation using the 27 high quality undervalued stocks list.
Mettler-Toledo International Investment Narrative Recap
Mettler-Toledo International appeals to shareholders who trust in steady demand for precision instruments, recurring service income and disciplined pricing. That story now sits next to slowing organic revenue growth and softer return on invested capital, which hint at less supportive end markets and recent spending that is not pulling its weight yet.
In the near term, the key upside driver is whether automation, bioprocessing and service activity can continue to offset weaker specialty chemical and European orders. The biggest risk is that tariffs and muted capital spending further compress organic growth, which would make the current rich P/E look harder to defend.
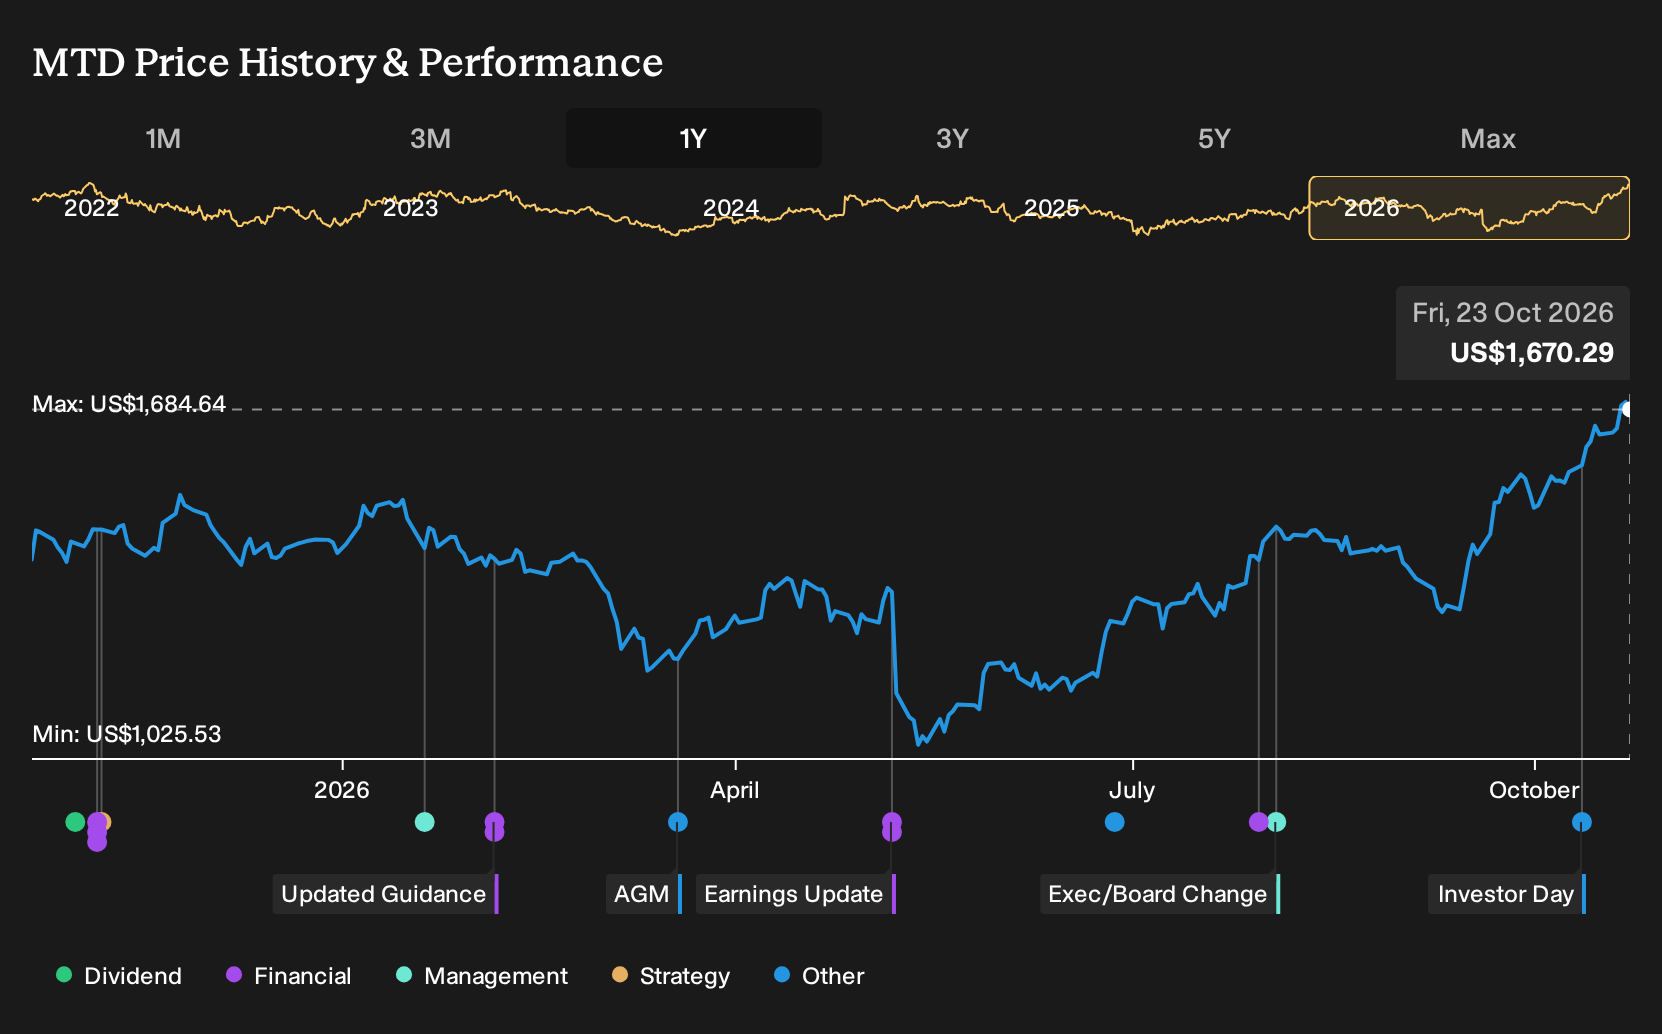
The most relevant recent development is the acknowledgement that organic growth has cooled, while earnings surprises and price momentum have kept interest in Mettler-Toledo International high ahead of the next report. That mix of softer activity and strong share performance puts more scrutiny on execution in the coming quarters.
With analysts only expecting modest revenue expansion and return on invested capital already trending lower, the earnings release around November 5, 2026 becomes an important checkpoint for your thesis. Any sign that automation projects, bioprocessing demand or the service portfolio are not offsetting tariff and debt related pressure would raise the risk that growth expectations need to be reset.
Mettler-Toledo International's current analyst script points to revenue of US$4.8b and earnings of US$1.1b by 2029, based on 4.9% yearly revenue growth and an earnings increase of about US$194.4m from US$905.6m today.
Uncover why Mettler-Toledo International's fair value indicates a 9% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster in a tight band between roughly US$1,415 and US$1,526, which contrasts with Mettler-Toledo International's rich P/E and recent earnings surprises. Those views do not yet reflect slower organic growth or tariff risk, so use them as a starting point and compare several alternative perspectives.
Explore another Mettler-Toledo International fair value estimate, including one that suggests as much as 15% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Mettler-Toledo International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mettler-Toledo International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mettler-Toledo International's overall financial health at a glance.
Looking for more Mettler-Toledo International investment ideas?
If the current setup around Mettler-Toledo International leaves you wanting a broader watchlist, use this moment to widen the lens and compare it with other opportunities filtered for quality, resilience and income potential using the Simply Wall St Screener.
- For investors who want potential upside with tighter risk controls, consider stocks filtered for resilient balance sheets and stronger fundamentals through the list of solid balance sheet and fundamentals (25 results).
- If income is a priority and you care about consistency as much as yield, review companies screened as 5 dividend fortresses to see which ones might suit a more cash focused approach.
- When you are hunting for opportunities that the broader market may be overlooking, cast a wider net across 21 high quality undiscovered gems that pair solid fundamentals with lower current visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com