


EN
Blue Bird (BLBD) Stock Still Seems Cheap After Its 210% Run
Blue Bird Corporation has delivered a powerful share price run over recent years, which raises a simple but important question for investors who own or follow Blue Bird stock: Is the current valuation fully explained by what the business is earning today and what those earnings can reasonably support?
- Over the past 3 years, Blue Bird has returned 209.7%, which puts a lot of weight on whether its earnings performance can carry that kind of rerating.
- The planned US$300 million manufacturing investment in Georgia may support future production capacity and revenue, but it also introduces a sizeable call on capital that matters for earnings-based valuation work.
- The analysts covering Blue Bird have run their own numbers. See what analysts think Blue Bird's shares could be worth.
The issue now is whether Blue Bird's current share price near US$57.73 is appropriately aligned with its earnings when judged against a Fair Ratio benchmark.
If you want a benchmark for what earnings supported reratings can look like beyond Blue Bird, line this story up next to 27 high quality undervalued stocks.
Is Blue Bird a Bargain on Earnings?
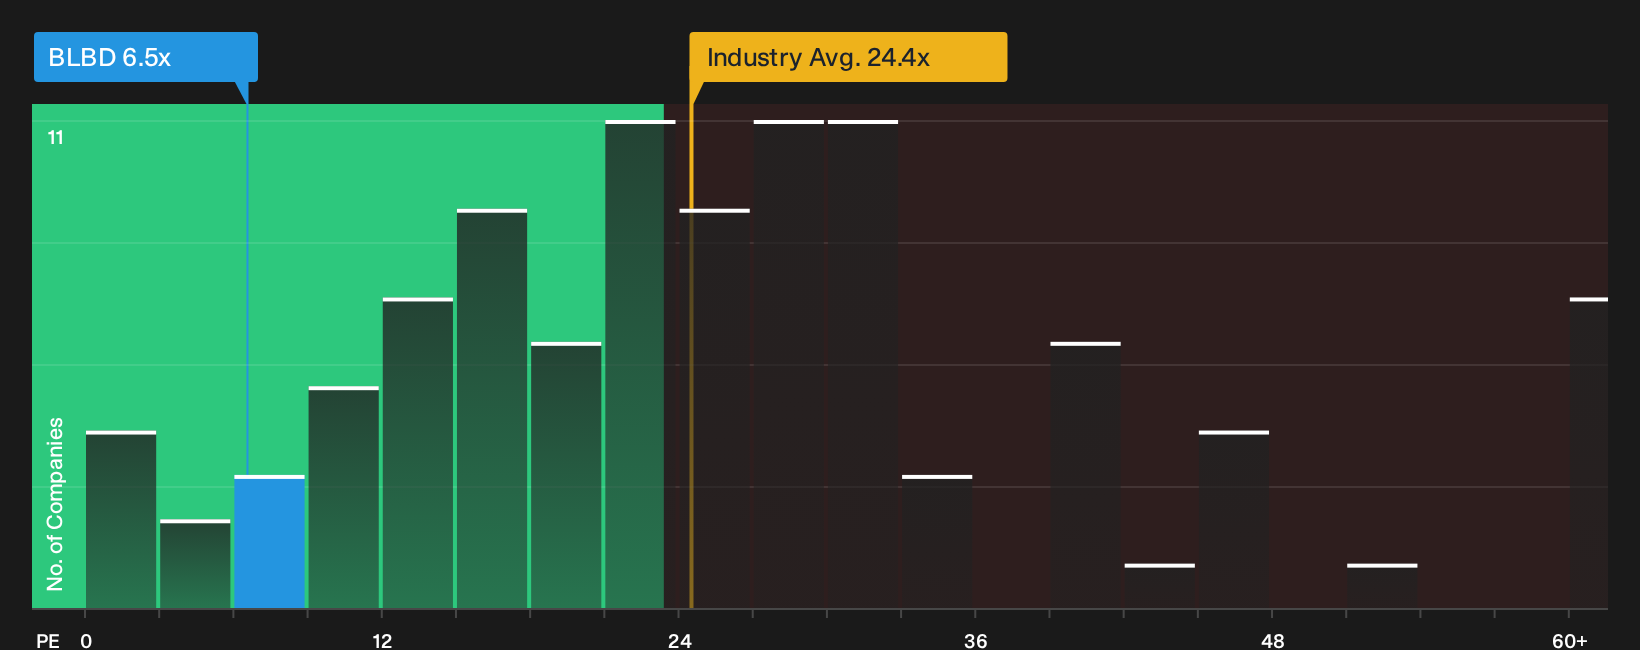
P/E works well for Blue Bird because earnings sit at the center of how investors frame this manufacturer. On that yardstick, the stock trades on a P/E of about 6.5x, which is roughly half the 12.1x peer average and far below the broader Machinery industry on about 24.4x. Against other listed rivals and the sector backdrop, the earnings multiple screens as low rather than punchy.
Because the Fair Ratio model points to a higher P/E than the current 6.5x figure, it flags Blue Bird as undervalued on this earnings lens. The planned US$300 million facility in Georgia has put more attention on the story, yet the market is still pricing the shares at a discount to what comparable businesses command on their profits. That gap leaves you weighing how durable current earnings are, and how much of the expansion risk is already baked into the multiple. Explore the numbers behind Blue Bird's P/E valuation.
The Blue Bird Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle for Blue Bird leaves off. They spell out which paths for revenue, profitability and earnings would need to hold for the stock to justify a meaningfully higher or lower price than today. Each one links its number to a clear view on how growth, margins and risk could evolve, giving you something concrete to track as new information on Blue Bird's business comes through.
One of the top community narratives on Blue Bird: 35% undervalued
"The build out of a broader specialty vehicle and chassis platform, including full Micro Bird consolidation and new shuttle and Class 5 to 6 chassis programs…"
Discover why this Narrative puts Blue Bird at 35% undervalued.
Blue Bird's valuation still hinges on one unresolved question
Numbers tell only part of the Blue Bird story, because the people directing capital and the way their rewards are structured can heavily influence where this business goes next. See who runs Blue Bird and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com