


EN
Why TTM Technologies (TTMI) Is Up 8.4% And What's Next
- TTM Technologies reported third quarter 2026 sales of US$1,203.86 million and net income of US$84.8 million, and issued fourth quarter and full year 2026 revenue guidance alongside a preliminary 2027 sales outlook.
- The business is committing a further US$400 million to expand advanced N+M capacity in China and Penang to support AI driven infrastructure demand, while providing a 2027 net sales forecast in the range of US$6.5 billion to US$6.75 billion.
- Next, the focus will be on how TTM Technologies' record earnings and sizeable AI focused expansion plans may influence its broader investment narrative.
TTM Technologies Investment Narrative Recap
To own TTM Technologies, you need to believe its heavy exposure to AI infrastructure and defense can absorb higher capex and debt without squeezing returns. The latest quarter shows the business producing higher sales and earnings alongside that investment, while the 2026 and preliminary 2027 net sales forecasts frame a clear growth agenda that management is committing to execute.
The key near term swing factor is how quickly new AI focused capacity fills and whether margins hold as volumes scale. The biggest risk remains capital intensity and leverage. If demand or cash generation slows, that combination could pressure flexibility more than the latest guidance shift itself.
The most relevant update for this story is the US$400 million expansion plan across China and Penang tied to advanced N+M capacity. That rollout connects directly to the Q4 2026 and 2027 net sales frameworks because meaningful AI infrastructure orders would need to flow through those facilities to support the higher revenue ranges that TTM Technologies has outlined.
This build out also sharpens the trade off investors are weighing. On one side is faster AI led growth and expanded engineered solutions capacity. On the other side is the risk of underutilized assets and higher borrowing costs. Execution on timing, yields and customer loading into these factories will likely drive how quickly the Q3 earnings strength translates into more durable cash flow.
TTM Technologies' current analyst blueprint ties revenue of US$7.9b and earnings of US$1.2b to 2029. That path assumes 32.7% yearly top line growth and an earnings increase of about US$963.2m from US$236.8m today.
Uncover why TTM Technologies' fair value indicates a 163% potential upside to its current price that may not last much longer.
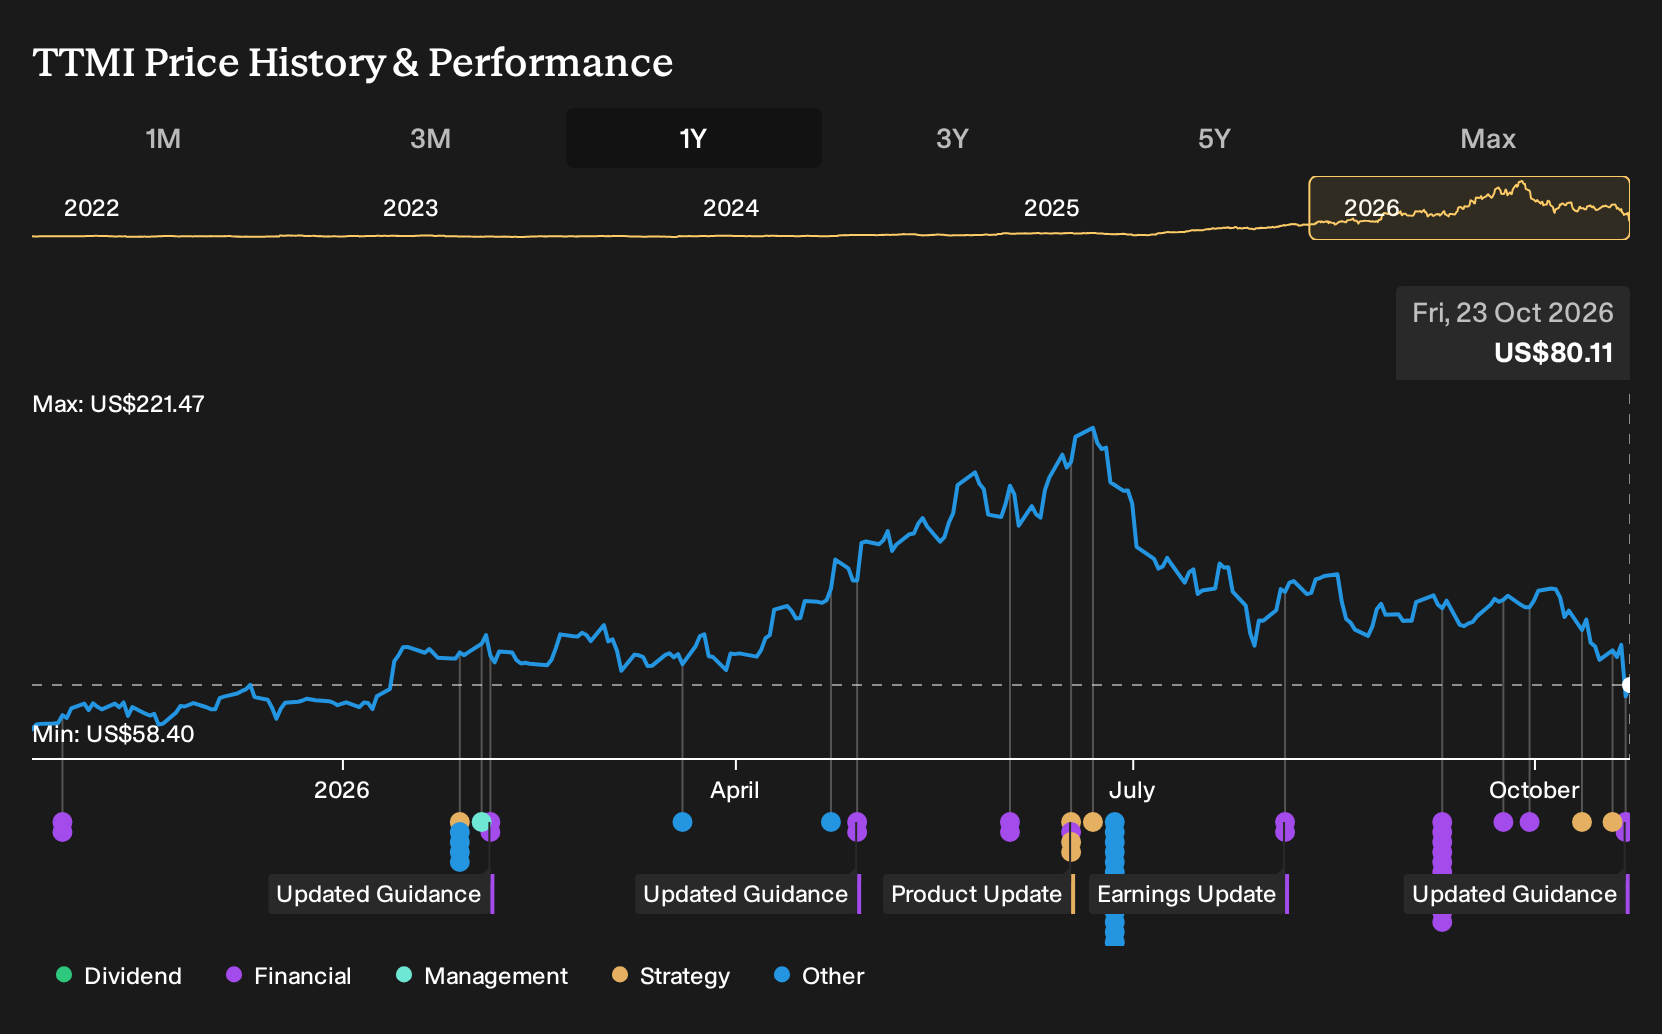
Exploring Other Perspectives
One alternate angle on TTM Technologies focuses on customer and end market concentration as the key risk. The lowest analysts were already cautious, penciling in about US$9.1b of 2029 revenue and US$1.3b of earnings before this US$6.5b to US$6.75b 2027 guidance, so their narrative may shift if defense or AI ordering patterns change. You can treat this spread in expectations as a reminder to compare several viewpoints rather than rely on a single story.
Explore 4 other TTM Technologies fair value estimates, including one that suggests it could be worth just $150.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TTM Technologies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TTM Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TTM Technologies' overall financial health at a glance.
Looking for more investment ideas beyond TTM Technologies?
If the TTM Technologies story has sharpened your thinking, use that same lens to scan a broader opportunity set. The Simply Wall St Screener can help you quickly filter for companies that better match your risk appetite, income needs, or balance sheet comfort level.
- For investors who want potential mispricing with quality behind it, start with a focused shortlist of 27 high quality undervalued stocks that may warrant a closer look.
- If resilience matters most to you, narrow the field to a 30 resilient stocks with low risk scores that score well on stability and downside protection.
- For those who care deeply about financial strength, zero in on a list of solid balance sheet and fundamentals (25 results) and use it as a foundation for further research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com