


EN
China National Building Material (SEHK:3323) Faces A Big Fair Value Gap As Losses Land
China National Building Material (SEHK:3323) reported a net loss of CNY 728.3 million for the nine months to September 30, 2026, on sales of CNY 129.99b, following today’s earnings announcement.
China National Building Material's latest earnings setback lands on a weak price chart, with the share price falling about 44% year to date and the 1 year total shareholder return declining roughly 47%. This signals fading momentum as investors reassess the higher perceived risk around the shift to a loss.
Capitalize on the pressure China National Building Material is under by reviewing hand picked building and materials peers with stronger balance sheets and cash flows in our list of solid balance sheet and fundamentals (206 results).After a slide like this, China National Building Material either offers meaningful upside from a beaten down base, or most of the easy rebound has already played out. The valuation section examines which scenario this currently appears closer to.
Preferred Multiple of 0.1x P/S: Is it justified?
China National Building Material last closed at HK$2.90, and on a P/S ratio of 0.1x the shares are pricing in far lower sales value than both peers and internal estimates suggest. For investors tracking valuation resets after big drawdowns, that gap on revenue multiples is the core question.
The price to sales ratio compares the company’s market value to its annual revenue. For a diversified building materials group like China National Building Material, with cement, new materials and engineering services all contributing, sales based metrics are often used when earnings are distorted by losses or heavy investment.
On this measure the stock is trading at what looks like a deep discount. Management is currently unprofitable and interest payments are not well covered. Yet the P/S ratio of 0.1x is far below the Asian Basic Materials industry average of 1x and the peer average of 7.5x. Our fair price to sales ratio estimate is 0.5x, a level the market could move towards if sentiment around profitability and balance sheet risk improves.
Explore the SWS fair ratio for China National Building Material.
Result: Price-to-Sales of 0.1x (UNDERVALUED)
Still, the ongoing net loss and weak interest coverage mean any setback in funding conditions or construction demand could quickly undercut the China National Building Material rebound story.
Find out about the key risks to this China National Building Material narrative.
Another view on China National Building Material's value
Revenue based metrics paint one picture for China National Building Material, but the SWS DCF model pushes it much further. At HK$2.90, the stock is compared with an estimated future cash flow value of HK$37.40, which points to a very large valuation gap. Is that a rare bargain or a sign that the DCF is assuming too much improvement in cash generation?
Look into how the SWS DCF model arrives at its fair value.
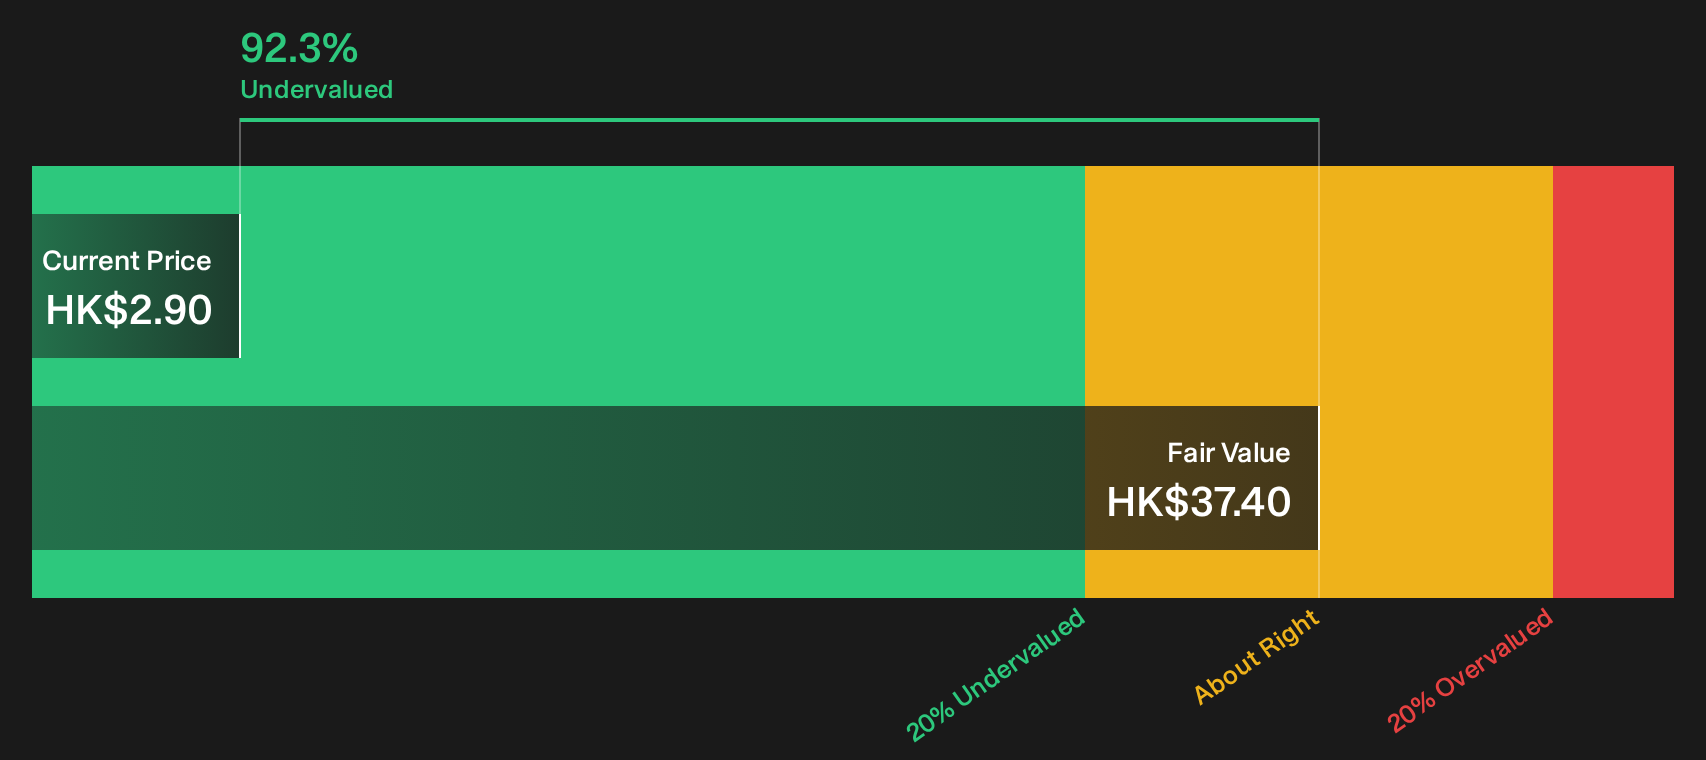
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China National Building Material for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around China National Building Material can feel confusing, so move quickly, look through the numbers yourself and decide what holds up in your own framework by weighing the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond China National Building Material?
Do not leave your watchlist anchored to one difficult story when a wider set of opportunities is only a quick screen away.
- Target potential mispricings by scanning a curated set of value ideas through the 192 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that feature robust payout profiles inside the 227 dividend fortresses.
- Dial down portfolio stress by focusing on businesses flagged for resilience using the 221 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com