


EN
Apple Hospitality REIT (APLE) Gets A Zacks Lift, Is It Fully Priced?
Apple Hospitality REIT (APLE) just caught fresh attention after Zacks lifted the stock to a Rank #2 rating, reflecting stronger earnings estimates and growing analyst confidence in the hotel focused real estate investment trust.
Recent price action has been punchy, with a 13.96% 1 month share price return and a 49.59% year to date share price gain at a last close of US$18.04. The 66.01% 1 year total shareholder return points to strong momentum that recent earnings optimism and the affirmed monthly dividend are helping to reinforce.
Spot 27 high quality undervalued stocks that share Apple Hospitality REIT’s mix of earnings momentum, analyst upgrades, and value credentials.Apple Hospitality REIT now trades just above the average analyst target, yet screens on some models as materially undervalued. After this kind of run, where does a sensible view of fair value land in that spread?
Most Popular Narrative: 5% Overvalued
Compared with the Simply Wall St narrative fair value of about $17.17, Apple Hospitality REIT’s $18.04 close prices in a premium that recent momentum and earnings expectations need to justify.
The current valuation, along with evidence of resilient RevPAR, margin expansion, regular monthly cash distributions near a mid single digit yield and improving external views on Apple Hospitality REIT’s earnings outlook, suggests the share price already reflects a fairly valued, bullish narrative that assumes continued execution rather than a deep discount.
See why 49 investors see Apple Hospitality REIT as 5% overvalued.
Result: Fair Value of $17.17 (OVERVALUED)
Still, that upbeat Apple Hospitality REIT story can fray if renovation disruption at key hotels hits RevPAR harder than expected, or if softer markets like Phoenix drag portfolio level earnings.
Find out about the key risks to this Apple Hospitality REIT narrative.
Another View: Our DCF Model Flips The Story
A different lens on Apple Hospitality REIT uses the Simply Wall St DCF model, which estimates fair value at about $39.58 per share. In comparison with the current $18.04 price, that suggests the stock could be significantly undervalued rather than 5% rich. Which narrative do you think fits the risks and cash flows better?
Look into how the SWS DCF model arrives at its fair value.
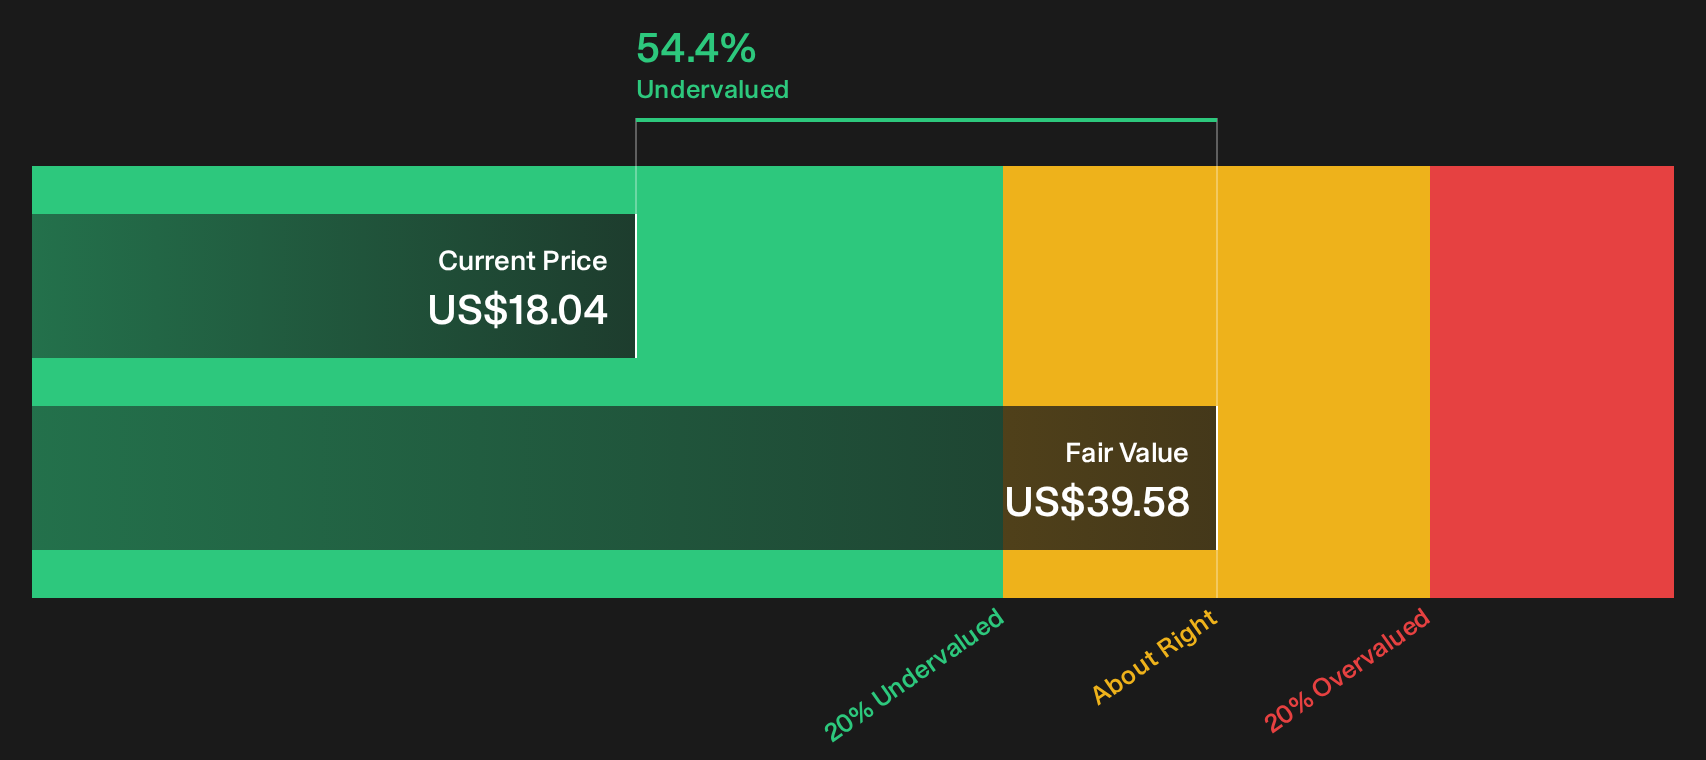
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Apple Hospitality REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed on the story so far or just curious where you land on Apple Hospitality REIT? Move fast and test the bullish and cautious angles against 2 key rewards and 2 important warning signs
Looking for more Apple Hospitality REIT style ideas?
Do not stop with Apple Hospitality REIT. Put this research to work and line up a few more candidates that match the kind of profile you want next.
- Target income resilience by focusing on businesses built around reliable cash flows and healthy balance sheets through a list of solid balance sheet and fundamentals (25 results).
- Hunt for value by scanning companies that pair quality fundamentals with prices that still look reasonable using a 27 high quality undervalued stocks.
- Spot potential early stage opportunities before they get crowded and use a 7 elite penny stocks with strong financials to narrow the field to financially stronger candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com