


EN
Iron Mountain (IRM), What Is Driving Fresh Attention Now?
Iron Mountain (IRM) heads into its November 5 Q3 earnings release with analyst forecasts calling for a clear jump in diluted EPS compared with last year, which puts the spotlight on its expanding digital services and new customer partnerships.
Recent momentum around Iron Mountain has cooled, with the share price down 14.3% over the past 90 days. However, the year-to-date share price return of 32.1% and a 5-year total shareholder return of 191.15% still point to a strong longer-term run that frames current earnings expectations against a rich recent history for holders.
Scan beyond Iron Mountain and line up other asset heavy compounders using the hand picked list of solid balance sheet and fundamentals (25 results) to help shape returns through steadier cash flows and more resilient finances.
The pullback in Iron Mountain after a strong multiyear run could be read as a reality check on fundamentals or simply a reset in enthusiasm. The valuation now needs to do the talking.
Most Popular Narrative: 24% Undervalued
Iron Mountain's most followed narrative pegs fair value at about $144.91 using an 8.4% discount rate, compared with the latest $109.96 close. This frames current expectations for its data center and digital push as key to the investment case.
Robust hyperscale data center demand, including 110 megawatts of leases signed year to date and 325 megawatts of capacity scheduled to energize over the next 18 to 24 months with over 90% of leasing historically to major cloud providers on 10 to 15 year contracts, supports the view that Iron Mountain can grow high visibility recurring revenue and contribute to future AFFO growth.
See why 49 investors see Iron Mountain as 24% undervalued.
Result: Fair Value of $144.91 (UNDERVALUED)
Still, the Iron Mountain narrative can be knocked off course if physical records storage weakens faster than expected, or if large data center build outs face meaningful delays and cost pressure.
Find out about the key risks to this Iron Mountain narrative.
Another View On Iron Mountain's Valuation
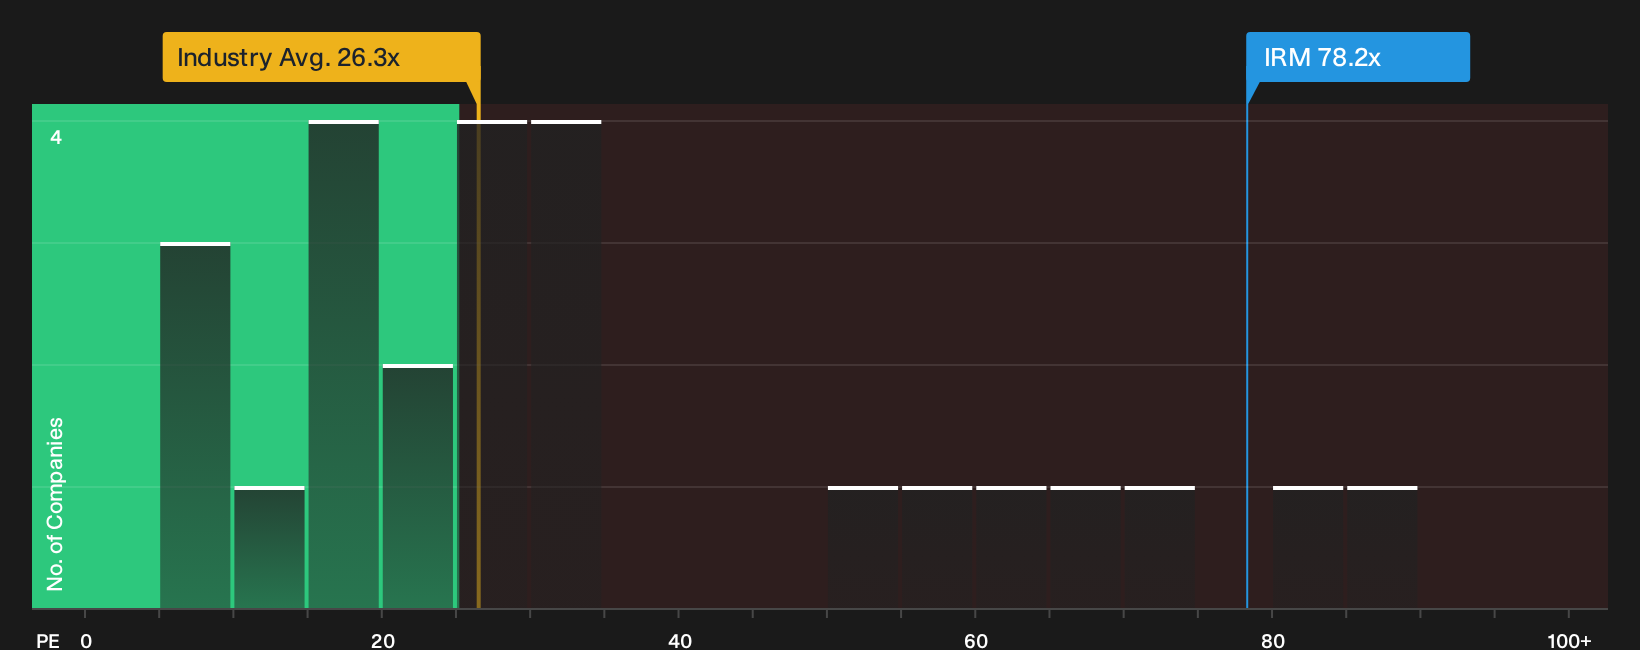
On price multiples, Iron Mountain looks expensive. It trades on a P/E of 78.2x compared with 25.7x for the North American Specialized REITs group and 18.1x for peers, while the fair ratio sits at 41.9x. That gap points to real valuation risk if sentiment cools.
To see how those rich earnings multiples stack up against cash flow expectations, and where the market could shift closer to the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Iron Mountain story today. If you want to move quickly and decide where you land on it, weigh up the 4 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Iron Mountain?
If Iron Mountain has sharpened your thinking, do not stop here. Use the Simply Wall St screener to surface fresh opportunities that fit your style.
- Target stronger potential value by scanning companies that pair dependable balance sheets with appealing prices using the 27 high quality undervalued stocks.
- Secure income focused opportunities by lining up reliable payers through the 5 dividend fortresses before the next wave of investors catches on.
- Zero in on lower risk candidates with steadier fundamentals by running the 30 resilient stocks with low risk scores and avoid leaving sturdier options unnoticed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com