


EN
Rhythm Pharmaceuticals (RYTM) Launched IMCIVREE In Japan, Is It Still A Bargain?
Why Rhythm Pharmaceuticals Stock Is Back In Focus
Rhythm Pharmaceuticals (RYTM) has moved back onto investor watchlists after launching IMCIVREE in Japan for acquired hypothalamic obesity, following inclusion on the National Health Insurance drug price list.
The therapy is the first approved treatment in Japan for this condition. Rhythm estimates it affects roughly 5,000 to 8,000 people in the country, so the new launch creates a defined, reimbursed patient pool in a rare disease segment.
Recent trading tells a mixed story. The share price has slipped about 15% year to date and is down roughly 13% over the past 90 days, yet Rhythm Pharmaceuticals still carries a very large 5 year total shareholder return. This shows how strong earlier momentum has cooled recently.
Spot similar rare-disease opportunities by scanning our handpicked 21 high quality undiscovered gems, which pair niche therapies with strong underlying fundamentals.Recent performance for Rhythm Pharmaceuticals can be read two ways: as cooling enthusiasm after years of strong shareholder gains, or as a mismatch between sentiment and a rare-disease platform still expanding. Which story do the current valuation markers support?
Most Popular Narrative: 33% Undervalued
Rhythm Pharmaceuticals last closed at $89.27, while the most followed narrative on the stock pins fair value closer to $134. That gap frames IMCIVREE as more than a single-asset story and puts meaningful weight on how the rare obesity franchise could broaden from here.
Rhythm Pharmaceuticals is a high-growth commercial-stage company targeting orphan neuroendocrine disorders linked to MC4R pathway dysfunction (genetic obesity). Having expanded from one disorder to multiple approved indications, the company has additional opportunities ahead to expand its portfolio. I rate RYTM a BUY, driven by expected double-digit revenue growth, a broader targeted-obesity portfolio, and stronger-than-expected patient uptake.
See why 5 investors see Rhythm Pharmaceuticals as 33% undervalued.
According to peter_4mgsy, that fair value of $134 implies Rhythm Pharmaceuticals trades at a 33.4% discount to the story laid out in the narrative, even after a long multi year run for existing shareholders. The thesis leans heavily on forecast revenue growth of 39.2% per year and earnings growth of 69.44% per year, along with analysts expecting the business to move into profitability within three years.
Analyst targets point in the same direction. The average price target of $140.53 sits well above the current share price, and the data shows analysts are in relatively tight agreement on that outlook. That alignment with the narrative fair value helps explain why the SWS DCF model also flags RYTM as trading 81.3% below its estimated future cash flow value of $476.95.
None of this removes risk. Rhythm Pharmaceuticals is still loss making with a reported net loss of $210.22m and a very low historical return on equity. The rare disease focus, the forecast revenue ramp, and the expected shift to profitability are doing the heavy lifting in these valuation frameworks, so readers should weigh whether those assumptions fit their own risk tolerance and time horizon.
Result: Fair Value of $134 (UNDERVALUED)
Still, Rhythm Pharmaceuticals faces real pressure if IMCIVREE uptake slows or if clinical trial setbacks weaken confidence in the broader MC4R pipeline.
Find out about the key risks to this Rhythm Pharmaceuticals narrative.
Another View: Rhythm Pharmaceuticals Looks Expensive On Sales
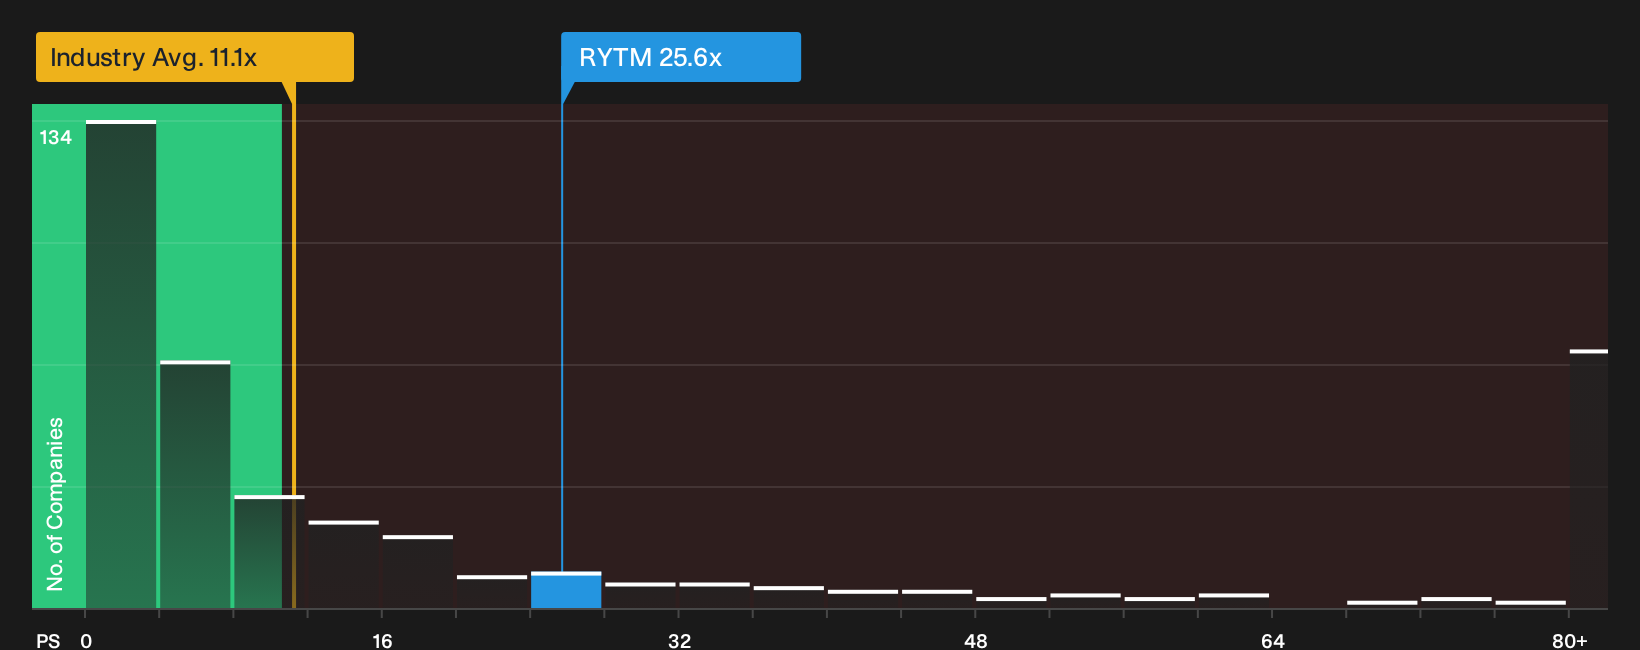
Flip the lens and the picture changes. On a P/S of 25.6x, Rhythm Pharmaceuticals trades well above the US Biotechs industry at 11.4x and above its own fair ratio of 16.6x. That rich revenue multiple suggests less margin for error if forecasts or sentiment cool.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Rhythm Pharmaceuticals feels familiar, move quickly from reading to checking the numbers yourself and pressure testing every assumption. Then ground that view in the 3 key rewards.
Looking for more investment ideas beyond Rhythm Pharmaceuticals?
Rhythm Pharmaceuticals might be your starting point, but your edge comes from lining up a whole bench of strong contenders across different styles of opportunity.
- Prioritise quality at a discount by hunting for companies that combine strong fundamentals with attractive valuations through our 27 high quality undervalued stocks.
- Protect your downside by targeting businesses with sturdier finances using the list of solid balance sheet and fundamentals (25 results) to filter for balance sheets that can better handle shocks.
- Stay ahead of the crowd by scanning the 30 resilient stocks with low risk scores for resilient opportunities that score well on risk without giving up on potential upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com