


EN
GXO Logistics (GXO) Could Be 9% Overvalued After Action Warehouse Expansion
GXO Logistics (GXO) expanded its work with discount retailer Action by taking on a new 80,000 square meter distribution center in Onnaing, France, which serves stores across France and Belgium.
For context, GXO Logistics shares trade at US$48.43, with a 1 month share price return of 7.07% after a softer 1 day move that slipped 0.98%. However, the 1 year total shareholder return is still down 11.41% and the 5 year total shareholder return has fallen 45.46%. This suggests that near term momentum has picked up following a tougher multi year stretch, as investors reassess growth projects like the new Action distribution center in relation to past performance and perceived risk.
Spot opportunities across logistics and supply chain specialists by scanning our hand picked 95 robotics and automation stocks, which could benefit from similar warehouse automation and fulfillment trends.Bulls see GXO Logistics using projects like Onnaing to support its revenue and earnings growth, while bears point to the long slide in shareholder returns. Which story does the current valuation support next?
Most Popular Narrative: 9% Overvalued
GXO Logistics last closed at $48.43, while the most followed narrative fair value of $44.27 implies the shares are pricing in more optimism than that framework supports. This puts extra weight on how confidently you view the underlying cash flow story.
"That enormous range is not proof that GXO is undervalued. It is proof that a relatively small change in assumed cash conversion can produce a radically different equity value when meaningful debt sits ahead of common shareholders. The robots make the story more exciting. The leverage makes the assumptions less forgiving."
See why 1 investors see GXO Logistics as 9% overvalued.
Result: Fair Value of $44.27 (OVERVALUED)
Still, the GXO Logistics story could change quickly if free cash flow once again misses guidance, or if Wincanton integration costs hit cash conversion.
Find out about the key risks to this GXO Logistics narrative.
Another View: SWS DCF Puts GXO Logistics In A Different Bucket
The earlier fair value of $44.27 presented GXO Logistics as roughly 9% overvalued. Our DCF model arrives at a different result, with a future cash flow value of $100.10, which indicates that the current $48.43 price could be well below that framework. Which perspective appears more convincing to you: the cautious cash conversion lens, or the longer runway that the DCF is reflecting?
Investors who want to see how those assumptions are built line by line can Look into how the SWS DCF model arrives at its fair value.
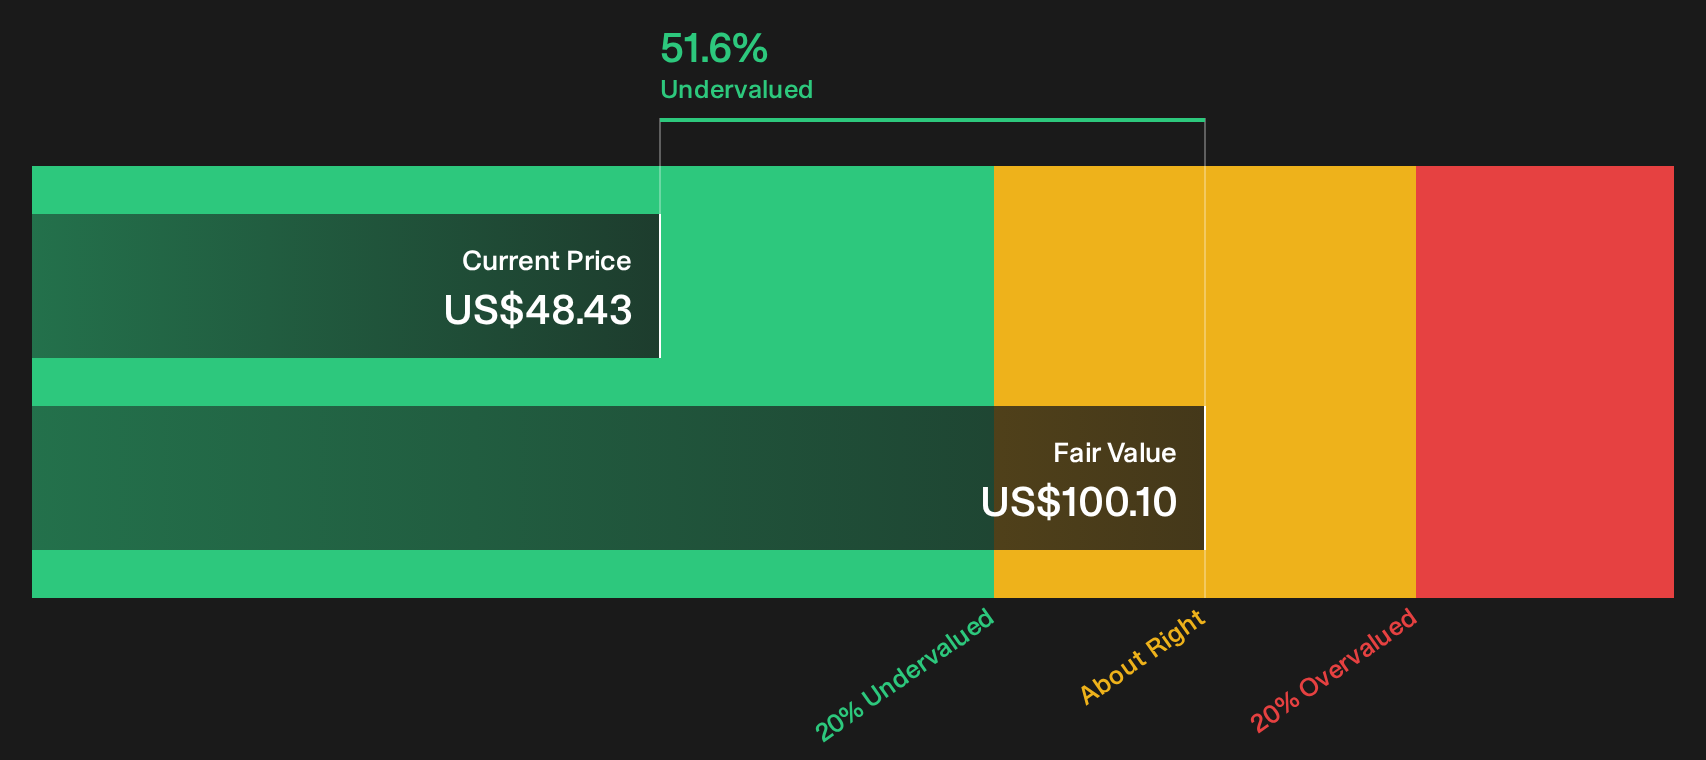
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out GXO Logistics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on GXO Logistics so far. If you want a clear personal stance, review the full data set, including the 4 key rewards and 2 important warning signs.
Looking for more GXO Logistics sized investment ideas?
If GXO Logistics has sharpened your thinking, do not stop here. Broader context from other companies can help you spot patterns and gaps in your portfolio.
- Target resilient compounders that combine quality with a potential margin of safety by scanning our hand picked 27 high quality undervalued stocks.
- Secure more dependable income streams by reviewing companies in the 5 dividend fortresses that pair higher yields with sturdier payout profiles.
- Limit unpleasant surprises by focusing on financially robust operators using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com