


EN
Why AIXTRON Doubters Were Wrong Before A 115% Gain
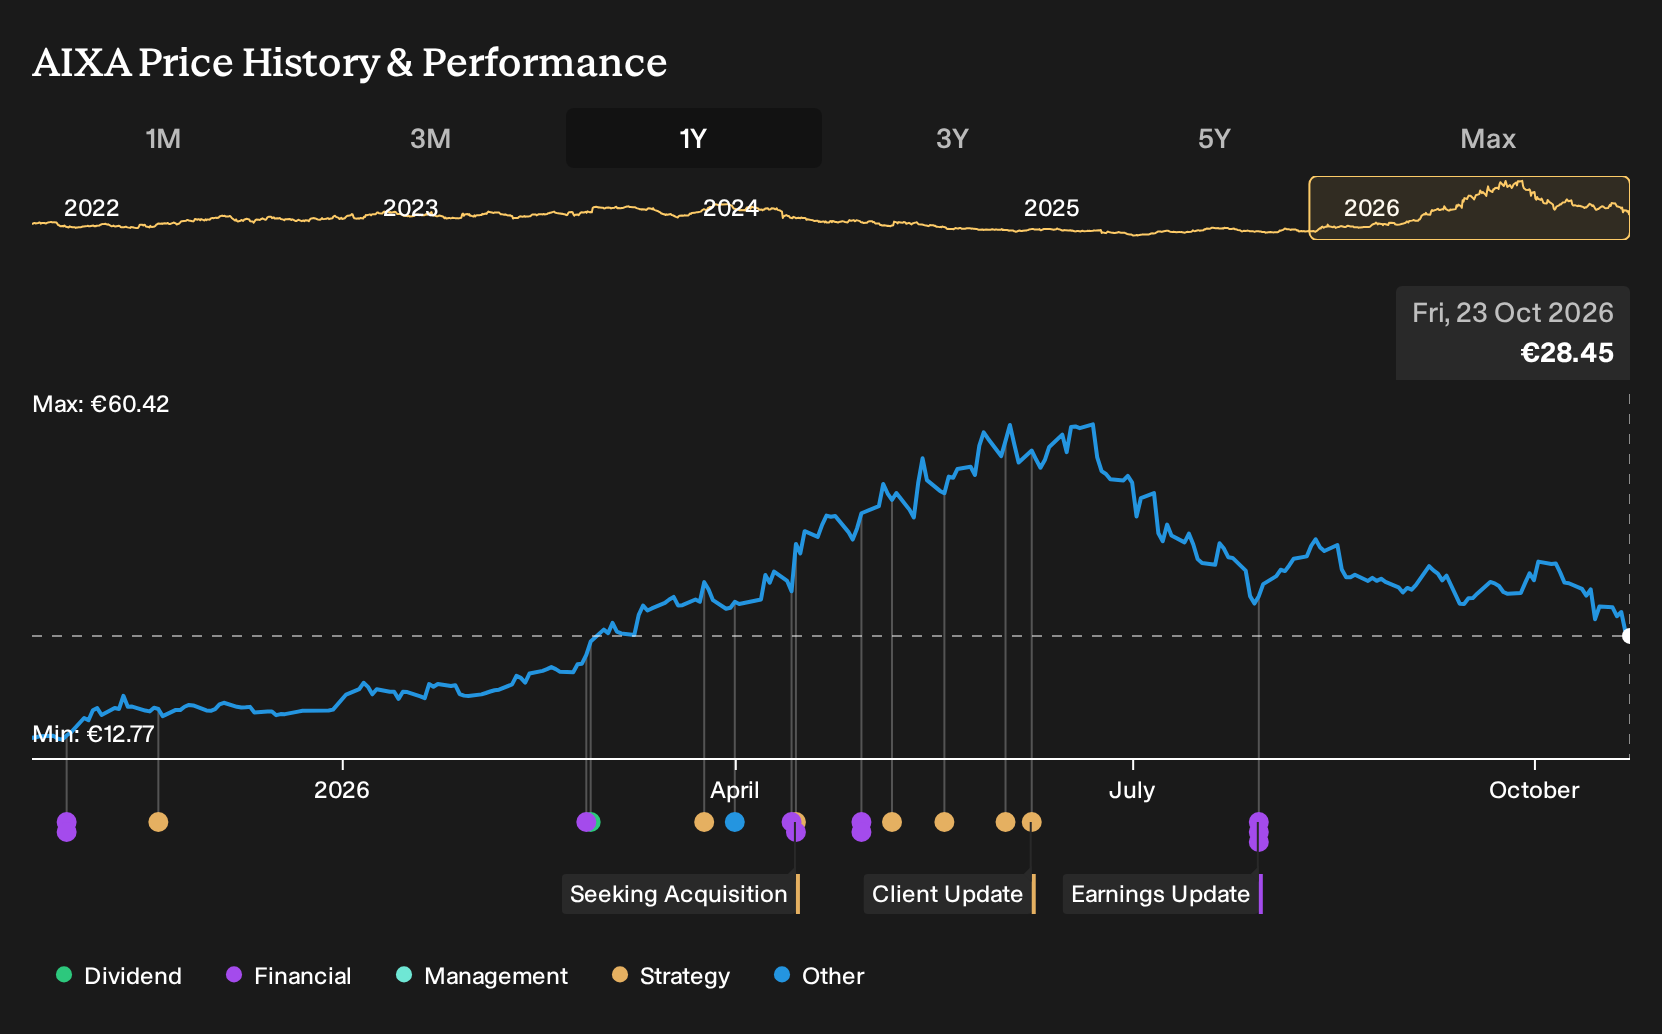
If you only skimmed the 2025 headlines about overcapacity in silicon carbide tools and scrapped factories in China, AIXTRON might have looked like a value trap, not a future winner. For AIXTRON shareholders, the return over the past year was 114.5%, including dividends. If you had been weighing those bullish AI-optoelectronics arguments against the bearish SiC glut at the time, what should have carried more weight in that decision?
The move put AIXTRON in the middle of this trade. Scan 55 AI infrastructure stocks for other companies exposed to it.
The Two AIXTRON Stories Investors Had To Compare
The shares cost €13.14 at the start of the period, and investors looking at AIXTRON had to choose which story about its future sounded more convincing.
The bullish Narrative argued that optoelectronics and compound semiconductors would open up a larger opportunity. Its Fair Value was €15.96, a rough guide to what that story implied the stock could be worth if those assumptions played out, based on expectations for tools like the G10 platform and recurring service revenue.
The bearish Narrative focused on SiC overcapacity and Chinese competition as the central threats. Its Fair Value sat at €10.9 and leaned hard on the idea that severe SiC wafer oversupply, idle tools, and rising domestic rivals in China could leave AIXTRON facing weak orders and thinner margins for an extended period.
What The Evidence Did To The AIXTRON Argument
The clearest new fact came from optoelectronics. AIXTRON reported strong AI related laser equipment demand, raised its 2026 outlook on higher AI orders, and later delivered Q3 2026 results that beat expectations while keeping full year guidance. That supported the bullish optoelectronics story, while the drop in total revenue from €137.415m in Q2 2025 to €115.105m in Q2 2026 and slightly lower net income kept the cautious case alive. Overall, the evidence cut both ways.
The lesson is simple. When a thesis hangs on one growth engine offsetting weakness elsewhere, track segment demand and order intake directly. Then compare that to total revenue and net margin to see whether the strong part of the story is carrying the rest of the business or just softening a slowdown.
What AIXTRON’s Price Now Asks You To Believe
AIXTRON shares now trade at €28.45, after a 114.5% gain over the past year. The selected bullish Narrative places its Fair Value above that level, with AI driven optoelectronics seen as the key driver rather than silicon carbide tools.
In that view, today’s price still underplays how much recurring service income and margin mix could change if the G10 led laser cycle develops into a much larger installed base.
"The sharp inflection in AI driven optoelectronics orders, with well over two thirds of Q1 2026 intake and 75% of Q2 equipment orders tied to lasers for 800G and 1.6T links, creates room for AIXTRON to convert a concentrated tool boom into a larger installed base that can support higher recurring service revenue and, over time, a richer margin mix as that base matures."
One Narrative disagrees with today's price. → See where this Narrative says AIXTRON should trade
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 33% below our estimate - manages fee based capital targeting renewable infrastructure, social assets and regional private equity.
- Company 2 - 18% below our estimate - scales teahouse openings while a membership program drives repeat orders and higher spend.
- Company 3 - 45% below our estimate - integrates a bank acquisition to widen its footprint and pursue cost savings.
Three companies from the same screener. Open the full list of 192 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com