


EN
How Investors May Respond To PayPal Stock Expanded Commerce Partnerships
- LianLian Global and Glance each announced new partnerships with PayPal, extending PayPal payout coverage, Venmo wallet access and in-app AI-powered checkout for social commerce, marketplaces and agentic shopping in the U.S. and nearly 100 markets.
- These deals push PayPal deeper into creator and AI-driven commerce, linking its global wallet network and Venmo ecosystem more directly to emerging shopping platforms and new payment flows.
- We will look at how PayPal Holdings' investment narrative is affected by its Glance in-app checkout and agentic commerce integration.
PayPal Holdings Investment Narrative Recap
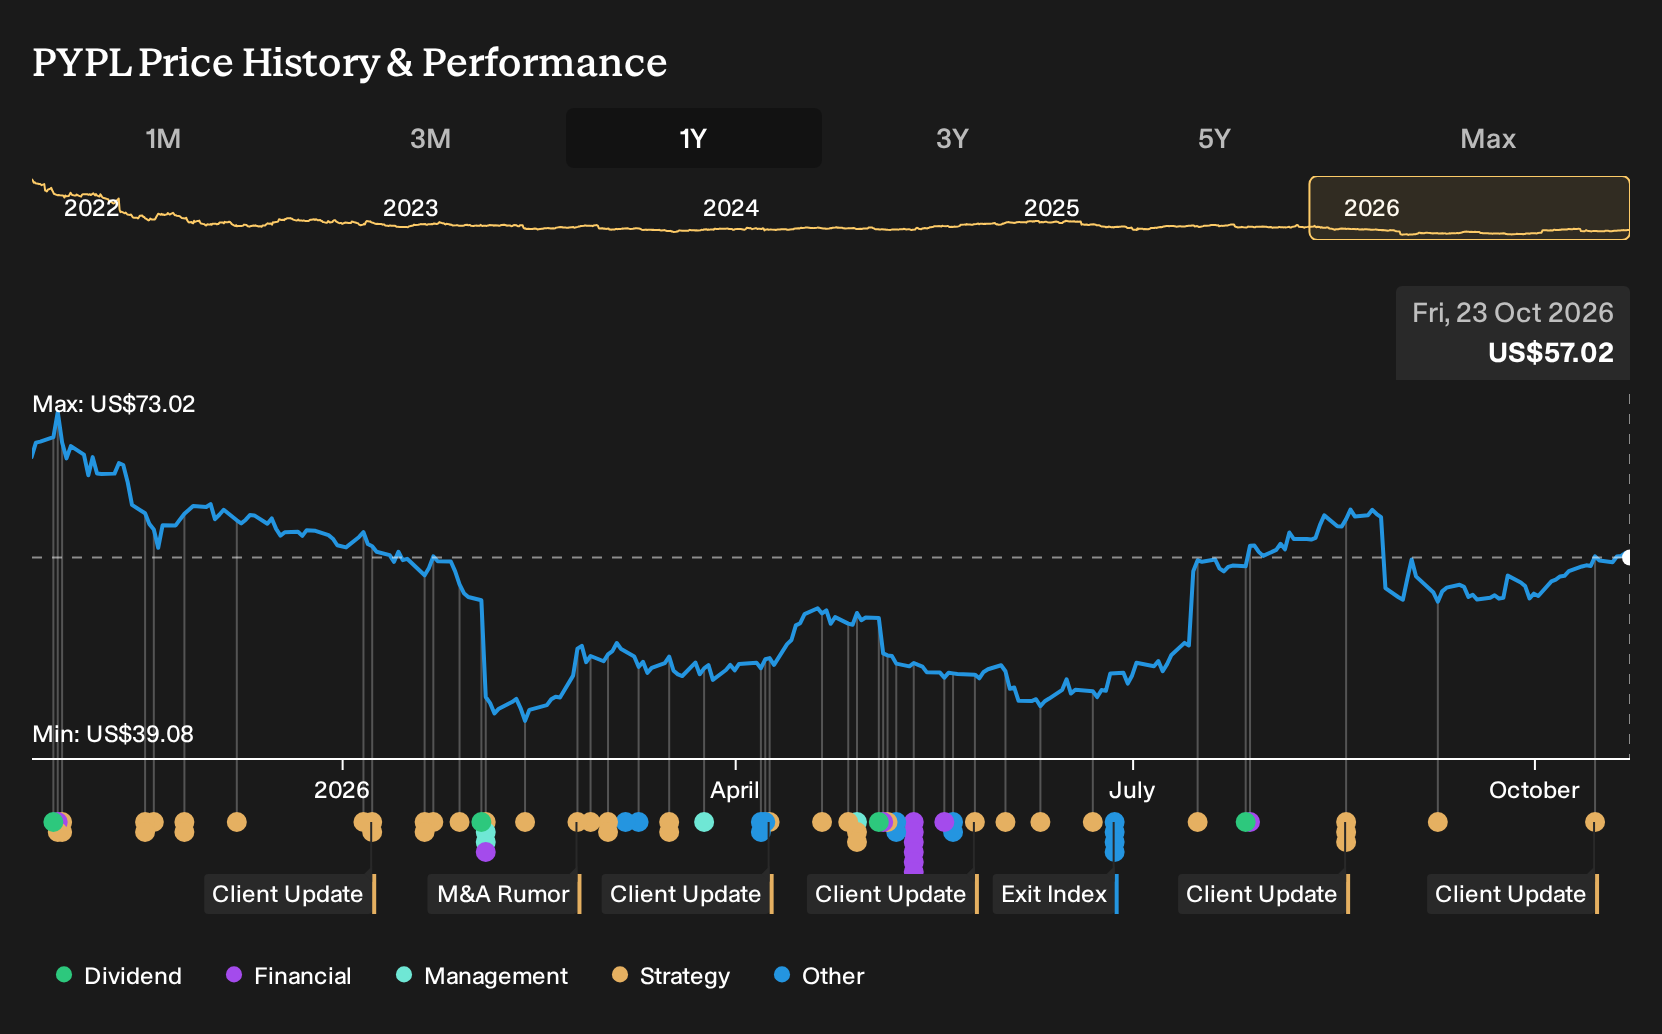
For PayPal Holdings, the core belief is that its large two sided network can keep finding new use cases, even while headline earnings are expected to decline slightly over the next three years. In the short term, the key swing factor is execution on the US$1.5b cost program, which management expects to ramp from Q4 2026. The biggest risk is that the mix shift toward lower take rate products and restructuring disruption could outpace those savings.
The LianLian and Glance deals tie directly into new payment flows such as AI agent checkout and creator payouts, but on their own they probably do not change that key cost versus margin debate in the near term. They matter more as proof that PayPal can plug its wallet, Venmo and merchant tools into newer commerce surfaces, at a time when cross border tariffs and European checkout pressures are weighing on parts of the franchise.
The Glance agentic commerce partnership is closest to the current AI checkout theme. It keeps PayPal inside the shopping moment for tens of millions of US consumers, rather than sending buyers away to a browser redirect. This aligns with management’s push to rebuild the consumer network and Venmo led engagement.
For you as a shareholder, the question is whether these real time data and in app checkout integrations can scale quickly enough to support transaction margin dollars while branded European flows and take rates face pressure. Analysts still highlight earnings compression risk and a Zacks Rank #4, so execution on cloud migration, cost savings and product delivery will likely matter more than any single agentic commerce launch over the next few quarters.
PayPal Holdings' current narrative points to revenues of US$38.7b and earnings of US$4.7b by 2029, based on analyst forecasts that assume about 4.3% yearly revenue growth and a decline in earnings of US$0.2b from US$4.9b today.
Uncover why PayPal Holdings' fair value suggests a valuation that aligns with its current price.
Exploring Other Perspectives
One alternate view treats PayPal’s cost program as the real catalyst, not AI checkout. Those bullish analysts were modelling faster revenue growth of 6.7% a year and earnings of US$6.3b by 2029, before this Glance and LianLian news. That more optimistic camp might revise forecasts meaningfully, while others stay cautious. Explore both angles.
Explore 24 other PayPal Holdings fair value estimates, including one that suggests as much as 122% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A great starting point for your PayPal Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PayPal Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PayPal Holdings' overall financial health at a glance.
Looking for more PayPal Holdings style investment ideas?
If you want to apply the same kind of thinking used on PayPal Holdings to a wider opportunity set, the Simply Wall St Screener can help you quickly filter for companies that match your own risk and return preferences.
- For investors who care most about quality at a reasonable price, start with a curated 27 high quality undervalued stocks that already screens for fundamentals and valuation in one place.
- If balance sheet strength is your first filter, focus on companies in the list of solid balance sheet and fundamentals (25 results) to see which businesses pair financial resilience with earnings power.
- Those hunting for less volatile ideas can narrow their search using the 30 resilient stocks with low risk scores and compare candidates side by side before committing fresh capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com