


EN
Rogers (ROG) Faces A Fair Value Debate, Is The Stock Still Cheap?
Recent Share Performance Context for Rogers
Rogers (ROG) has drawn fresh attention after a stretch of weaker trading, with the share price down about 3% over the past day and 10% over the past month.
The pullback sits against a year-to-date gain of roughly 35%, along with a total return of about 45% over the past year and a modest rise across the past 3 months.
For investors tracking the recent swings, Rogers now trades at US$124.96, with near term share price momentum fading after a weak 1 month patch. However, the 1 year total shareholder return remains firmly positive and signals a very different longer term experience.
Scan beyond Rogers's recent pullback and consider other tech-focused opportunities on our hand picked list of 21 high quality undiscovered gems.
Rogers has a rising share price over the year but a softer recent patch, which raises a simple question. Are you seeing a business catching up to fundamentals, or a swing in sentiment that the valuation no longer fully supports?
Most Popular Narrative: 35% Undervalued
Rogers closed at $124.96, while the most followed narrative pegs fair value at $193.33 using an 8.75% discount rate. This frames recent share weakness against a materially higher long term estimate.
Expansion into AI data center connectivity and cooling through next generation PTFE-based laminates that already meet and exceed M9 performance requirements with a path to M10, and direct-to-chip microchannel coolers now being prototyped with several major AI chip and data center customers, alongside management’s expectation that these adjacencies contribute meaningfully to roughly US$450 million of targeted incremental revenue by 2030, provides a potential new leg of growth and margin mix improvement.
See why 2 investors see Rogers as 35% undervalued.
Result: Fair Value of $193.33 (UNDERVALUED)
Still, the Rogers narrative leans heavily on ambitious margin targets and the ramp of its ceramic substrate plant, where underutilization or weaker EV demand could quickly challenge those assumptions.
Find out about the key risks to this Rogers narrative.
Another View on Rogers Using Market Multiples
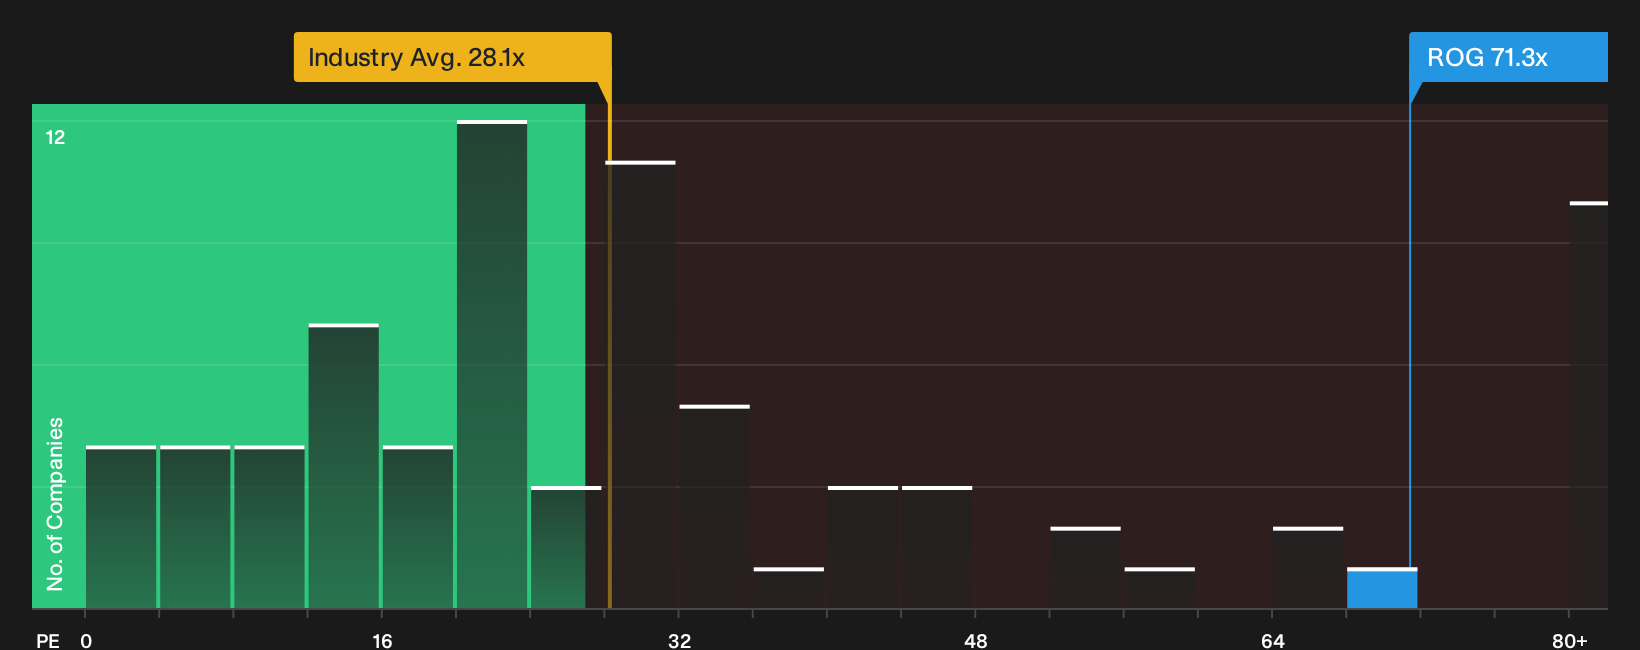
The narrative around Rogers leans on a fair value of $193.33, yet the current P/E of 71.3x sends a very different message. That figure is far above the US Electronic industry on 28.1x, the peer group on 60x and even the 38.9x fair ratio our models suggest the market could move toward over time. If sentiment cools or expectations reset, how comfortable are you owning something that far above its own fair ratio as well as sector and peer benchmarks?
To see how this pricing gap stacks up in more detail, including how the numbers compare with the fair ratio and sector averages, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Rogers can be useful, especially when some investors focus on risks and others on potential rewards. Move quickly, review the data that matters most to you, then anchor your view on the 3 key rewards and 1 important warning sign.
Looking for more Rogers investment ideas?
If Rogers has sharpened your focus, do not stop here. Use the Simply Wall St Screener to surface new opportunities that fit your checklist before they move away.
- Target resilient compounding opportunities by scanning our 27 high quality undervalued stocks based on stronger fundamentals and supportive valuations.
- Prioritize capital preservation and smoother portfolio swings by zeroing in on 30 resilient stocks with low risk scores that clear stricter risk filters.
- Strengthen your income stream by reviewing 5 dividend fortresses that pair higher yields with balance sheet discipline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com