


EN
Does Boeing (BA) Trade At A Premium After FAA Approval?
Boeing shares have fallen year to date, even as the business works through key certification milestones and defence contracts that can shape its earnings base. The question for investors is whether the current valuation of the stock still lines up with what the company is earning today.
- The share price is down 17.3% year to date. That puts the focus squarely on whether that move has brought the valuation closer to what Boeing's earnings can support.
- FAA approval for the 737 MAX 10 and continued involvement in areas like military robots and collaborative combat aircraft may support expectations for future profit streams. However, they also raise questions around timing, execution and how quickly those programs convert into cash and earnings.
- The analysts covering Boeing have run their own numbers. See what analysts think Boeing's shares could be worth.
The issue now is whether Boeing's current share price is justified by the earnings investors can reasonably tie to the business today.
If you want to stress test Boeing's valuation question against a wider set of listed companies tied to defence and security themes, it can help to scan 16 nuclear energy infrastructure stocks.
Where Does Boeing Sit on Earnings?
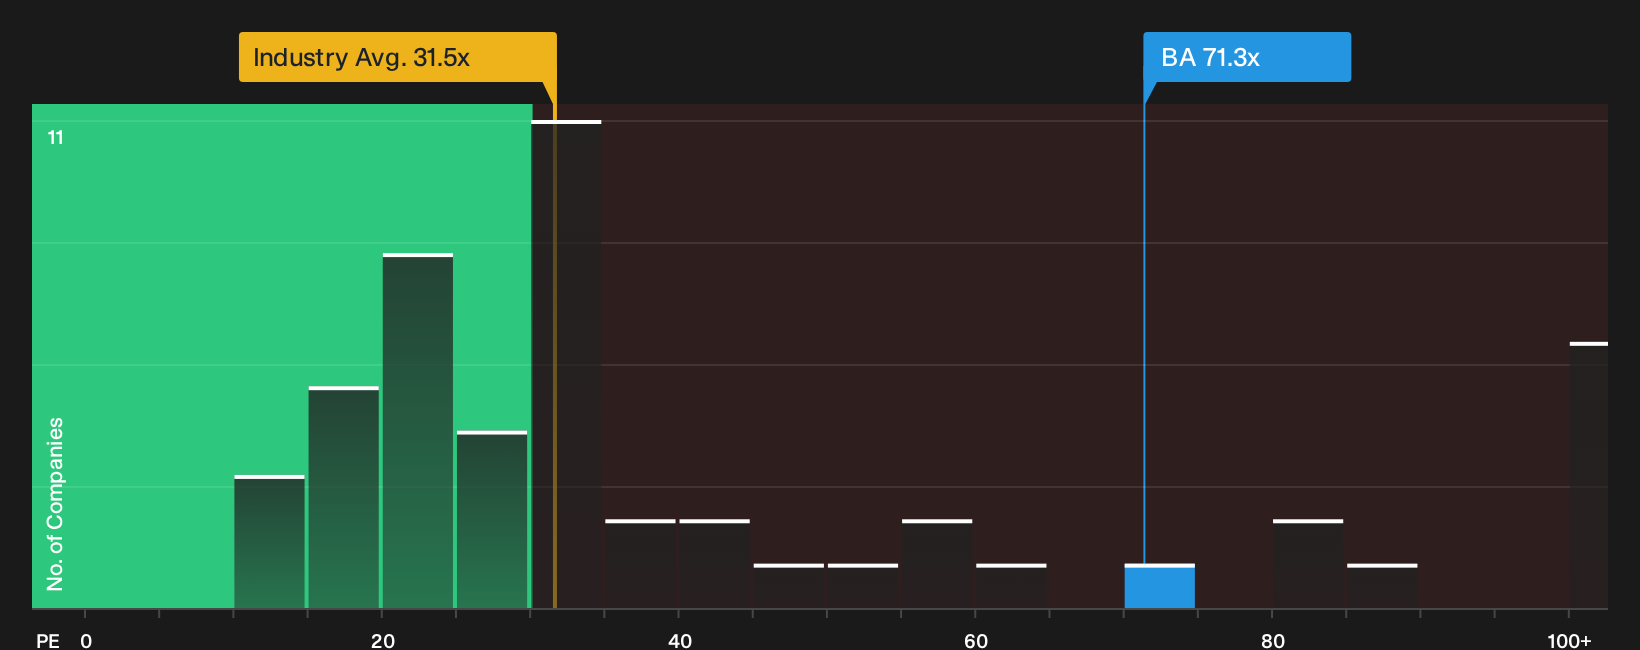
The P/E ratio is a useful yardstick for Boeing because earnings ultimately need to carry the weight of its aircraft backlog and defence contracts. Right now the stock trades on about 71.3x earnings, compared with an aerospace and defence sector average near 31.5x and a peer group around 28.2x. That is a hefty premium to what investors are paying for similar businesses on this metric.
The fair P/E multiple implied by the tailored model sits slightly below Boeing's current 71.3x, so the shares screen broadly in line with what that framework suggests rather than appearing clearly cheap or expensive. Despite the fresh 737 MAX 10 certification giving a clearer path to deliveries, the market is still pricing Boeing on an earnings multiple that assumes its profit base catches up to the headline valuation over time. Explore the numbers behind Boeing's P/E valuation.
The Boeing Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Boeing's valuation question leaves off by spelling out which paths for revenue, margins and earnings would need to play out for the stock to look meaningfully higher or lower than today's share price, using the Community page as the home for those scenarios. Rather than relying on a single P/E or one model, each narrative lays out its own fair value assumptions so you can later compare them with Boeing's reported results as they come through.
Community views on Boeing split between backlog driven upside and concern that a lot of recovery already sits in the price.
Bull case: 38% undervalued
"Boeing's record commercial and defense backlog, including over 6,200 airplanes and a total of US$715b in contracted work, gives management room to prioritize higher margin delivery slots and contract renegotiations…"
Discover why this Narrative puts Boeing at 38% undervalued.
Bear case: 18% overvalued
"But Commercial Airplanes still loses money, and the second half has to carry an unusual load…"
Explore why this Narrative puts Boeing at 18% overvalued.
One more Boeing factor to weigh before making a move
There is a whole other lens on Boeing that sits outside historical results and current multiples, which is what professional analysts think the income statement looks like a few years from now, and how that stacks against today's price. Explore where analysts expect Boeing to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com