


EN
Freshpet (FRPT) Stock Looks Fully Valued As Earnings Support Stays Thin
Freshpet has delivered a mixed journey for shareholders, with the stock up over the past year but still showing a sizeable decline over five years. That kind of path naturally raises a pointed question for anyone looking at the shares today: whether the current price makes sense when set against the company’s earnings.
- Over the past 5 years the share price has fallen 58.9%, which puts the focus squarely on whether the underlying earnings story now lines up with where the stock trades.
- The business model leans on scaling premium pet food through refrigerated retail placement, which can influence both cost structure and future profit margins in ways that matter directly for an earnings based valuation.
- There is a second opinion on Freshpet worth weighing. See what analysts think Freshpet's shares could be worth.
The stock’s next move may depend on whether Freshpet’s current earnings profile provides enough support for the price investors are being asked to pay today.
If you are weighing whether Freshpet’s earnings justify its current valuation, it can help to compare that same question across a wider set of companies using 27 high quality undervalued stocks.
Is Freshpet Getting Expensive on Earnings?
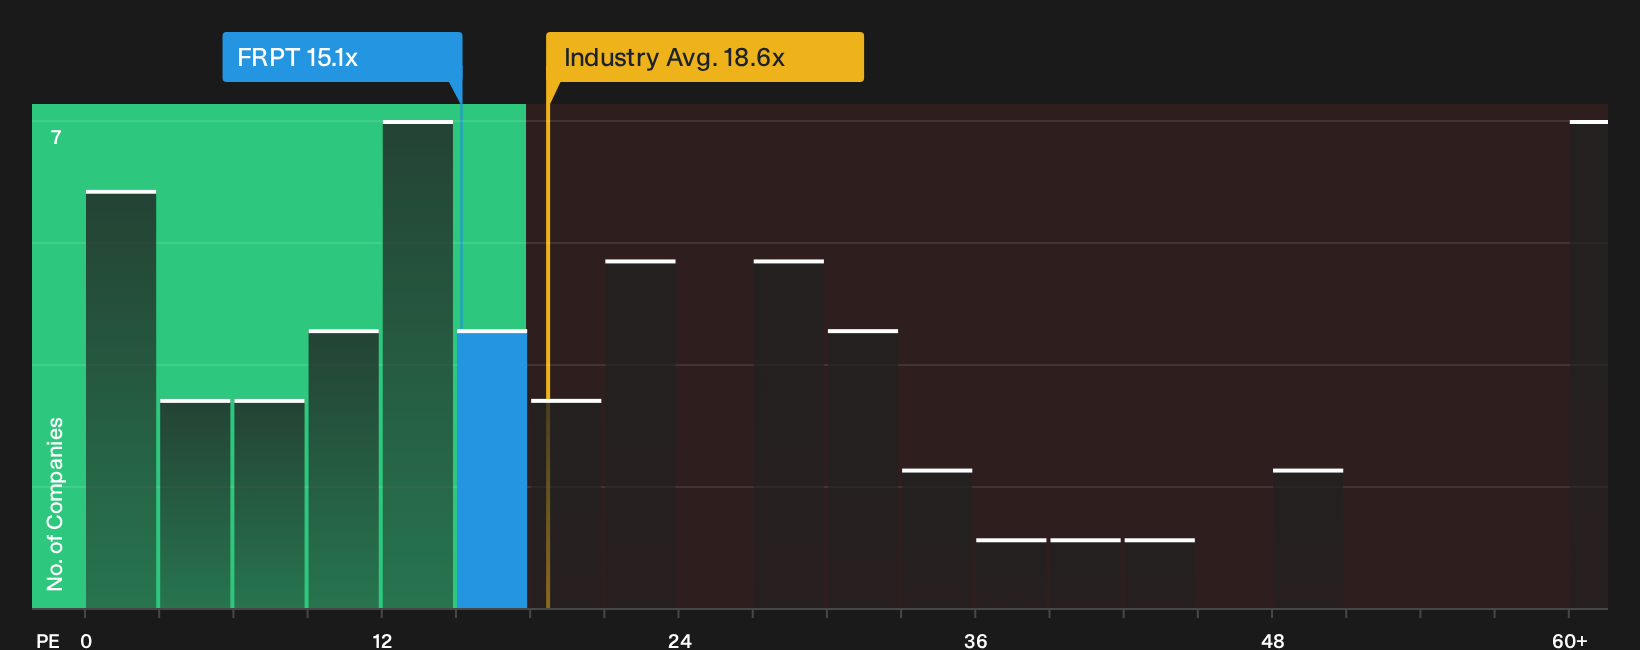
The P/E ratio is a useful lens for Freshpet because earnings ultimately need to support any long run share price. On this measure, Freshpet trades on about 15.1x earnings, which is below the Food industry average of roughly 18.6x and well under the peer group level near 26.2x. That kind of gap suggests the market is not giving the stock the same earnings multiple as many comparable businesses.
The Fair Ratio model, which looks at factors like the company’s growth potential, profitability profile, sector and risk, points to a higher P/E than where Freshpet trades today. Since the current 15.1x sits above that tailored benchmark, the shares screen as overvalued on this framework, even if they look cheaper than many listed peers on a simple comparison. That tension is what you need to weigh before deciding whether the multiple on Freshpet makes sense for your own return expectations. Explore the numbers behind Freshpet's P/E valuation.
The Freshpet Narrative: What Would Justify Today's Price?
Freshpet’s valuation puzzle only really comes into focus once you spell out what kind of future the current share price is implicitly assuming. Simply Wall St Narratives on the Community page do that by setting out clear scenarios for Freshpet’s growth, margins and earnings, and each one frames a fair value as a thesis about the business that you can track over time rather than treating it as a one off snapshot.
One of the top community narratives on Freshpet: roughly fairly valued
"The current numbers and active share repurchase program imply that the market prices Freshpet as a company where legal, cost, and execution risks still heavily discount the value of its growing revenue base and margin targets..."
Discover why this Narrative puts Freshpet at roughly fairly valued.
Freshpet’s price is only one side of the decision
For any long term holder, the next question is who is actually steering Freshpet, how their incentives line up with yours, and whether that pay structure supports the story the valuation is telling. See who runs Freshpet and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com