


EN
Did Higher Earnings Forecasts Just Shift Cullen Frost Bankers (CFR) Investment Narrative?
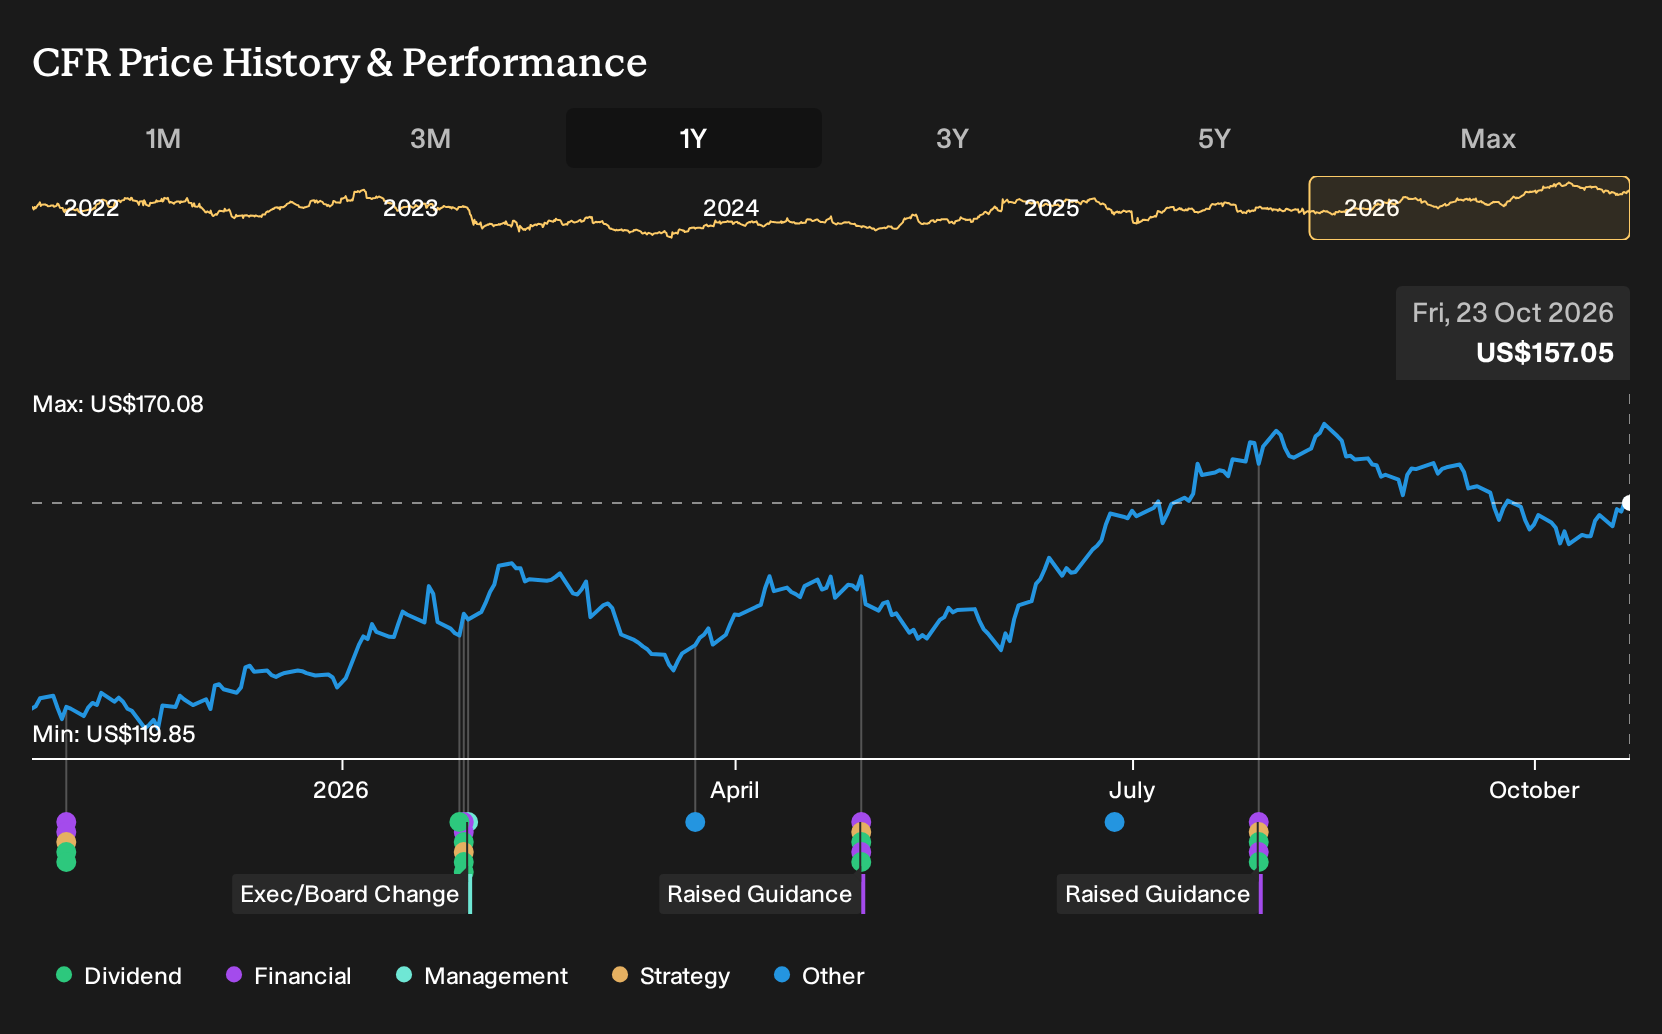
- Cullen/Frost Bankers recently drew attention as analysts projected higher year over year earnings and revenue for the September 2026 quarter, following a run of consensus earnings beats.
- The focus now falls on how that expected earnings strength reflects underlying trends in Texas focused lending, deposit gathering, and fee based banking services.
- We will look at how the investment narrative for Cullen/Frost Bankers is shaped by expectations for stronger quarterly earnings and revenue performance.
Cullen/Frost Bankers Investment Narrative Recap
To own Cullen/Frost Bankers, you need to be comfortable with a Texas centric lender that leans hard into relationship banking, physical branches, and disciplined credit culture. The near term story depends on whether core loans, deposits, and fee businesses in that region continue to support earnings while costs for branch builds and technology remain under control.
The September 2026 earnings expectations raise the stakes on that balance. A stronger report would reinforce confidence in the branch expansion and customer acquisition plan. A softer outcome would focus attention on concentrated Texas exposure, competitive pricing pressure, and whether credit costs or funding expenses are starting to rise.
The most relevant development is the recent increase in earnings estimates for the September 2026 quarter, alongside expectations of higher revenue. That revision effectively turns the upcoming October 29 report into a key checkpoint on whether Cullen/Frost Bankers is converting its guidance and branch growth into tangible operating momentum.
For you as a shareholder, the catalyst is straightforward. If reported results are in line with the higher earnings expectations, it supports the view that Texas expansion, mortgage platform growth, and ongoing customer wins are progressing according to plan. If results fall short, the focus shifts back to concentration risk in Texas, intense deposit competition, and the cost of running a branch heavy model.
Cullen/Frost Bankers' outlook forecasts revenue of US$2.6 billion and earnings of US$716.4 million by 2029. This is based on an assumed 5.1% annual revenue growth rate and an earnings increase of about US$47 million from US$669.4 million today.
Uncover why Cullen/Frost Bankers' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community currently span roughly US$175 to US$257 per share for Cullen/Frost Bankers, so retail views already stretch across a wide band. Those opinions pre date the latest earnings optimism, so you need to weigh them against Texas concentration risk and cost pressure, and then explore more community viewpoints before relying on any single number.
Explore another Cullen/Frost Bankers fair value estimate, including one that suggests it could be worth just $174.86.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Cullen/Frost Bankers research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cullen/Frost Bankers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Cullen/Frost Bankers' overall financial health at a glance.
Looking for more Cullen/Frost Bankers sized ideas?
If you want to stress test your thesis on Cullen/Frost Bankers and build a broader watchlist, the Simply Wall St Screener can help you quickly scan for other stocks that match your preferences on quality, value, income, or resilience.
- For investors hunting for resilient balance sheets rather than headline excitement, start by reviewing the list of solid balance sheet and fundamentals (25 results) to see which companies keep debt and liquidity tightly under control.
- If capital protection sits high on your priority list, narrow your search using the 30 resilient stocks with low risk scores and focus on businesses with more measured risk profiles.
- For readers who want early stage opportunities with cleaner financials than the typical microcap, filter the market through the 7 elite penny stocks with strong financials and concentrate on smaller stocks that still carry solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com