


EN
Is Nu Holdings (NU) Undervalued After Brazil License Pressure And Its CTO Resignation?
Why Nu Holdings Is Back In Focus
Nu Holdings (NYSE:NU) is juggling two big shifts at once. Brazil’s central bank is pushing Nubank toward a full banking license by 2026, while the group’s Chief Technology Officer has chosen to resign.
Recent price action shows Nu Holdings trying to balance these regulatory and leadership headlines with investor expectations. The US$15.16 share price comes after a 1-month share price return of 11.31%. However, the year-to-date share price return is down 10.93%, while the 3-year total shareholder return of 89.26% points to strong longer term momentum despite a 1-year total shareholder return decline of 4.29%.
Spot opportunities beyond Nu Holdings by checking a curated set of digital finance players and other high growth financial platforms in the 21 high quality undiscovered gems.Nu Holdings now trades about 7% below one intrinsic value estimate and roughly 20% under the average analyst target after its recent swing. Is that a sensible cushion for the regulatory and tech upheaval, or an overreaction investors might be mispricing?
Most Popular Narrative: 33% Undervalued
Nu Holdings is priced at $15.16 while the most followed narrative assigns a fair value of $22.74. The gap between price and thesis is wide and grounded in a detailed operating story rather than a simple headline multiple.
The first is that Nu Holdings is currently trading at a historically low multiple relative to its growth profile. At $12.20 per share, the market is assigning it a 2026 forward P/E of just 13.7x based on an estimated earnings per share of $0.89, for a company growing that same earnings figure at roughly 48% annually. The 36% decline from its January highs ($18.98) has been driven by higher credit loss provisions in the first quarter and macroeconomic deterioration in Brazil, not by any change in the quality of the business model. That potentially creates an attractive entry window.
See why 107 investors see Nu Holdings as 33% undervalued.
Result: Fair Value of $22.74 (UNDERVALUED)
Still, the narrative around Nu Holdings could unravel quickly if Brazilian credit conditions worsen again or if regulatory demands around its banking license tighten materially.
Find out about the key risks to this Nu Holdings narrative.
Another Take On Nu Holdings’ Valuation
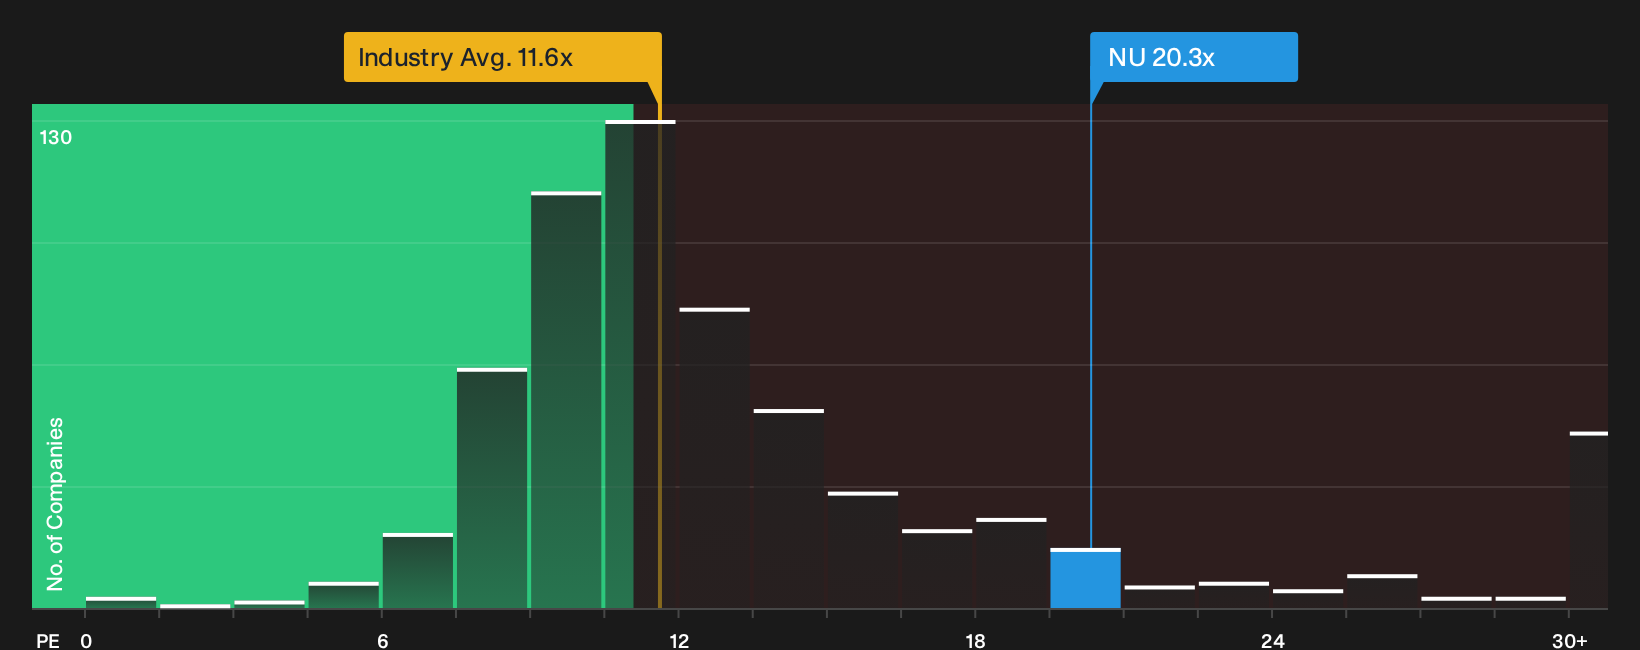
Multiples provide a different perspective. Nu Holdings trades on a P/E of 20.3x compared with 11.6x for the US Banks industry and 14.3x for its peer group, while the fair ratio sits at 17.6x. That premium can signal quality, but it also raises the question of how much positive information is already reflected in the share price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Nu Holdings often create the real opportunity, so check the data for yourself, weigh both sides, and decide quickly whether the balance of 4 key rewards and 2 important warning signs.
Ready To Hunt Beyond Nu Holdings?
Do not stop with a single ticker. Use the Simply Wall Street Screener to turn scattered ideas into a focused watchlist before the next round of opportunities moves without you.
- Target resilient balance sheets and steady fundamentals through a curated list of solid balance sheet and fundamentals (25 results) that helps you sidestep fragile businesses.
- Pursue upside potential with a focused 27 high quality undervalued stocks designed to spotlight stronger fundamentals at prices that may not fully reflect them yet.
- Lock in income ideas by scanning a hand picked 5 dividend fortresses that highlights higher yielding payouts with an emphasis on endurance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com