


EN
Is Applied Industrial Technologies (AIT) Cheap After Board Changes And Automation Growth?
Board refresh puts governance and automation focus in the spotlight
Applied Industrial Technologies (AIT) is refreshing its board just as its automation franchise gains traction. Recent appointments of Pamela J. Tomczik and Michael L. Olosky give investors fresh perspectives on governance and oversight.
Recent appointments come at a time when Applied Industrial Technologies’ share price has cooled in the short term, with the stock down over the past month and quarter. However, the year-to-date share price return and multi year total shareholder returns remain firmly positive and indicate momentum built over a longer horizon.
Scan beyond Applied Industrial Technologies and identify other automation and industrial plays with momentum using the hand picked 95 robotics and automation stocks in the same corner of the market.
Applied Industrial Technologies has cooled after a strong multi year run, yet still trades below analyst targets and one intrinsic estimate. Has most of the upside already played out, or is the valuation gap still meaningful?
Most Popular Narrative: 21% Undervalued
The most followed valuation view on Applied Industrial Technologies pegs fair value at $400, above the last close of $317. This sets a clear gap for investors to weigh.
Management has raised intermediate financial targets to US$7b in sales and 14% EBITDA margin over the next five years and has maintained net leverage near 0.2 to 0.3x EBITDA while deploying nearly US$1b of capital in FY25 and FY26, which leaves room for continued investment in growth initiatives that can support future earnings and free cash flow.
See why 15 investors see Applied Industrial Technologies as 21% undervalued.
Result: Fair Value of $400 (UNDERVALUED)
Still, softer demand across machinery and energy end markets, along with heavier dependence on acquisitions, could pressure Applied Industrial Technologies if expected margin gains do not materialise.
Find out about the key risks to this Applied Industrial Technologies narrative.
Another View: Applied Industrial Technologies Looks Expensive On Earnings
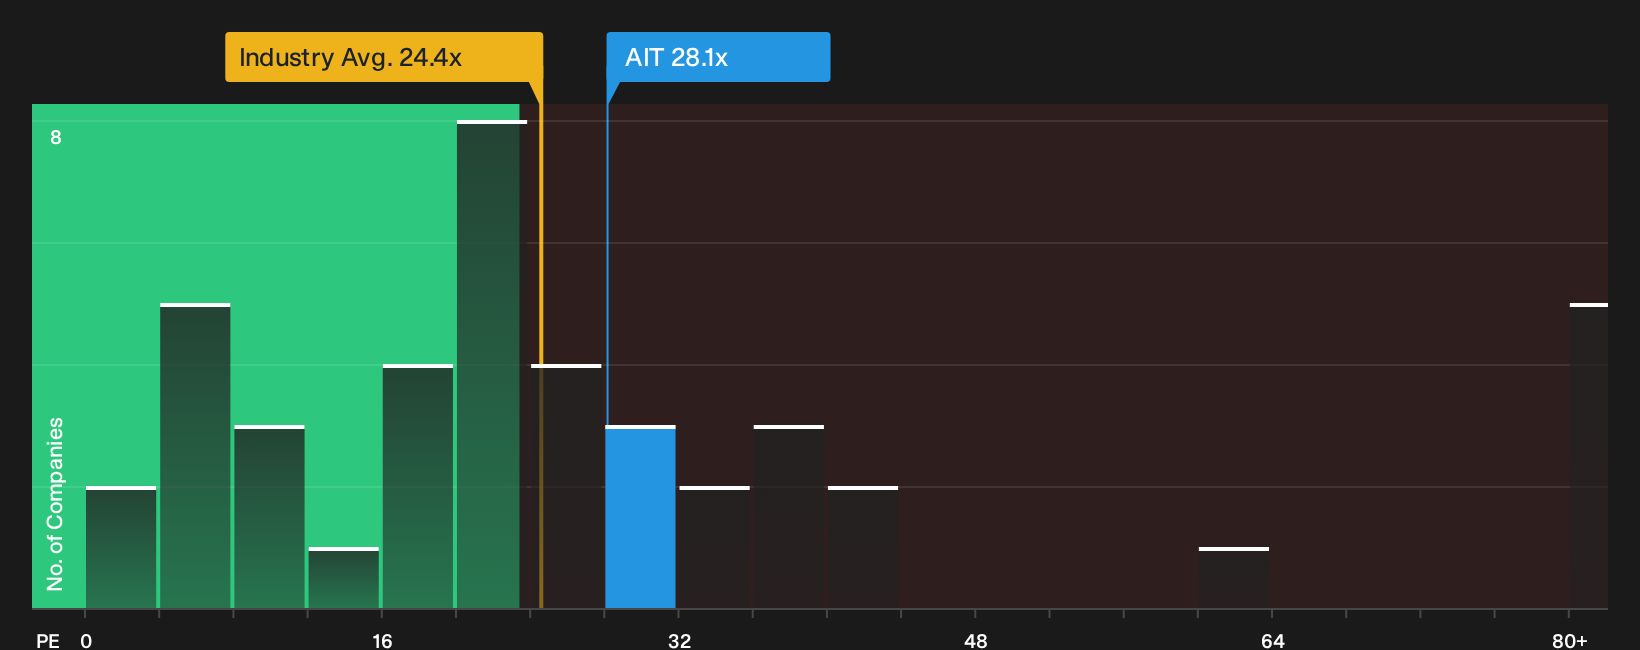
While the most popular narrative pegs Applied Industrial Technologies at a fair value of $400, the current P/E of 28.1x tells a different story. That multiple sits well above both the fair ratio of 19.6x and the US Trade Distributors average of 24.6x, as well as a 23.8x peer group mark.
If the share price eventually drifts toward that lower fair ratio, the adjustment would fall on you as a shareholder, not on the income statement. This raises the question of how comfortable you are paying a premium earnings multiple on top of an already optimistic $400 fair value view.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Applied Industrial Technologies can pull you in both directions, so act promptly, study the data carefully, and consider both the risks and rewards in the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Applied Industrial Technologies?
If you only focus on Applied Industrial Technologies, you could miss other opportunities that fit your style even better, so broaden your watchlist before the market moves.
- Hunt for quality at a discount by scanning companies that pass the 27 high quality undervalued stocks and see which businesses match your return and risk expectations.
- Lock in consistency by reviewing the 5 dividend fortresses and focus on companies aiming to pair higher yields with resilient cash generation.
- Dial down volatility by filtering for steadier balance sheets using the 30 resilient stocks with low risk scores and build a core list of potential long term holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com