


EN
Yancoal Australia (ASX:YAL) Reports Higher Output, Is It A Bargain Or Fully Priced?
What Yancoal Australia’s Latest Quarter Tells Investors
Yancoal Australia (ASX:YAL) has just released third quarter and nine month 2026 production and sales figures, reporting higher coal output alongside lower quarterly attributable sales volumes compared with the same period a year earlier.
Yancoal Australia’s recent production update and the scheduled Q3 2026 earnings call have arrived alongside a 20.16% year to date share price return and a 14.82% one year total shareholder return. This points to momentum that has cooled slightly in the last quarter but still reflects a stronger multi year track record, with a 268.01% five year total shareholder return.
Spot opportunities across coal and resource producers with similar volatility and return profiles by scanning the hand picked 4 high quality undervalued stocks.Yancoal Australia now trades at a steep intrinsic discount while the share price has already run hard over several years. Is that gap a genuine opportunity, or a simple reflection of market caution around coal exposure?
Preferred P/E of 27x: Is it justified?
On simple earnings terms, Yancoal Australia is not cheap. The stock trades on a P/E of 27x, which is being applied to a business with a last close share price of A$6.02 and forecast earnings growth of 17.36% per year rather than extremely rapid expansion.
The P/E ratio compares what investors pay today for each dollar of current earnings. For a coal producer like Yancoal Australia, this matters because profits can be heavily influenced by commodity prices and volume swings, so paying a high multiple usually implies the market is comfortable with those earnings and expects them to hold up or improve.
Here, the current P/E of 27x sits above the estimated Fair P/E of 21.2x and above the Australian Oil and Gas industry average of 16x. That gap suggests the market is putting a richer price on Yancoal Australia’s earnings than both peers and the level our fair ratio work suggests the valuation could move toward if sentiment or earnings expectations normalise.
Explore the SWS fair ratio for Yancoal Australia.
Result: Price-to-Earnings of 27x (OVERVALUED)
Still, Yancoal Australia faces obvious risks if coal pricing weakens sharply or if tighter environmental policy reduces demand from key Asian customers.
Find out about the key risks to this Yancoal Australia narrative.
Another View on Yancoal Australia’s Value
That rich 27x P/E paints Yancoal Australia as expensive, yet our DCF model points the other way. With the shares at A$6.02 and the SWS DCF model indicating a future cash flow value of A$43.57, the stock screens as heavily undervalued. Which signal would you trust more: the multiple or the cash flows?
Look into how the SWS DCF model arrives at its fair value.
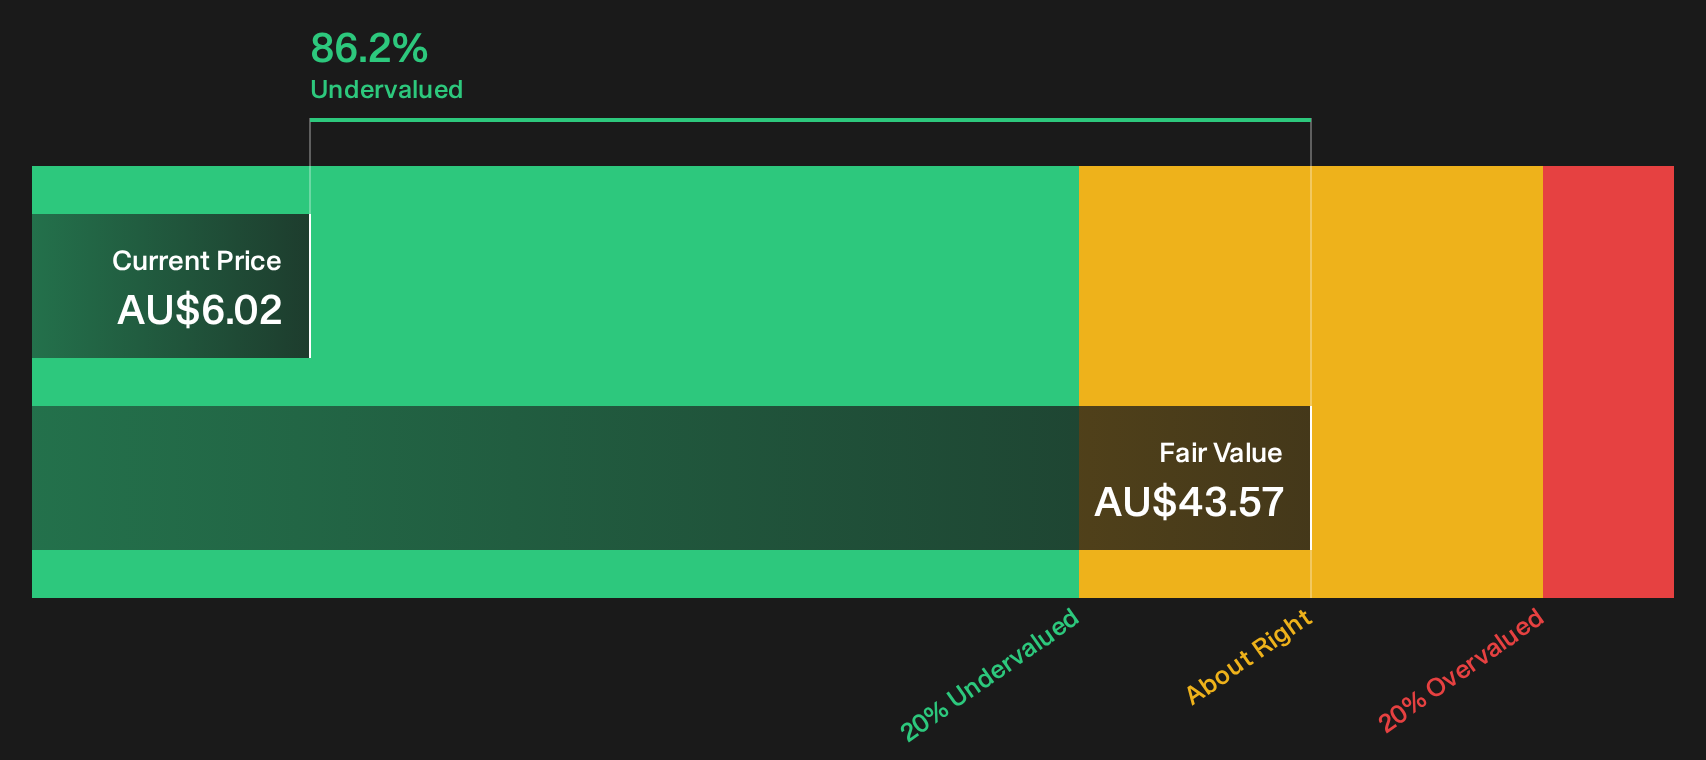
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yancoal Australia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Yancoal Australia can feel uncomfortable, which is exactly why it helps to move fast and check the underlying data yourself. To see both the upside and the concerns set out clearly, walk through the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Yancoal Australia?
Do not stop with a single stock when a broader watchlist of potential opportunities can sharpen your next investing move and help you stay competitive.
- Target potential mispricing by lining up quality businesses against their current tags through the 4 high quality undervalued stocks.
- Strengthen your sleep at night factor by focusing on the 6 resilient stocks with low risk scores that combine resilience with more measured risk profiles.
- Spot early stage potential by scanning the 15 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com