


EN
How Earnings Beat Will Impact ICF International Stock Investors
- ICF International recently reported quarterly revenue of US$474.5 million, roughly flat year on year, while beating analyst EPS estimates and slightly topping full year EPS guidance, and management reaffirmed the earnings outlook.
- The firm also highlighted a US$9.3b business development pipeline and said a DCF assessment places intrinsic value roughly in line with the current share price, which supports management’s confidence in the existing guidance.
- We will now examine how ICF International's investment narrative is affected by this reaffirmed earnings outlook and raised full year guidance.
Compare ICF International's reaffirmed outlook and valuation with a curated set of resilient peers by scanning our 30 resilient stocks with low risk scores, which aims to balance opportunity with lower risk scores.
ICF International Investment Narrative Recap
To own ICF International, you need to be comfortable with a mix shift story. The thesis leans on commercial energy, international government, and state and local work carrying more of the load while federal revenue remains under pressure. The reaffirmed earnings outlook suggests management still sees that mix supporting margins despite flat quarterly revenue.
In the short term, the key catalyst is whether that US$9.3b pipeline turns into bookings that lift backlog and keep the book to bill ratio healthy. The biggest risk is that federal funding delays and a declining backlog persist. The latest results do not remove that risk, but they also do not materially worsen it.
The reaffirmed outlook paired with a DCF value roughly in line with the current share price is the announcement that matters most here. It effectively indicates that management believes the commercial and international opportunities and efficiency programs are enough to support the existing earnings path, even with federal revenue still soft.
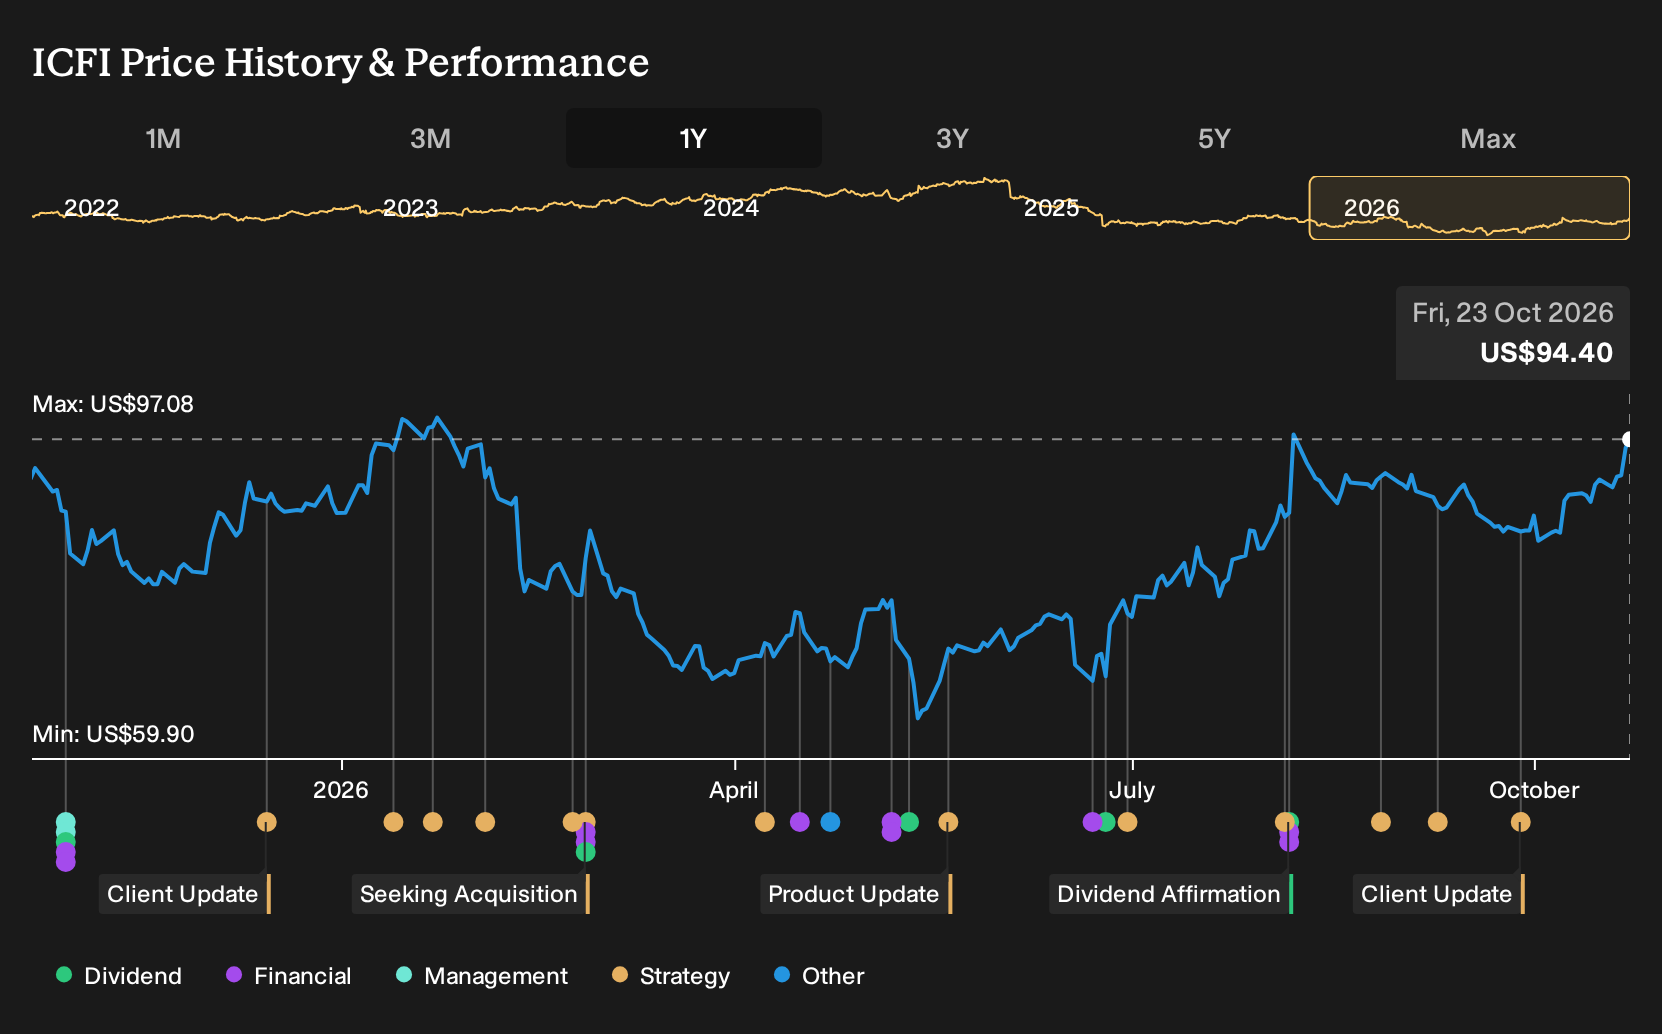
For catalysts, the raised full year EPS guidance versus peers and the 9.3% move in ICF International since reporting put more attention on execution. Stronger conversion of the US$9.3b pipeline into contracts, particularly in commercial energy and AI enabled government work, could support that guidance. Missed awards or slower procurement would test it quickly.
ICF International's current narrative links analyst forecasts of US$2.2b revenue and US$149.6 million earnings by 2029 to an assumed 7.1% yearly revenue growth rate, with profits rising from US$88.5 million today to that 2029 consensus level. This implies roughly a 69% earnings increase off the current base.
Uncover how ICF International's fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For ICF International, the most optimistic analysts frame the catalyst very differently. They focus on cash generation. Before this earnings update, the bullish camp was working off revenue forecasts around US$2.3b and earnings of about US$152.8 million by 2029. Your takeaway is simple. Opinions already spanned a wide range and this fresh guidance could push those views further apart.
Explore another ICF International fair value estimate, including one that suggests as much as 14% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ICF International research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for ICF International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ICF International's overall financial health at a glance.
Looking For More Investment Ideas Beyond ICF International?
If ICF International has sharpened your view on what you want from a holding, it can be useful to line it up against other opportunities that share the traits you care about most.
- Focus on quality at a discount by scanning a curated pool of companies trading below their estimated worth through the 27 high quality undervalued stocks.
- Prioritize balance sheet strength and resilience across market cycles by sorting through our list of solid balance sheet and fundamentals (25 results).
- Target income focused opportunities by reviewing a universe of higher yielding payers using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com